Torrent Power (TORNTPOWER) Q2 FY27 Profit Growth Lags Revenue as Nabha Acquisition Weighs on Margins
The utility's revenue surged 24% year-on-year, but profit grew only 13% as higher finance costs and depreciation from its new acquisition squeezed margins.
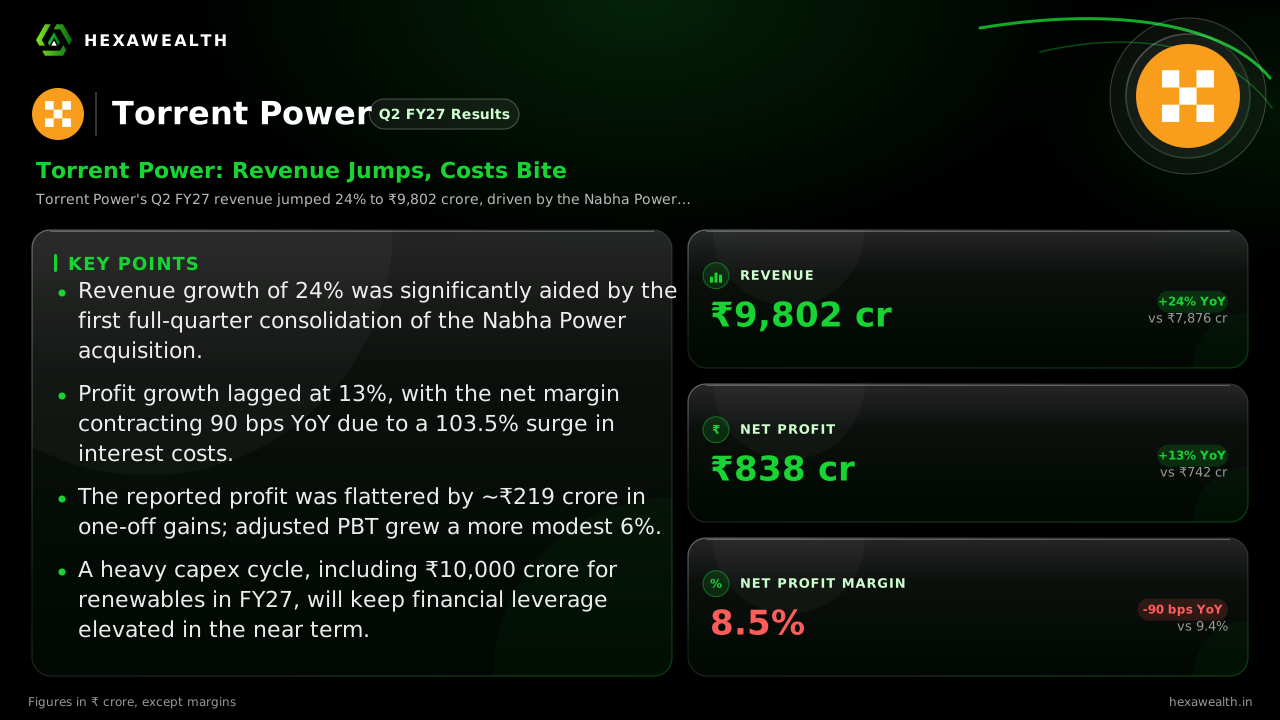
Torrent Power's Q2 FY27 revenue jumped 24% to ₹9,802 crore, driven by the Nabha Power acquisition and strong distribution. However, profit growth was limited to 13% as interest costs more than doubled, compressing net margins.
For Torrent Power, the September quarter was about absorbing a major acquisition while navigating a high-demand power market. The headline showed a 24% revenue jump, but the real story was the cost of funding that growth.
Revenue rose to ₹9,802 crore, while profit reached ₹838 crore. The net profit margin contracted 90 basis points year-on-year to 8.5%. A strong sequential rebound from Q1 is clear, but profitability remains under pressure.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 9,801.58YoY +24% | 8,124.15 | 7,876.00 |
| Profit (₹ Cr) | 837.96YoY +13% | 661.85 | 741.55 |
| Net Margin (%) | 8.5YoY -9.6% | 8.1 | 9.4 |
Why the headline profit flatters
The reported profit before tax of ₹1,131 crore included about ₹219 crore of non-recurring items, according to management commentary cited by Investing.com. This comprised indemnity income from the Nabha seller and gains from unwinding LNG hedges. Excluding these, adjusted PBT grew a more modest 6% year-on-year.
The Nabha Power acquisition, completed in June, was the quarter's dominant force. It contributed its first full quarter of revenue and an EBITDA of ₹142 crore, as noted in the AlphaStreet transcript. This drove the top-line surge but came with a heavy financial burden.
The costs that will not fall soon
Financing the Nabha deal more than doubled the interest expense to ₹439 crore. Management explained on the call that this included ₹70 crore from Nabha's own debt and another ₹70 crore from borrowings to fund the acquisition. Higher capitalisation in the renewable segment also pushed up depreciation.
These are structural costs that will persist. The company's debt-to-equity ratio stands at 0.72, and it has guided for a massive ₹10,000 crore in renewable capex for FY27 alone. The heavy investment cycle is pressuring near-term returns.
A renewable-led future, but timing is key
Operationally, the distribution business and renewables provided a counterbalance. The AlphaStreet transcript noted improved volumes and efficiency in franchise distribution, while renewable EBITDA rose to ₹148 crore on better plant load factors.
Management, cited by Investing.com, expects to commission 1.0–1.2 GW of renewable capacity in FY27. This pipeline is critical for long-term margin improvement as these assets come online. For now, investors are weighing strong execution against a leveraged balance sheet and compressed margins.
Key Points
- Revenue growth of 24% was significantly aided by the first full-quarter consolidation of the Nabha Power acquisition.
- Profit growth lagged at 13%, with the net margin contracting 90 bps YoY due to a 103.5% surge in interest costs.
- The reported profit was flattered by ~₹219 crore in one-off gains; adjusted PBT grew a more modest 6%.
- A heavy capex cycle, including ₹10,000 crore for renewables in FY27, will keep financial leverage elevated in the near term.
Hexa Perspective
This quarter underscores the transition Torrent Power is navigating. The Nabha acquisition provides immediate revenue scale but at the cost of higher fixed financial charges, squeezing margins. The path to improved profitability now hinges on the timely commissioning of its large renewable pipeline, which promises better margins than the legacy thermal portfolio. The market's neutral stance, with consensus targets implying upside but highlighting execution risk per Stockwatch, reflects this wait-and-see phase. Earnings accretion from new projects must outpace the rising cost of capital for the stock to re-rate.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.