Thrive Future Habitats (THRIVE) Q2 FY27' Losses Deepen as Real Estate Pivot Fuels Cost Surge
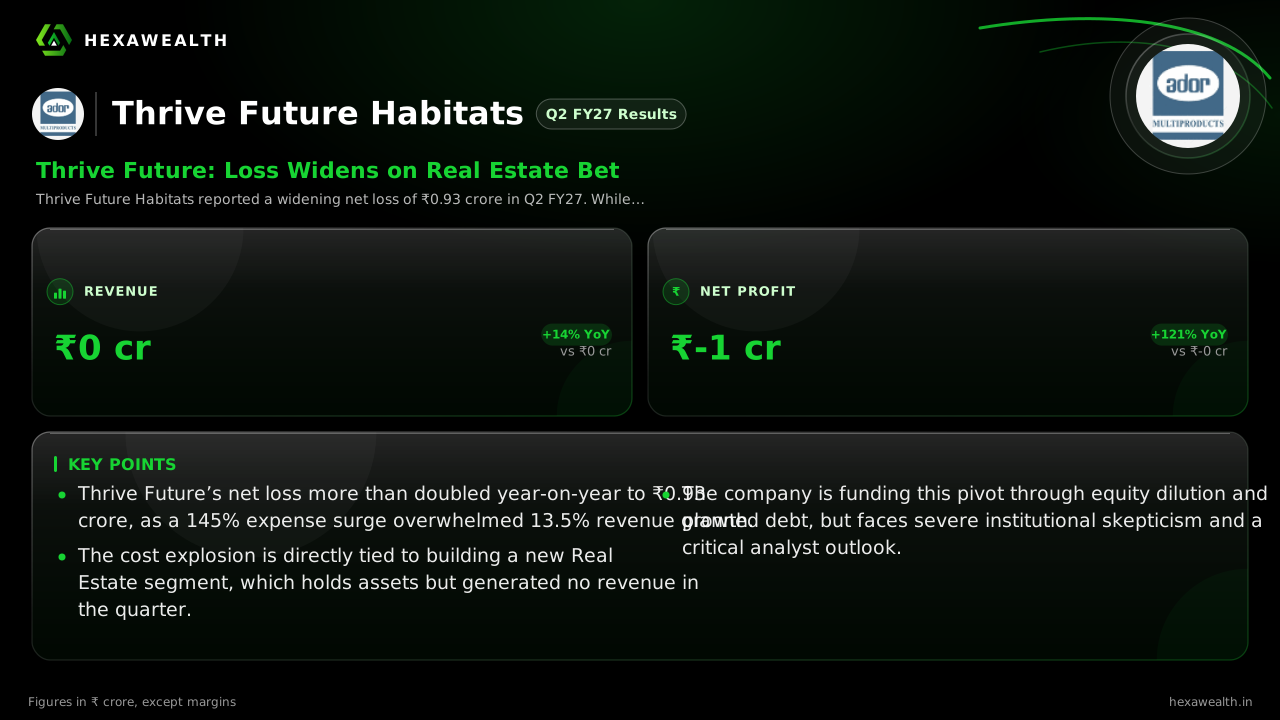
The company's quarterly net loss more than doubled year-on-year to ₹0.93 crore, as heavy investment in a new real estate segment overwhelmed modest revenue growth.
Thrive Future Habitats reported a widening net loss of ₹0.93 crore in Q2 FY27. While revenue grew 13.5% YoY, total expenses surged 145%, driven by a massive build-up for its new, non-revenue-generating real estate segment.
Thrive Future Habitats is betting its future on real estate, but the transition is proving costly. The company’s September quarter shows a business in the painful early stages of a pivot, where heavy upfront investment is drowning out its modest core operations.
The numbers tell a story of structural change. Revenue from operations grew 13.5% year-on-year to ₹0.42 crore. Yet the net loss widened sharply to ₹0.93 crore from ₹0.42 crore a year ago. This disconnect comes from a 145% explosion in total expenses, which now completely swamp the top line.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 0.37
- Revenue (₹ Cr), Q3 FY26: 0.08
- Revenue (₹ Cr), Q4 FY26: 0.47
- Revenue (₹ Cr), Q1 FY27: 0.35
- Revenue (₹ Cr), Q2 FY27: 0.42
- Net Profit (₹ Cr), Q2 FY26: -0.42
- Net Profit (₹ Cr), Q3 FY26: 0.34
- Net Profit (₹ Cr), Q4 FY26: -0.68
- Net Profit (₹ Cr), Q1 FY27: -0.92
- Net Profit (₹ Cr), Q2 FY27: -0.93
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 0.37
- Revenue (₹ Cr), Q3 FY26: 0.08
- Revenue (₹ Cr), Q4 FY26: 0.47
- Revenue (₹ Cr), Q1 FY27: 0.35
- Revenue (₹ Cr), Q2 FY27: 0.42
Net Profit (₹ Cr)
- Net Profit (₹ Cr), Q2 FY26: -0.42
- Net Profit (₹ Cr), Q3 FY26: 0.34
- Net Profit (₹ Cr), Q4 FY26: -0.68
- Net Profit (₹ Cr), Q1 FY27: -0.92
- Net Profit (₹ Cr), Q2 FY27: -0.93
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 0.42YoY +14% | 0.35 | 0.37 |
| Net Profit (₹ Cr) | -0.93YoY -121% | -0.92 | -0.42 |
The Cost of a New Beginning
The expense surge has two clear drivers, both linked to the new real estate foray. According to a scanx.trade report, employee costs jumped seven-fold year-on-year to ₹0.79 crore, now exceeding quarterly revenue. Depreciation surged over 940% to ₹0.48 crore, indicating significant asset acquisition for the new segment.
This new Real Estate division, as per the same report, holds assets worth ₹8.47 crore but generated zero revenue, booking a small EBITDA loss. The company’s core Personal Care segment produced all the ₹0.42 crore revenue. The cost base has been rebuilt for a business that does not yet exist.
Funding the Burn and Market Skepticism
To finance this build-up, the company has turned to equity markets. A recent warrant conversion raised ₹29.25 crore, as noted by scanx.trade, boosting the paid-up capital. Shareholders have also approved a ₹200 crore borrowing limit increase to fund projects.
Live Chart
· THRIVE
(BSE)
ISIN: INE628D01014
The market’s read is one of deep skepticism. MarketsMojo assigns the stock a “STRONG SELL” rating with a score of 17/100, citing a “fundamental breakdown in business viability.” Notably, institutional investors hold a 0% stake, a clear vote of no confidence from professional capital.
Key Points
- Thrive Future’s net loss more than doubled year-on-year to ₹0.93 crore, as a 145% expense surge overwhelmed 13.5% revenue growth.
- The cost explosion is directly tied to building a new Real Estate segment, which holds assets but generated no revenue in the quarter.
- The company is funding this pivot through equity dilution and planned debt, but faces severe institutional skepticism and a critical analyst outlook.
Hexa Perspective
The quarter underscores a company caught between a fading legacy business and an unproven new venture. The financials are now entirely shaped by pre-revenue investment, making profitability a distant prospect contingent on real estate execution.
Investors are effectively underwriting a start-up within a listed shell. The risk is high, as the cash burn continues with no near-term revenue offset from the new segment. The valuation, therefore, hinges not on current earnings but on belief in a management turnaround that has yet to show any operational results.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.