Shree Vasu Logistics (SVLL) Q2 FY27 Profit Soars 389% on Strong 3PL Demand
The logistics firm's Q2 FY27 net profit surged to ₹5.08 crore, driven by a 43% revenue jump and expanding margins, though high debt and valuation remain concerns.
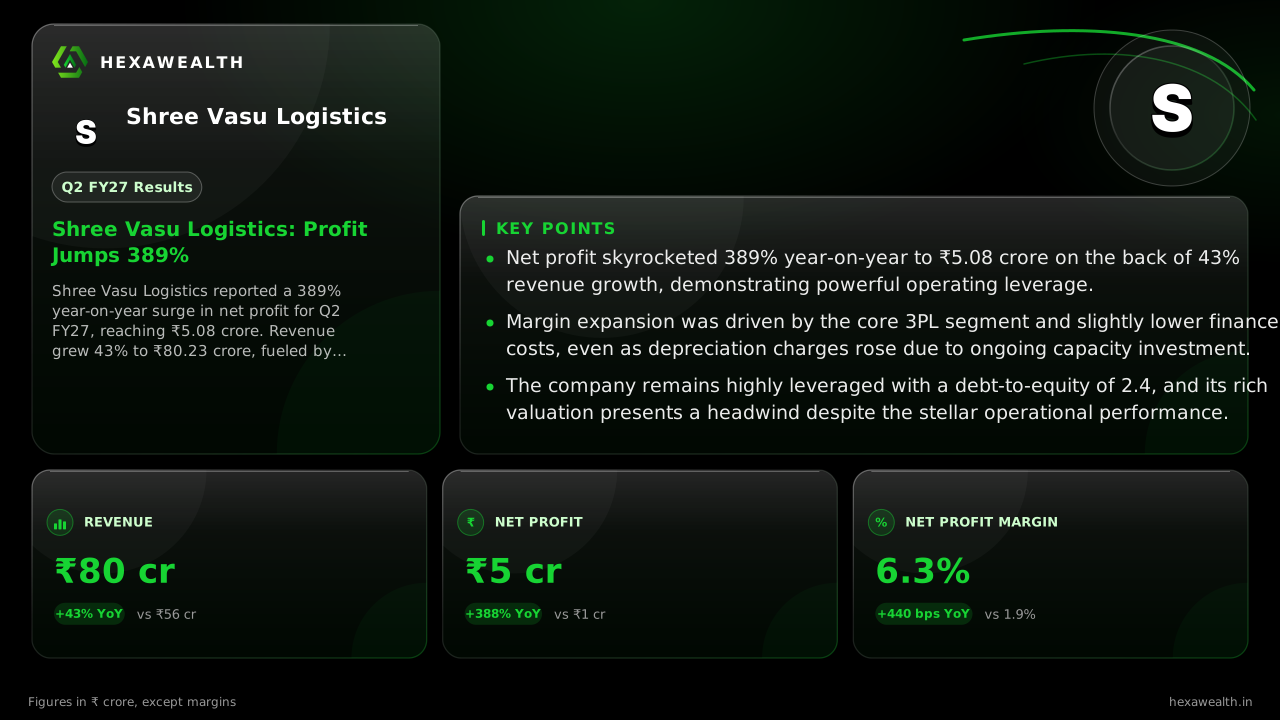
Shree Vasu Logistics reported a 389% year-on-year surge in net profit for Q2 FY27, reaching ₹5.08 crore. Revenue grew 43% to ₹80.23 crore, fueled by robust demand in its core 3PL logistics segment.
For Shree Vasu Logistics, the story is one of scale finally meeting demand. The company’s core third-party logistics (3PL) business, which drives over 90% of revenue, is riding a wave of outsourcing and industrial expansion across India.
This translated into a record September quarter. Revenue climbed to ₹80.23 crore, up 43% from a year ago and 24% from the June quarter. Profit growth was even more dramatic, surging 389% year-on-year to ₹5.08 crore.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 55.97
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 55.82
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 62.45
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 64.75
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 80.23
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 1.04
- Profit (₹ Cr), Q3 FY26 (Dec 2025): -1.13
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 4.00
- Profit (₹ Cr), Q1 FY27 (Jun 2026): 3.25
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 5.08
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 55.97
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 55.82
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 62.45
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 64.75
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 80.23
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 1.04
- Profit (₹ Cr), Q3 FY26 (Dec 2025): -1.13
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 4.00
- Profit (₹ Cr), Q1 FY27 (Jun 2026): 3.25
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 5.08
Net Profit Margin
- Net Profit Margin, Q2 FY26 (Sep 2025): 1.9%
- Net Profit Margin, Q3 FY26 (Dec 2025): -2.0%
- Net Profit Margin, Q4 FY26 (Mar 2026): 6.4%
- Net Profit Margin, Q1 FY27 (Jun 2026): 5.0%
- Net Profit Margin, Q2 FY27 (Sep 2026): 6.3%
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 80.23 | 64.75 |
| Profit (₹ Cr) | 5.08 | 3.25 |
| Net Profit Margin | 6.3% | 5.0% |
Why Profits Outpaced Revenue
The profit surge wasn't just about higher sales. Operating leverage kicked in as revenue growth of 43% far outpaced the 36.5% rise in total expenses. A key factor was a slight decline in interest costs, which fell 1.3% year-on-year to ₹3.95 crore, according to the company's filings.
This helped the net profit margin expand by 440 basis points to 6.3%. The company's 3PL segment results jumped to ₹8.58 crore from ₹2.91 crore a year ago, as reported by ScanX Trade, highlighting the core business's improving profitability.
The Capacity Build-Out and Its Cost
Growth is coming at a capital cost. Depreciation rose 32% year-on-year to ₹11.21 crore, reflecting ongoing investment in assets. The company's investor presentation, noted by Arthneeti, shows capital work-in-progress of ₹7.60 crore and new asset purchases of ₹1.72 crore in the first half.
Live Chart
· SVLL
(BSE)
ISIN: INE00CE01017
This spending supports a long-term roadmap to reach 50 million square feet of warehousing capacity by FY31. For now, it means a significant portion of operating profit is consumed by depreciation and interest, keeping net margins in single digits.
The Balance Sheet Tension
Strong earnings are set against a leveraged financial structure. The debt-to-equity ratio stands at 2.4, and the current ratio is a tight 0.99, indicating minimal cushion for short-term obligations. While operating cash flow was strong at over ₹30 crore in FY26, the company is still adding debt; net borrowings increased by over ₹9 crore in the first half, per its cash flow statement.
Market reaction has been muted, with the stock largely flat around ₹800 after the results. MarketsMojo points to valuation concerns, with the stock trading at a P/E of 95.5, more than double the industry average of 44.9. The firm maintains a 'Hold with Caution' view, citing expensive multiples.
Key Points
- Net profit skyrocketed 389% year-on-year to ₹5.08 crore on the back of 43% revenue growth, demonstrating powerful operating leverage.
- Margin expansion was driven by the core 3PL segment and slightly lower finance costs, even as depreciation charges rose due to ongoing capacity investment.
- The company remains highly leveraged with a debt-to-equity of 2.4, and its rich valuation presents a headwind despite the stellar operational performance.
Hexa Perspective
The quarter confirms Shree Vasu Logistics is successfully capturing robust sector demand, with profitability reaching a multi-quarter high. The path ahead hinges on whether this margin expansion is sustainable as depreciation from new capex accrues and if interest costs can remain contained.
Investors are weighing the impressive growth trajectory against the company's leveraged balance sheet and a valuation that prices in significant future success. The next few quarters will test if operating profits can grow fast enough to improve coverage ratios and justify the premium.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.