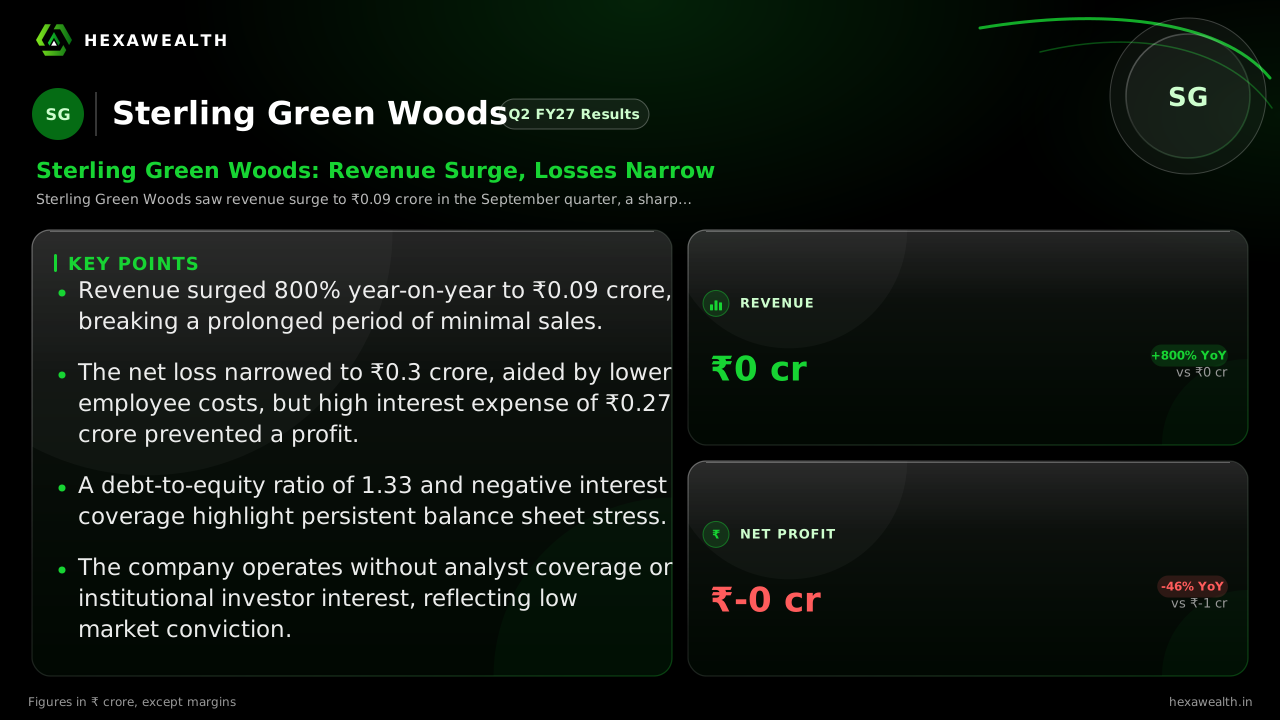
Sterling Green Woods (STRGRENWO) Q2 FY27 Revenue Jumps 800% as Losses Narrow
Sterling Green Woods reported an 800% revenue jump in Q2 FY27, but a high interest burden kept the company in the red as losses narrowed by 45% year-on-year.
Sterling Green Woods saw revenue surge to ₹0.09 crore in the September quarter, a sharp jump from a near-zero base. However, a persistent interest expense and high leverage kept the company in a loss-making position, though the net loss narrowed from the previous year.
For a real estate developer, a quarter of revenue is a sign of life. Sterling Green Woods showed a pulse in the September quarter, with sales finally arriving after a long drought.
The company reported revenue of ₹0.09 crore for Q2 FY27, a dramatic 800% increase from the ₹0.01 crore it recorded a year ago. Sequentially, revenue jumped 350% from ₹0.02 crore in the June quarter. The net loss for the quarter stood at ₹0.3 crore, an improvement from the ₹0.55 crore loss in Q2 FY26 and a slight narrowing from the ₹0.33 crore loss in Q1 FY27.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 0.01
- Revenue (₹ Cr), Q3 FY26: 0.01
- Revenue (₹ Cr), Q4 FY26: 0.01
- Revenue (₹ Cr), Q1 FY27: 0.02
- Revenue (₹ Cr), Q2 FY27: 0.09
- Profit (₹ Cr), Q2 FY26: -0.55
- Profit (₹ Cr), Q3 FY26: -0.32
- Profit (₹ Cr), Q4 FY26: 0.09
- Profit (₹ Cr), Q1 FY27: -0.33
- Profit (₹ Cr), Q2 FY27: -0.30
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 0.01
- Revenue (₹ Cr), Q3 FY26: 0.01
- Revenue (₹ Cr), Q4 FY26: 0.01
- Revenue (₹ Cr), Q1 FY27: 0.02
- Revenue (₹ Cr), Q2 FY27: 0.09
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26: -0.55
- Profit (₹ Cr), Q3 FY26: -0.32
- Profit (₹ Cr), Q4 FY26: 0.09
- Profit (₹ Cr), Q1 FY27: -0.33
- Profit (₹ Cr), Q2 FY27: -0.30
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Period Ended | Sep 2026 | Jun 2026 | Sep 2025 |
| Revenue (₹ Cr) | 0.09YoY +800% | 0.02 | 0.01 |
| Profit (₹ Cr) | -0.30YoY +45% | -0.33 | -0.55 |
Why the top line didn't reach the bottom
The revenue surge did not translate to profitability because of a fixed, heavy cost structure. Finance costs of ₹0.27 crore were nearly unchanged from the previous quarter and consumed the entire operating income. According to a scanx.trade report, the company's interest service coverage ratio remains deeply negative, reflecting that operating earnings are insufficient to cover interest obligations.
A balance sheet under strain
High leverage continues to be the central challenge. The debt-to-equity ratio stood at 1.33, indicating significant financial strain. The same scanx.trade analysis notes a severe liquidity crunch, with cash of just ₹0.87 lakh against current borrowings of over ₹13.5 crore. This structure leaves little room for operational investment or growth without external intervention.
The market's muted read
With no active analyst coverage or institutional holdings, the market's reaction to these results is inherently limited. StockFin.ai notes the absence of FII or DII participation and a fragmented retail ownership base, suggesting limited market confidence in a near-term turnaround. The company's shareholding pattern has remained static for several quarters.
Live Chart
· STRGRENWO
(BSE)
ISIN: INE398F01019
Key Points
- Revenue surged 800% year-on-year to ₹0.09 crore, breaking a prolonged period of minimal sales.
- The net loss narrowed to ₹0.3 crore, aided by lower employee costs, but high interest expense of ₹0.27 crore prevented a profit.
- A debt-to-equity ratio of 1.33 and negative interest coverage highlight persistent balance sheet stress.
- The company operates without analyst coverage or institutional investor interest, reflecting low market conviction.
Hexa Perspective
This quarter is a story of two halves. The revenue jump shows the business can still generate some sales, likely from its existing resort and real estate portfolio. Yet, the financial structure is the defining constraint. The interest burden is a fixed cost that the current scale of operations cannot support.
The path forward hinges on a material increase in revenue to cover these fixed costs, or a restructuring of the debt load itself. Until one of those levers is pulled, the company remains in a precarious position, where even significant percentage growth on a tiny base does little to change the fundamental equation.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.