All posts

Follow Us

LinkedInInstagramX
Quarterly ResultsArchiveLast updated 4 November 20263 min read

SM Auto Stamping (SMAUTO) Q2 FY27 Profit Plunges 60% Despite Strong Revenue Growth

SM Auto Stamping's Q2 FY27 revenue grew 27% year-on-year, but profit fell sharply from the previous quarter as costs rose faster than sales.

By Abhinav Swaroop, CFA, Chief Business Officer: Hexawealth · Created 4 November 2026

SM Auto Stamping reported a 26.8% YoY revenue rise to ₹43.28 crore in Q2 FY27. However, net profit fell 59.8% sequentially to ₹1.03 crore, squeezed by a sharp increase in material costs and depreciation.

For auto component makers, a strong top line is only half the story when input costs run ahead. SM Auto Stamping's September quarter shows that tension clearly, with revenue surging but profitability taking a sharp sequential hit.

The company's quarterly revenue reached ₹43.28 crore, a 26.8% jump from a year ago and a 16.4% rise from the June quarter. Yet net profit fell to ₹1.03 crore, down nearly 60% from the ₹2.56 crore posted in Q4 FY26. The net profit margin compressed by 450 basis points to just 2.4%.

Revenue & profit

Revenue (₹ Cr)

Profit (₹ Cr)

Net Profit Margin (%)

MetricCurrentQ2 FY27 (Sep 2026)PreviousQ4 FY26 (Mar 2026)
Revenue (₹ Cr)
43.28
37.19
Profit (₹ Cr)
1.03
2.56
Net Profit Margin (%)
2.4
6.9

Why the profit fell despite higher sales

The profit squeeze came from costs rising faster than revenue. According to a report from scanx.trade, the cost of materials consumed surged 38.2% year-on-year, outpacing the 26.8% revenue growth. Total expenses climbed 21.1% from the previous quarter, with depreciation rising 19% and interest costs falling 11%.

This suggests the company is running its plants harder to meet demand, but raw material inflation is eroding the gains. The sequential margin collapse from 6.9% to 2.4% shows how quickly that pressure can hit.

The outlook for the rest of the year

Management has not provided explicit forward guidance, notes an analysis from StockFin.ai. The broader sector outlook offers a mixed read. A report by Motilal Oswal Financial Services, cited by Awaz The Voice, expects auto sector margins to recover gradually from Q3 FY27 as price hikes offset higher costs.

However, risks like El Niño and geopolitical tensions remain. For SM Auto, the path to better profitability hinges on whether it can pass on cost increases or see a moderation in input prices.

Key Points

  • Revenue grew robustly by 26.8% year-on-year and 16.4% quarter-on-quarter, indicating strong demand for its components.
  • Net profit fell 59.8% sequentially as material costs rose 38.2% year-on-year, squeezing the net margin to 2.4%.
  • The company is deleveraging, with reduced borrowings and positive operating cash flow for the half-year, as per a scanx.trade report.
  • Management has not issued specific guidance, leaving the near-term margin trajectory dependent on cost trends and pricing power.

Hexa Perspective

The quarter underscores the volatile nature of profitability in the auto ancillary space. While the top-line momentum is undeniable and the balance sheet is strengthening, the margin performance is a stark reminder of the sector's sensitivity to input costs.

Investors are left weighing solid volume growth against thin and fluctuating margins. The stock's valuation, at a significant discount to the industry PE, may already reflect these cyclical pressures. The next few quarters will test whether the revenue growth can translate into more stable earnings.

Share or follow HexaWealth

Also read

Want this applied to your portfolio?

Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
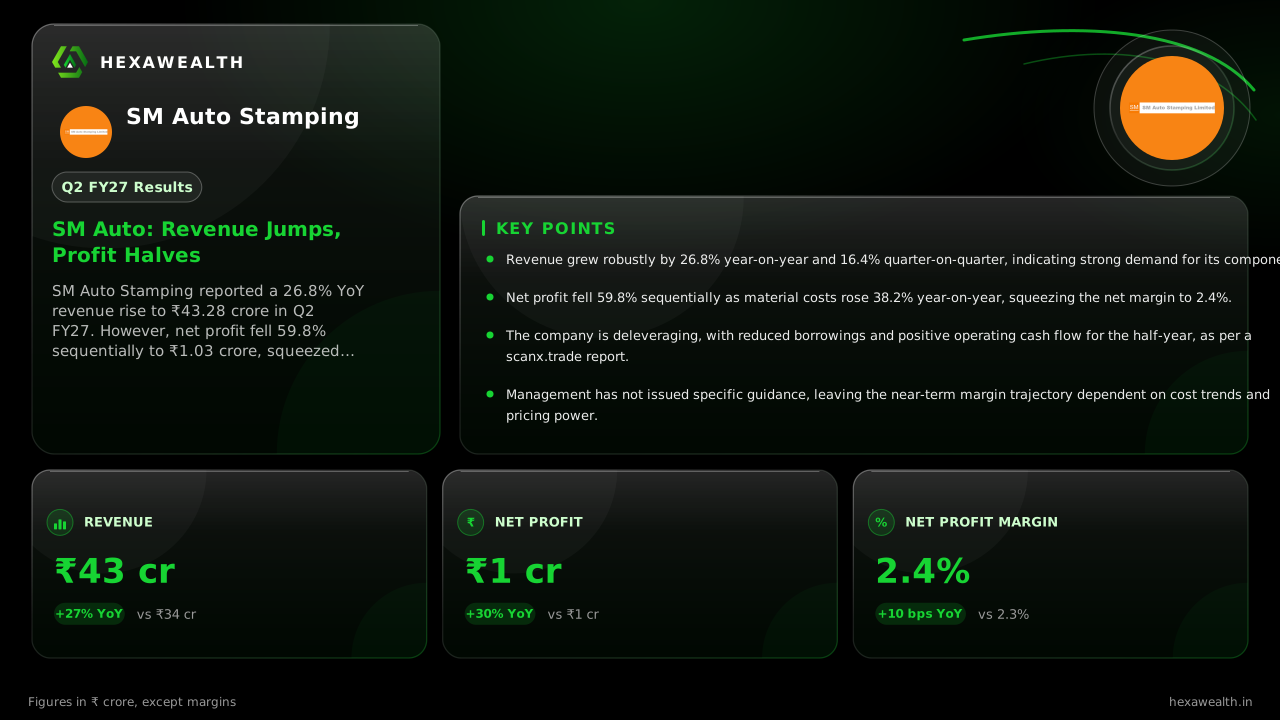
SM Auto Stamping (SMAUTO) Q2 FY27 results, revenue and profits.

Frequently asked questions

What were SM Auto Stamping's Q2 FY27 results?
For Q2 FY27 (September 2026), SM Auto Stamping reported revenue of ₹43.28 crore, up 26.8% year-on-year. Net profit was ₹1.03 crore, which was a 30.4% increase from the year-ago quarter but a 59.8% decline from the previous March quarter.
Why did SM Auto Stamping's profit fall sharply in Q2 FY27 despite higher revenue?
SM Auto's profit fell 60% sequentially because costs rose faster than sales. A scanx.trade report notes the cost of materials consumed jumped 38.2% year-on-year, outpacing revenue growth. Higher depreciation and total expenses also squeezed the net profit margin down to 2.4%.
What was SM Auto Stamping's net profit margin in Q2 FY27?
SM Auto Stamping's net profit margin was 2.4% in Q2 FY27. This marks a sharp 450 basis point drop from the 6.9% margin in the previous March quarter, reflecting significant cost pressure during the period.
What drove SM Auto Stamping's 27% YoY revenue growth in Q2 FY27?
SM Auto's revenue growth was driven by higher sales volumes, according to a scanx.trade report. The company benefited from strong demand in the auto ancillary sector, leading to a 26.8% year-on-year increase in revenue from operations to ₹43.28 crore.
Did SM Auto Stamping's Q2 FY27 results beat analyst estimates?
The research does not provide specific analyst estimates for SM Auto Stamping's Q2 FY27 results. The reported figures show strong revenue growth but a significant sequential decline in profit, which was the key story of the quarter.
What guidance did SM Auto Stamping management provide for FY27?
Management has not provided explicit forward guidance for FY27, according to an analysis by StockFin.ai. The board's focus appears to be on governance compliance and operational continuity rather than outlining a specific growth or margin roadmap.
How did SM Auto Stamping's stock price react to the Q2 results?
A price feed from Investing.com showed SM Auto Stamping's stock at ₹21.80, down 20% at one point around the results season. This suggests a negative market reaction, likely reflecting concern over the sharp sequential profit decline.
What is the state of SM Auto Stamping's order book?
The available research snippets do not provide specific details on SM Auto Stamping's order book or backlog as of Q2 FY27. The strong revenue growth indicates healthy demand, but no quantitative backlog figure is mentioned.
Is SM Auto Stamping undertaking any major capacity expansion?
The research does not mention any major new capacity expansion or capex projects affecting Q2 FY27. The increase in depreciation (up 19% QoQ) likely relates to existing asset utilization rather than a significant new project rollout.
Have any brokerages changed their rating on SM Auto Stamping after Q2 results?
The research does not cite any specific brokerage rating or target price changes for SM Auto Stamping following the Q2 FY27 results. The focus in available reports is on the reported financial figures.
SM Auto Stamping Q2 profit drop
SM Auto Stamping's Q2 FY27 net profit dropped 59.8% quarter-on-quarter to ₹1.03 crore. This sharp decline occurred even as revenue rose 16.4%, primarily due to material costs rising faster than sales.
SM Auto Stamping Q2 FY27 results November 2026
SM Auto Stamping announced its Q2 FY27 results on November 3, 2026. The company reported revenue of ₹43.28 crore and a net profit of ₹1.03 crore for the quarter ended September 2026.