Narmada Gelatines (SHAWGELTIN) Q2 FY27 Profit Jumps 31% Yearly but Margins Dip Sequentially
The gelatin maker posted robust annual growth, but a sequential decline in net profit margin signals rising cost pressures.
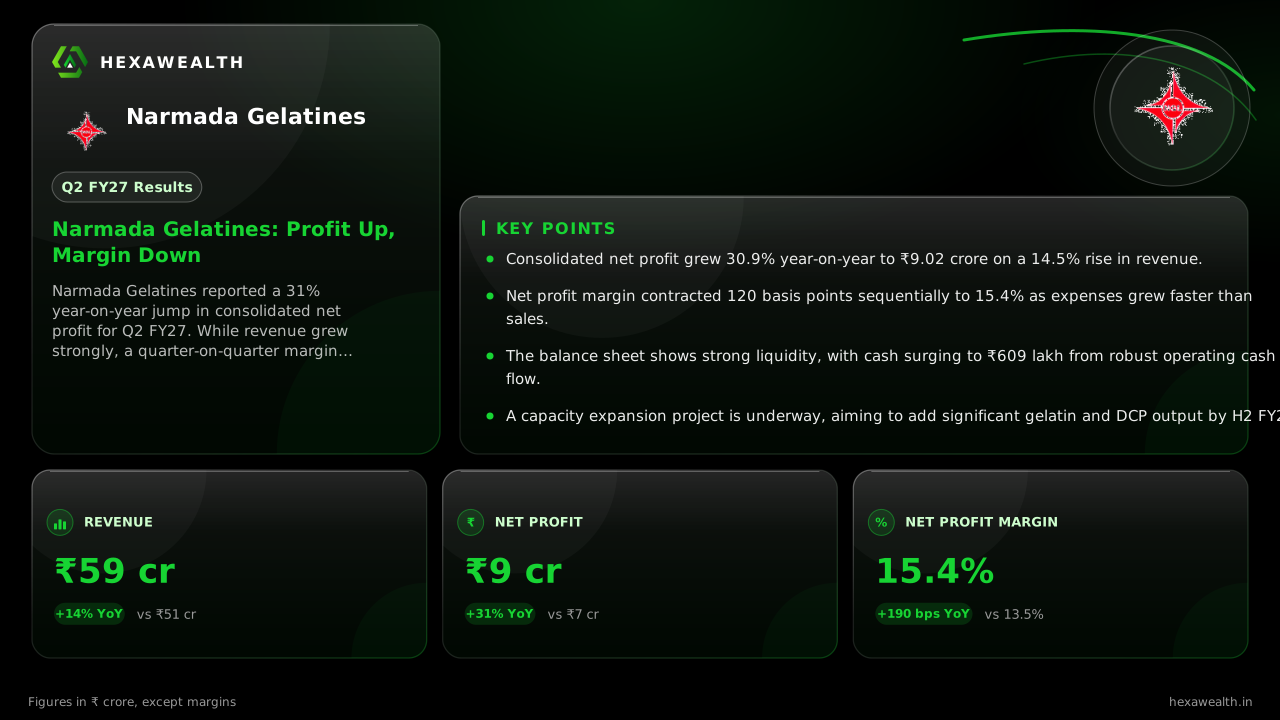
Narmada Gelatines reported a 31% year-on-year jump in consolidated net profit for Q2 FY27. While revenue grew strongly, a quarter-on-quarter margin contraction highlights emerging cost pressures.
For Narmada Gelatines, the September quarter delivered a tale of two trends. The gelatin and ossein manufacturer posted strong annual growth, yet the sequential numbers revealed a margin squeeze that investors will watch closely.
The consolidated scorecard shows revenue at ₹58.61 crore, up 14.5% from a year ago. Net profit grew even faster, rising 30.9% to ₹9.02 crore. Sequentially, however, profit dipped 3.3% even as revenue grew 4%, pulling the net profit margin down 120 basis points to 15.4%.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 51.21
- Revenue (₹ Cr), Q3 FY26: 56.73
- Revenue (₹ Cr), Q4 FY26: 61.70
- Revenue (₹ Cr), Q1 FY27: 56.37
- Revenue (₹ Cr), Q2 FY27: 58.61
- Net Profit (₹ Cr), Q2 FY26: 6.89
- Net Profit (₹ Cr), Q3 FY26: 8.40
- Net Profit (₹ Cr), Q4 FY26: 10.21
- Net Profit (₹ Cr), Q1 FY27: 9.33
- Net Profit (₹ Cr), Q2 FY27: 9.02
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 51.21
- Revenue (₹ Cr), Q3 FY26: 56.73
- Revenue (₹ Cr), Q4 FY26: 61.70
- Revenue (₹ Cr), Q1 FY27: 56.37
- Revenue (₹ Cr), Q2 FY27: 58.61
Net Profit (₹ Cr)
- Net Profit (₹ Cr), Q2 FY26: 6.89
- Net Profit (₹ Cr), Q3 FY26: 8.40
- Net Profit (₹ Cr), Q4 FY26: 10.21
- Net Profit (₹ Cr), Q1 FY27: 9.33
- Net Profit (₹ Cr), Q2 FY27: 9.02
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY26: 13.5
- Net Profit Margin (%), Q3 FY26: 14.8
- Net Profit Margin (%), Q4 FY26: 16.5
- Net Profit Margin (%), Q1 FY27: 16.6
- Net Profit Margin (%), Q2 FY27: 15.4
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 58.61YoY +14% | 56.37 | 51.21 |
| Net Profit (₹ Cr) | 9.02YoY +31% | 9.33 | 6.89 |
| Net Profit Margin (%) | 15.4YoY +14% | 16.6 | 13.5 |
Why margins softened sequentially
The year-on-year profit surge was powered by operating leverage, as per a ScanX report. Revenue grew faster than total expenses, which rose only 12.2%. Employee costs, a key semi-fixed expense, grew at a slower 9.5% pace.
This efficiency gain was partly offset in the sequential comparison. Total expenses rose 5.2% quarter-on-quarter, outpacing the 4% revenue growth. This cost creep, alongside a sharp rise in depreciation, explains the margin contraction from the previous quarter's 16.6%.
A cash-rich balance sheet
Despite the margin pressure, the company's financial health strengthened. According to the same ScanX report, cash and equivalents surged from ₹11 lakh in March 2026 to ₹609 lakh by September 2026. This was driven by robust operating cash flow of ₹2,192 lakh for the half-year, even after significant capital expenditure.
Live Chart
· SHAWGELTIN
(BSE)
ISIN: INE869A01010
The capacity expansion ahead
The company is investing for future growth. A social media analysis cited by ScanX indicates a ₹33 crore capex plan to add 600 MT of gelatin and 1,500 MT of DCP capacity. Commercial production from this expansion is expected around the second half of FY27.
Key Points
- Consolidated net profit grew 30.9% year-on-year to ₹9.02 crore on a 14.5% rise in revenue.
- Net profit margin contracted 120 basis points sequentially to 15.4% as expenses grew faster than sales.
- The balance sheet shows strong liquidity, with cash surging to ₹609 lakh from robust operating cash flow.
- A capacity expansion project is underway, aiming to add significant gelatin and DCP output by H2 FY27.
Hexa Perspective
The quarter underscores a business growing profitably over the year but facing near-term margin headwinds. The strong cash generation provides a cushion and funds expansion without straining the near-zero debt balance sheet. The trajectory now hinges on whether the new capacity can drive the next leg of revenue growth and restore operating leverage, offsetting the recent cost pressures. The stock's 27% one-year return suggests the market has priced in the robust annual performance; the sequential margin trend will be the new focus.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.