Satani Bearings (SATANIBRG) Revenue Jumps 354% but Profit Remains Thin in Q2 FY27
The bearings maker saw a massive sequential revenue recovery from a near-zero base, yet profitability remains fragile as it executes a strategic turnaround.
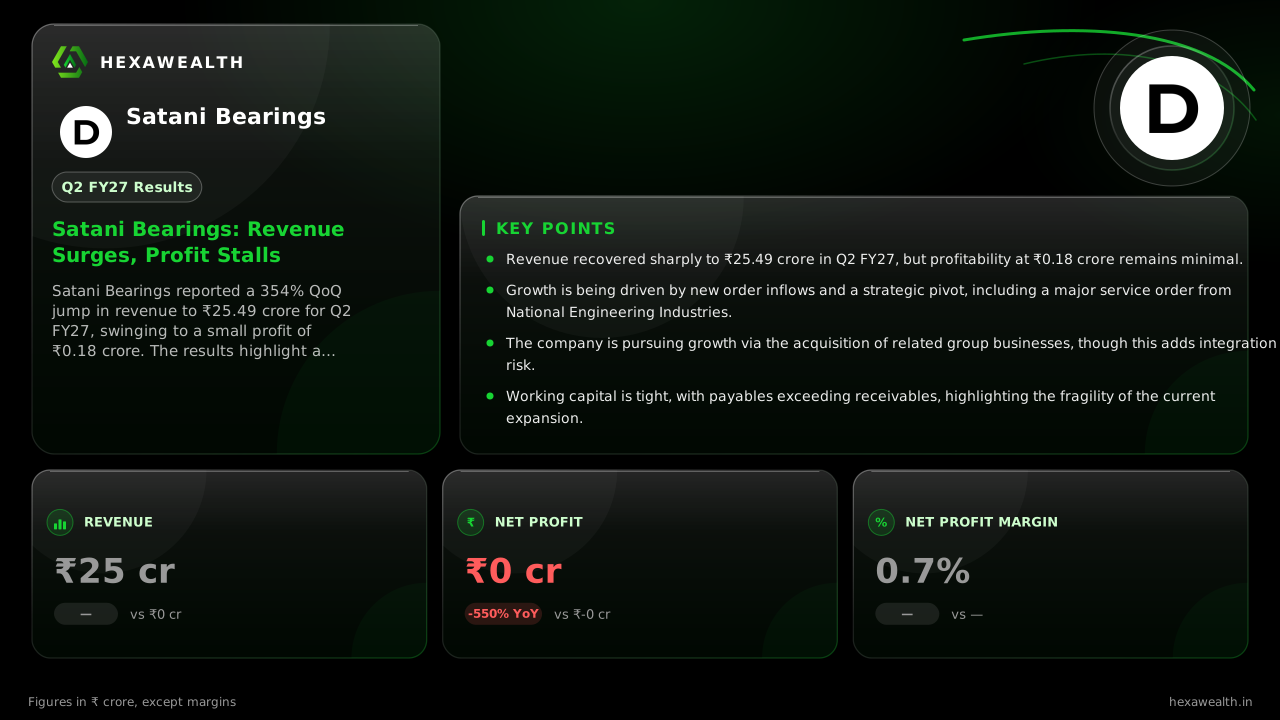
Satani Bearings reported a 354% QoQ jump in revenue to ₹25.49 crore for Q2 FY27, swinging to a small profit of ₹0.18 crore. The results highlight a volatile recovery phase as the company integrates new businesses and revives operations.
For Satani Bearings, the September quarter was about proving the revival is real. After a period of near-dormancy, the company's revenue surged back, but the path to consistent profitability remains narrow and crowded with costs.
The numbers show a business in transition. Revenue leaped to ₹25.49 crore from just ₹5.62 crore in the prior quarter. This brought a net profit of ₹0.18 crore, a swing from the ₹0.21 crore loss in Q1. Yet the half-year picture is still a net loss of ₹0.28 crore, as reported by ScanX.trade.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin %
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Period | Sep 2026 | Jun 2026 | Sep 2025 |
| Revenue (₹ Cr) | 25.49 | 5.62 | 0.00 |
| Profit (₹ Cr) | 0.18YoY +550% | -0.21 | -0.04 |
| Net Profit Margin % | 0.7 | -3.8 | N/A |
The Volatile Road to Recovery
The extreme revenue volatility—from zero a year ago to over ₹25 crore—stems from a fundamental restructuring. The company, formerly Deccan Bearings, is now actively trading after a period of no operations. The recent quarter likely reflects the initial contribution from new business models and order inflows.
A key driver was a major service order. According to Zerodha, Satani Bearings received a Letter of Intent from National Engineering Industries Ltd valued at ₹376.57 crore including GST. While not all recognized this quarter, it signals the scale of opportunity the company is now chasing.
Why Profit Lags Far Behind Sales
Despite the top-line explosion, profit remains a sliver. Expenses grew 334% sequentially to ₹25.28 crore, almost keeping pace with revenue. The net profit margin, though improved, is a fragile 0.7%.
The balance sheet reveals a tight working capital position. ScanX.trade notes trade payables of ₹23.25 crore exceeded receivables of ₹22.99 crore at the half-year mark. This supplier-funded growth model leaves little room for error if collections slow.
A Strategy Built on Acquisitions
Management is betting on consolidation to build scale. The board has approved acquiring the businesses of Satani Industries and Satani Forge & Turn on a slump-sale basis, as per filings covered by Zerodha. This move aims to integrate group operations but carries execution and integration risks.
Analysts remain cautious. A StockFin.ai analysis points out the company's small scale, volatile quarterly financials, and high promoter concentration as key concerns. The absence of institutional investor interest further underscores the speculative nature of the current turnaround story.
Key Points
- Revenue recovered sharply to ₹25.49 crore in Q2 FY27, but profitability at ₹0.18 crore remains minimal.
- Growth is being driven by new order inflows and a strategic pivot, including a major service order from National Engineering Industries.
- The company is pursuing growth via the acquisition of related group businesses, though this adds integration risk.
- Working capital is tight, with payables exceeding receivables, highlighting the fragility of the current expansion.
Hexa Perspective
Satani Bearings is in the earliest, most volatile phase of a turnaround. The revenue jump confirms the business model is now active, but the near-zero margin shows it lacks pricing power or operating leverage. Success hinges entirely on executing the acquisition-led integration smoothly and converting the large order book into sustained, profitable sales.
The valuation, at a PE of over 5,800 times, prices in a flawless recovery that is far from assured. Investors are essentially underwriting the management's ability to transform a dormant shell into a viable operating company—a high-risk proposition where the next two quarters will be critical for evidence.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.