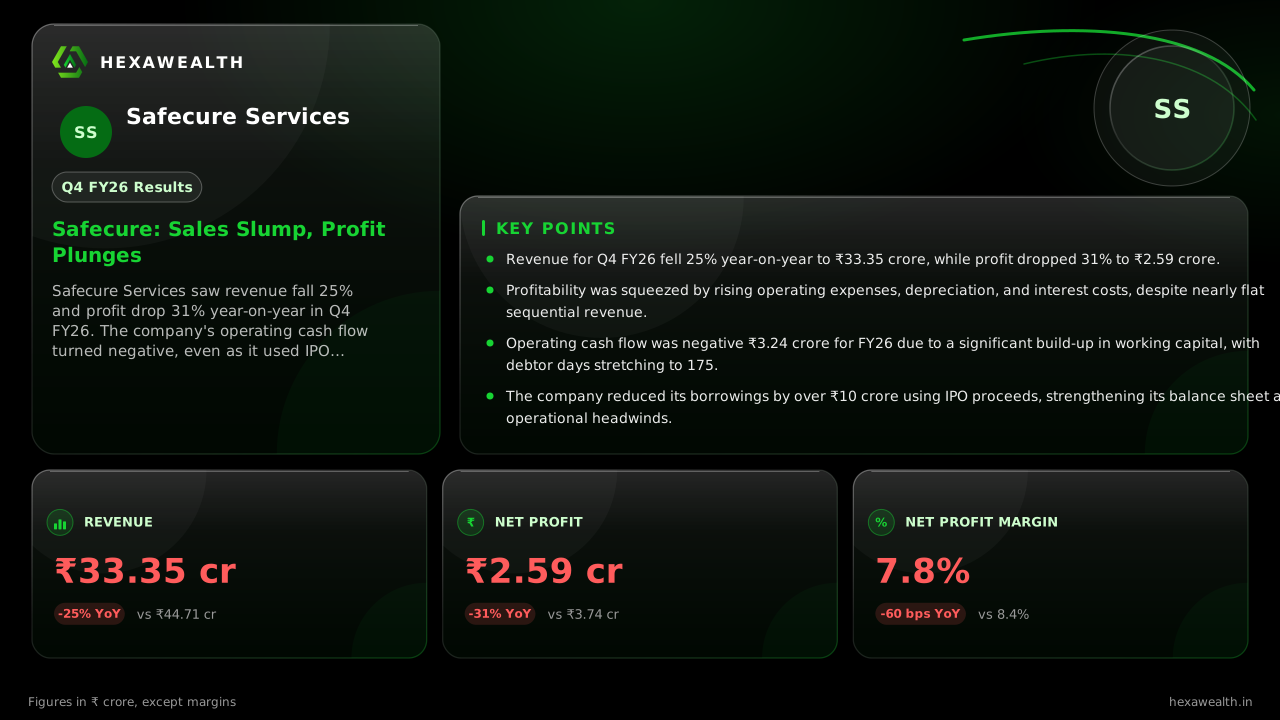
Safecure Services saw revenue fall 25% and profit drop 31% year-on-year in Q4 FY26. The company's operating cash flow turned negative, even as it used IPO proceeds to cut debt by over ₹10 crore.
For a manpower-intensive service business, revenue is a direct measure of client engagement and contract health. Safecure Services ended FY26 with a steep contraction on both fronts, as its fourth quarter revenue fell 25% from a year earlier to ₹33.35 crore. Profit after tax dropped 31% to ₹2.59 crore, capping a year of declining topline performance.
The quarterly scorecard shows a business losing momentum. Compared to the strong ₹44.71 crore revenue in Q4 FY25, the latest quarter's sales were down sharply. Profit fell even faster than revenue, pushing the net profit margin down 60 basis points year-on-year to 7.8%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Revenue (₹ Cr), Q1 FY25: 15.50
Revenue (₹ Cr), Q2 FY25: 28.39
Revenue (₹ Cr), Q4 FY25: 44.71
Revenue (₹ Cr), Q2 FY26: 33.53
Revenue (₹ Cr), Q4 FY26: 33.35
Profit (₹ Cr), Q1 FY25: 1.52
Profit (₹ Cr), Q2 FY25: 2.41
Profit (₹ Cr), Q4 FY25: 3.74
Profit (₹ Cr), Q2 FY26: 3.44
Profit (₹ Cr), Q4 FY26: 2.59
Revenue (₹ Cr)
Revenue (₹ Cr), Q1 FY25: 15.50
Revenue (₹ Cr), Q2 FY25: 28.39
Revenue (₹ Cr), Q4 FY25: 44.71
Revenue (₹ Cr), Q2 FY26: 33.53
Revenue (₹ Cr), Q4 FY26: 33.35
Profit (₹ Cr)
Profit (₹ Cr), Q1 FY25: 1.52
Profit (₹ Cr), Q2 FY25: 2.41
Profit (₹ Cr), Q4 FY25: 3.74
Profit (₹ Cr), Q2 FY26: 3.44
Profit (₹ Cr), Q4 FY26: 2.59
Net Profit Margin (%)
Net Profit Margin (%), Q1 FY25: 9.8
Net Profit Margin (%), Q2 FY25: 8.5
Net Profit Margin (%), Q4 FY25: 8.4
Net Profit Margin (%), Q2 FY26: 10.3
Net Profit Margin (%), Q4 FY26: 7.8
Metric
CurrentQ4 FY26
Same quarter LYQ4 FY25
Revenue (₹ Cr)
33.35YoY -25%
44.71
Profit (₹ Cr)
2.59YoY -31%
3.74
Net Profit Margin (%)
7.8YoY -7.1%
8.4
The costs that squeezed margins
Revenue was nearly flat sequentially, but profit fell 25% from the September quarter. This points to a margin squeeze from rising costs. Data from Newboard shows operating expenses rose 3.9% quarter-on-quarter, while depreciation jumped 24% and interest climbed 11%.
The operating profit margin for the half-year ending March 2026 was 15.9%, down from 18.4% in the prior half, according to the same source. This suggests the company faced pressure from both fixed costs and potentially higher manpower expenses, a key risk flagged by analysts.
A cash flow puzzle despite debt paydown
A striking feature of the full year was a negative operating cash flow of ₹3.24 crore, reported by DalalOS, despite a reported profit of ₹6.03 crore. This was driven by a ₹14.10 crore increase in working capital requirements, primarily tied up in receivables.
Live Chart
· SAFECURE
(BSE)
ISIN: INE0SVZ01015
Customer payment cycles stretched to 175 days in FY26, up from 159 days a year prior, as per Newboard. This cash conversion challenge comes even as the company strengthened its balance sheet, using IPO proceeds to cut borrowings by over ₹10 crore to ₹10.09 crore.
The outlook in a tightening market
The company has not provided formal guidance, but the industry context is shifting. A CRISIL report cited by Lokmattimes projects 9-10% revenue growth for the organised sector in FY27, supported by labour reforms that tighten compliance.
For Safecure, the immediate future appears challenging. Its H1 FY27 results, approved in November, showed revenue down 29.6% year-on-year, according to Alfafinder. Winning new contracts, like those recently secured from the Bajaj and Poonawalla groups, will be critical to reversing the revenue slide.
Key Points
Revenue for Q4 FY26 fell 25% year-on-year to ₹33.35 crore, while profit dropped 31% to ₹2.59 crore.
Profitability was squeezed by rising operating expenses, depreciation, and interest costs, despite nearly flat sequential revenue.
Operating cash flow was negative ₹3.24 crore for FY26 due to a significant build-up in working capital, with debtor days stretching to 175.
The company reduced its borrowings by over ₹10 crore using IPO proceeds, strengthening its balance sheet amid operational headwinds.
“
Hexa Perspective
The quarter underscores a fundamental tension between balance sheet repair and operating performance. While using fresh capital to slash debt is prudent, the core business is grappling with a sharp revenue decline and poor cash conversion.
The stretched receivables cycle indicates potential pressure from clients or a competitive scramble for contracts, which may continue to weigh on cash flows. For the stock's single-digit P/E to hold any appeal, investors need to see the new contract wins translating into sustained revenue growth and, crucially, faster cash collection.
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
Frequently asked questions
What were Safecure Services' Q4 FY26 results?
Safecure Services reported Q4 FY26 revenue of ₹33.35 crore, a 25% drop from the year-ago quarter. Net profit was ₹2.59 crore, down 31% year-on-year. The company's net profit margin for the quarter contracted to 7.8%.
Why did Safecure Services' Q4 FY26 revenue fall 25% year-on-year?
Safecure Services' Q4 FY26 revenue fell 25% year-on-year primarily due to a decline in its core business operations. The company's revenue for the half-year ending March 2026 was ₹33.35 crore, significantly lower than the ₹44.71 crore reported in the same period a year earlier, indicating a broad-based slowdown.
What caused Safecure Services' profit to drop 25% quarter-on-quarter in Q4 FY26?
Safecure Services' profit fell 25% quarter-on-quarter in Q4 FY26 due to a margin squeeze. While revenue was nearly flat, operating expenses rose 3.9%, depreciation increased 24%, and interest costs climbed 11%, compressing profitability significantly from the September 2025 quarter.
Why did Safecure Services' net profit margin contract in Q4 FY26?
Safecure Services' net profit margin contracted 250 basis points sequentially in Q4 FY26 to 7.8%. This was driven by a rise in total expenses, including higher depreciation and interest costs, which outpaced the company's nearly flat revenue for the quarter.
Why did Safecure Services report negative operating cash flow for FY26?
Safecure Services reported negative operating cash flow of ₹3.24 crore for FY26 due to a ₹14.10 crore increase in working capital. This was primarily caused by longer customer payment cycles, with debtor days stretching to 175, tying up cash despite the company reporting a profit.
How did Safecure Services reduce its borrowings in FY26?
Safecure Services reduced its borrowings by over ₹10 crore in FY26, bringing them down to ₹10.09 crore. This was achieved by utilizing a portion of the proceeds from its initial public offering (IPO) specifically allocated for debt repayment.
What guidance did Safecure Services management provide for FY27?
Safecure Services management did not provide specific formal guidance for FY27 in its Q4 results. However, the broader industry outlook from a CRISIL report projects 9-10% revenue growth for the organised security and facility management sector in the current fiscal year.
What is the current order book status for Safecure Services?
Safecure Services has recently secured service contract orders from prominent financial services companies, including the Bajaj Group and the Poonawalla Group. These new wins are crucial for the company as it looks to reverse the revenue decline seen in recent quarters.
Did Safecure Services announce any dividends with its Q4 FY26 results?
No, Safecure Services did not announce any dividends alongside its Q4 FY26 results. The company's dividend payout for FY26 was nil, as confirmed by MarketPing, indicating a focus on conserving capital.
What were the analyst estimates for Safecure Services' Q4 FY26?
Specific analyst estimates for Safecure Services' Q4 FY26 were not disclosed in the available research. A report from mcapital.in noted that the extracted results filing did not contain enough detail to quantify a directional impact, leading to flat projections with low confidence.
Which brokerages have changed their rating for Safecure Services?
Prior to its IPO, Minerva Capital Research Solutions assigned an 'AVOID' rating to Safecure Services, assessing the issue at 17x FY25 PAT. There is no information in the research about brokerage rating changes specifically following the Q4 FY26 results announcement.
Have mutual funds or FIIs changed their stake in Safecure Services?
Mutual funds and Foreign Institutional Investors (FIIs) held a 0% stake in Safecure Services as of the September 2026 quarter, according to Alfafinder. Promoter holding remained steady at 66.14% through the March, June, and September 2026 quarters.
What are the key analyst concerns about Safecure Services?
Analysts, including Minerva Capital Research Solutions, have highlighted key concerns such as customer concentration, negative cash flows, intense competition from unorganized players, rising manpower costs, and extended working capital cycles as risks to Safecure Services' business model.
Safecure Services H2 FY26 results
Safecure Services reported H2 FY26 (which includes Q4) revenue of ₹33.35 crore, down 25% from the same half a year earlier. Net profit for the half-year was ₹2.59 crore, a decline of 31% year-on-year, as reported by Alfafinder.
Safecure Services FY26 annual results
For the full year FY26, Safecure Services reported annual revenue of ₹66.88 crore, down 8.5% from the previous year. Net profit for the year was ₹6.03 crore, a slight decline of 2.1% year-on-year, according to the verified financial payload.