Royal Sense (ROYAL) Q4 FY26 Profit Falls 25% Despite 50% Revenue Surge
The medical distributor's FY26 revenue soared 67%, but a sharp rise in expenses and interest costs squeezed quarterly profit margins to a two-year low.
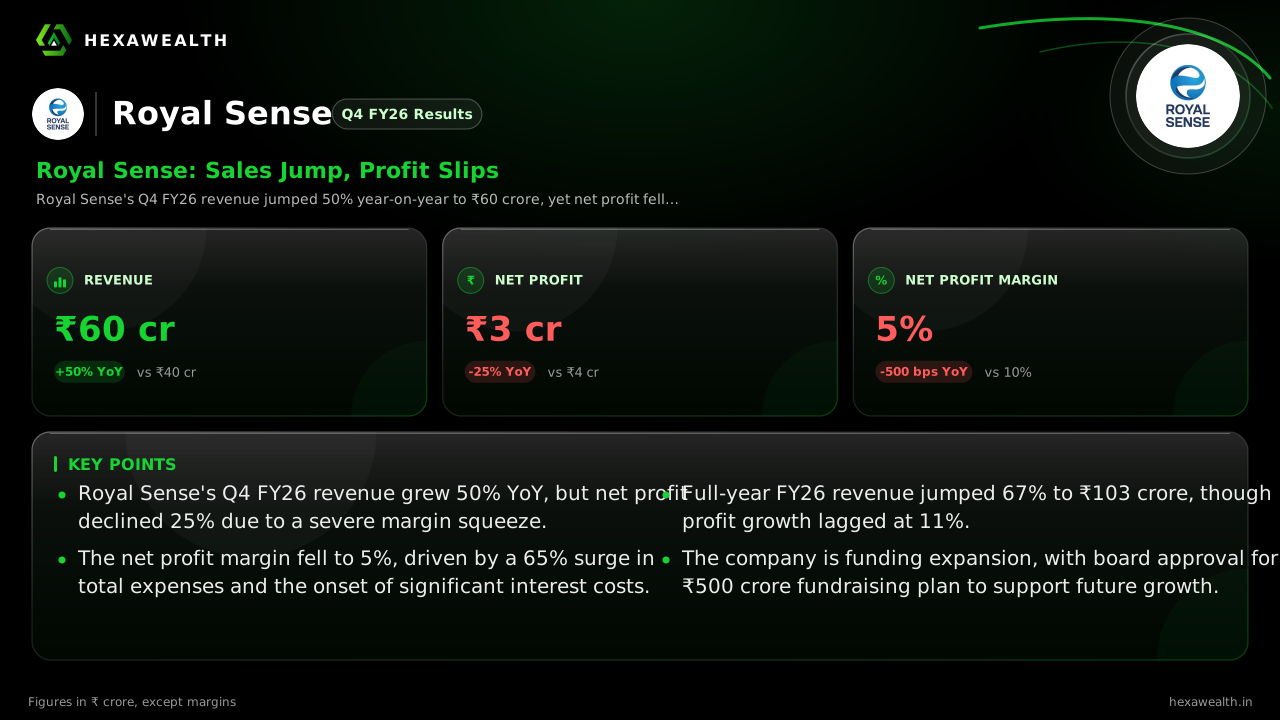
Royal Sense's Q4 FY26 revenue jumped 50% year-on-year to ₹60 crore, yet net profit fell 25% to ₹3 crore. The margin squeeze highlights the cost pressures facing the fast-growing medical equipment distributor.
For a medical equipment distributor riding India's healthcare expansion, growth is the easy part. The challenge is keeping costs in check as sales explode. Royal Sense's latest quarter shows that tension in stark relief, with revenue soaring while profits contracted sharply.
The numbers tell a story of two diverging lines. Revenue for the March 2026 quarter hit ₹60 crore, up 50% from a year ago and 39.5% from the previous quarter. Yet, net profit fell 25% in both comparisons to ₹3 crore. The net profit margin collapsed to 5%, down 500 basis points year-on-year.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 11.0
- Revenue (₹ Cr), Q2 FY25: 22.0
- Revenue (₹ Cr), Q4 FY25: 40.0
- Revenue (₹ Cr), Q2 FY26: 43.0
- Revenue (₹ Cr), Q4 FY26: 60.0
- Profit (₹ Cr), Q4 FY24: 5.0
- Profit (₹ Cr), Q2 FY25: 2.0
- Profit (₹ Cr), Q4 FY25: 4.0
- Profit (₹ Cr), Q2 FY26: 4.0
- Profit (₹ Cr), Q4 FY26: 3.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 11.0
- Revenue (₹ Cr), Q2 FY25: 22.0
- Revenue (₹ Cr), Q4 FY25: 40.0
- Revenue (₹ Cr), Q2 FY26: 43.0
- Revenue (₹ Cr), Q4 FY26: 60.0
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY24: 5.0
- Profit (₹ Cr), Q2 FY25: 2.0
- Profit (₹ Cr), Q4 FY25: 4.0
- Profit (₹ Cr), Q2 FY26: 4.0
- Profit (₹ Cr), Q4 FY26: 3.0
Net Profit Margin (%)
- Net Profit Margin (%), Q4 FY24: 45.5
- Net Profit Margin (%), Q2 FY25: 9.1
- Net Profit Margin (%), Q4 FY25: 10.0
- Net Profit Margin (%), Q2 FY26: 9.3
- Net Profit Margin (%), Q4 FY26: 5.0
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 60.0YoY +50% | 40.0 |
| Profit (₹ Cr) | 3.0YoY -25% | 4.0 |
| Net Profit Margin (%) | 5.0YoY -50% | 10.0 |
Why the top line didn't reach the bottom
The profit squeeze came from two directions. First, total expenses surged 65% year-on-year, outpacing revenue growth. Data from newboard.in shows the operating margin for the full year FY26 fell to 10.6% from 14.4% a year earlier.
Second, interest costs emerged as a new burden. The company reported ₹1 crore in interest expense for the quarter, up from near-zero levels a year ago. This aligns with a jump in borrowings to ₹13 crore at the end of FY26, as noted in the same report.
The growth engine and its fuel
The revenue surge is not a fluke. The Indian surgical equipment market is projected to grow at nearly 10% annually through 2032, according to a Ken Research report. Royal Sense, acting as a one-stop trading house, is positioned to capture this demand.
Live Chart
· ROYAL
(BSE)
ISIN: INE0QQG01019
However, this scale requires capital. The company's board approved a plan to raise up to ₹500 crore in July 2026, as reported by Flash Finance. This suggests the current borrowing and cost structure may be a feature of its growth phase, not a one-off.
Key Points
- Royal Sense's Q4 FY26 revenue grew 50% YoY, but net profit declined 25% due to a severe margin squeeze.
- The net profit margin fell to 5%, driven by a 65% surge in total expenses and the onset of significant interest costs.
- Full-year FY26 revenue jumped 67% to ₹103 crore, though profit growth lagged at 11%.
- The company is funding expansion, with board approval for a ₹500 crore fundraising plan to support future growth.
Hexa Perspective
This quarter frames the classic scaling dilemma. Revenue growth is robust and sits in a supportive sector tailwind. Yet, profitability is being sacrificed to fund that growth, evident in rising borrowings and operating costs.
The path forward hinges on whether Royal Sense can achieve operating leverage. If sales continue to climb while expense growth moderates, margins could recover. The risk is that competitive pricing in medical distribution and continued working capital needs keep profitability subdued. Investors are weighing rapid top-line expansion against the uncertainty of when—or if—the bottom line will catch up.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.