RITES Q2 FY27 Profit Falls 13.5% as Revenue Milestones Slide into Q3
The engineering consultancy's quarterly profit fell despite a robust order book, as management flagged a delay in planned revenue recognition.
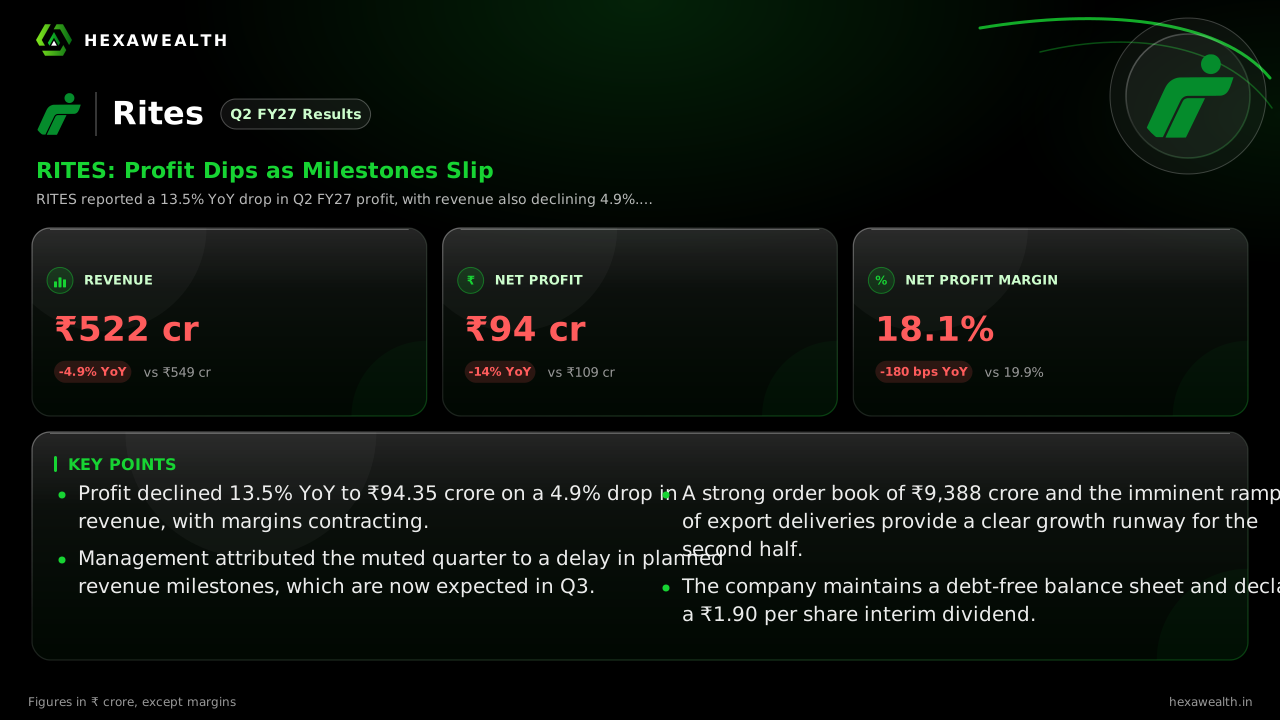
RITES reported a 13.5% YoY drop in Q2 FY27 profit, with revenue also declining 4.9%. Management attributed the muted performance to revenue milestones slipping into the next quarter, even as the order book remained strong at ₹9,388 crore.
For an infrastructure consultancy, revenue follows project milestones. RITES entered the September quarter with a near-record order book, but the translation to earnings stalled. Profit fell 13.5% from a year ago to ₹94.35 crore, as revenue also declined 4.9%.
The numbers show a sequential slowdown. Revenue and profit dipped 2% and 3.5% from the June quarter. The net profit margin contracted 180 basis points year-on-year to 18.1%, pressured by rising total expenses.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 521.82YoY -4.9% | 532.20 | 548.74 |
| Profit (₹ Cr) | 94.35YoY -14% | 97.78 | 109.10 |
| Net Profit Margin (%) | 18.1YoY -9% | 18.4 | 19.9 |
Why the Milestones Mattered
Chairman Rahul Mithal told PSUWatch the performance was muted because certain planned revenue milestones slid into Q3. This delay in project execution and recognition directly hit the top line. While other income rose sharply, it wasn't enough to offset the core revenue miss.
Expenses grew 1.6% YoY even as revenue fell, squeezing margins. Employee costs rose 2.2%, which Arthneeti notes is part of a strategic build-up for order execution. The company remains debt-free, a key strength in a capital-intensive sector.
The Order Book Cushion
Visibility remains strong. The order book stood at ₹9,388 crore as of September 30, according to the company's investor presentation. RITES secured new orders worth ₹446 crore in the quarter, including a major consultancy win for the Patna Metro.
The export segment, which saw a sharp revenue drop, is expected to gain momentum. Management expects supplies to Bangladesh and Mozambique to boost exports and profits from Q3 FY27 onward, as noted in the presentation.
Key Points
- Profit declined 13.5% YoY to ₹94.35 crore on a 4.9% drop in revenue, with margins contracting.
- Management attributed the muted quarter to a delay in planned revenue milestones, which are now expected in Q3.
- A strong order book of ₹9,388 crore and the imminent ramp-up of export deliveries provide a clear growth runway for the second half.
- The company maintains a debt-free balance sheet and declared a ₹1.90 per share interim dividend.
Hexa Perspective
The quarter underscores the lumpy nature of project-based revenue, where timing is everything. The 13.5% profit drop is a pause, not a breakdown, given the ₹9,388 crore order backlog.
The test is execution. If the delayed Q2 milestones and promised export shipments materialize in Q3, the full-year targets are still within reach. Investors are weighing near-term volatility against the long-term visibility that order book provides.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.