Power Mech Projects (POWERMECH) Q2 FY27 Revenue Jumps 30% as Profit Trails Behind
The infrastructure firm's September quarter saw robust top-line growth, but higher costs and interest expenses kept profit growth in check.
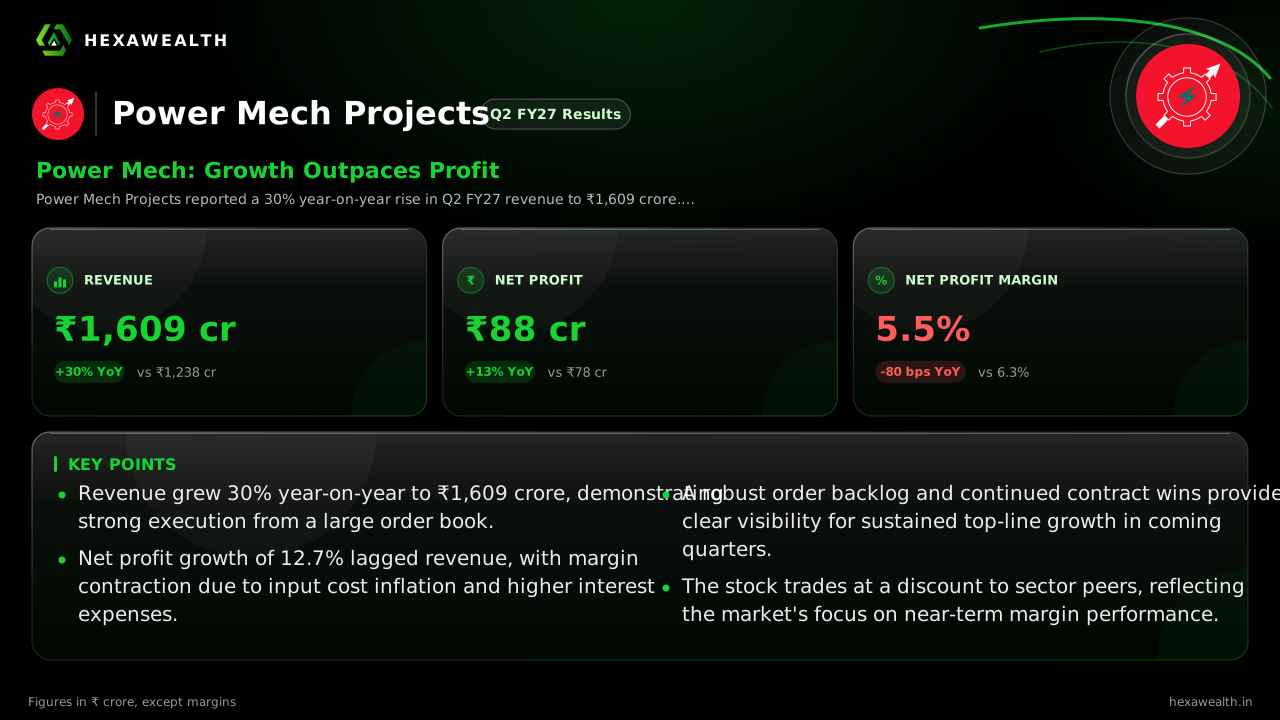
Power Mech Projects reported a 30% year-on-year rise in Q2 FY27 revenue to ₹1,609 crore. Net profit grew 12.7% to ₹88 crore, with margins contracting due to rising costs and a 28% quarterly jump in interest expense.
For Power Mech Projects, the September quarter was about translating a massive order book into revenue, a task it accomplished with a 30% year-on-year sales jump. The catch was that profit grew at less than half that pace, as costs and interest expenses rose even faster.
The numbers show a company in high-growth execution mode. Revenue reached ₹1,609 crore, while net profit settled at ₹88 crore. The net profit margin contracted 80 basis points from a year ago to 5.5%, highlighting the profitability squeeze.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 1,237.9
- Revenue (₹ Cr), Q3 FY26: 1,419.6
- Revenue (₹ Cr), Q4 FY26: 2,110.7
- Revenue (₹ Cr), Q1 FY27: 1,623.7
- Revenue (₹ Cr), Q2 FY27: 1,609.0
- Profit (₹ Cr), Q2 FY26: 78.1
- Profit (₹ Cr), Q3 FY26: 99.6
- Profit (₹ Cr), Q4 FY26: 153.4
- Profit (₹ Cr), Q1 FY27: 89.3
- Profit (₹ Cr), Q2 FY27: 88.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 1,237.9
- Revenue (₹ Cr), Q3 FY26: 1,419.6
- Revenue (₹ Cr), Q4 FY26: 2,110.7
- Revenue (₹ Cr), Q1 FY27: 1,623.7
- Revenue (₹ Cr), Q2 FY27: 1,609.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26: 78.1
- Profit (₹ Cr), Q3 FY26: 99.6
- Profit (₹ Cr), Q4 FY26: 153.4
- Profit (₹ Cr), Q1 FY27: 89.3
- Profit (₹ Cr), Q2 FY27: 88.0
Net Profit Margin
- Net Profit Margin, Q2 FY26: 6.3%
- Net Profit Margin, Q3 FY26: 7.0%
- Net Profit Margin, Q4 FY26: 7.3%
- Net Profit Margin, Q1 FY27: 5.5%
- Net Profit Margin, Q2 FY27: 5.5%
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 1,609.0YoY +30% | 1,623.7 | 1,237.9 |
| Profit (₹ Cr) | 88.0YoY +13% | 89.3 | 78.1 |
| Net Profit Margin | 5.5%YoY -13% | 5.5% | 6.3% |
Where the profit went
Revenue growth was broad-based, but costs grew almost as quickly. According to Sahi.com, EBITDA margin eased 77 basis points to 11.11%, pressured by raw material costs and a shift toward lower-margin civil infrastructure work. Interest expense jumped 28% from the June quarter, a sign of higher working capital needs for scaling projects.
Depreciation also rose sharply, up 44% from last year, reflecting the heavy capital expenditure of recent quarters. The company invested nearly ₹500 crore in capex in the first half, as reported by Equitypandit.com, to support future growth.
A runway built on orders
The pressure on near-term margins is offset by exceptional revenue visibility. The company's order backlog, excluding mining, stood at a robust ₹16,229 crore at the end of the June quarter. Recent wins, like a ₹490 crore international contract from a Saudi joint venture reported by AlfaFinder, add to this pipeline.
Live Chart
· POWERMECH
(BSE)
ISIN: INE211R01019
Management has set an ambitious full-year order inflow target of ₹12,000 crore. With power sector investments driving growth, as highlighted in a Crisil report, the company's core markets remain strong.
The market's measured reaction
The stock closed slightly lower on the results day, a typical reaction to margin pressure despite good growth. Analysts maintain a positive outlook, with an average price target implying significant upside, according to data from Finance.yahoo.com. The valuation trades at a 35% discount to the industry average PE, pricing in the current margin challenges.
Key Points
- Revenue grew 30% year-on-year to ₹1,609 crore, demonstrating strong execution from a large order book.
- Net profit growth of 12.7% lagged revenue, with margin contraction due to input cost inflation and higher interest expenses.
- A robust order backlog and continued contract wins provide clear visibility for sustained top-line growth in coming quarters.
- The stock trades at a discount to sector peers, reflecting the market's focus on near-term margin performance.
Hexa Perspective
The quarter paints a picture of a company successfully scaling operations, with the growing pains of margin compression and higher leverage that often accompany such phases. The critical question is whether the margin pressure is a temporary cost of growth or a structural shift.
The answer likely lies in the mix of future work. A greater contribution from higher-margin mining and long-term O&M contracts, which management is targeting, could ease the squeeze. For now, investors are weighing strong revenue momentum against the patience required for profitability to catch up.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.