All posts

Follow Us

LinkedInInstagramX
Quarterly ResultsArchiveLast updated 6 November 20262 min read

Multibase India (MULTIBASE) Q2 FY27's Q2 Profit Rises 29% as Revenue Jumps, But Margins Narrow Sharply

The specialty materials maker posted strong top-line growth of 39.6% YoY, but a sharp rise in raw material costs squeezed its net profit margin.

By Abhinav Singhvi, Founder & CEO Hexawealth · Created 6 November 2026

Multibase India's Q2 FY27 revenue surged nearly 40% year-on-year, driving profit higher. However, profit growth lagged sales as the cost of materials consumed more than doubled, pressuring margins.

For a specialty materials maker, the quarter often hinges on balancing volume growth against volatile input costs. Multibase India's September quarter delivered the growth, with revenue surging 39.6% year-on-year to ₹25.87 crore, but the cost side of that equation tightened sharply.

The numbers show a clear divergence. Profit after tax grew a healthy 29.4% to ₹3.7 crore, yet it trailed the revenue increase. The net profit margin contracted to 14.3%, down from 15.5% a year ago and 16.0% last quarter.

Revenue & profit

Revenue (₹ Cr)

Profit (₹ Cr)

Revenue & profitQ2 FY26 18.53, Q3 FY26 13.53, Q4 FY26 17.76, Q1 FY27 20.96, Q2 FY27 25.87. Q2 FY26 2.86, Q3 FY26 3.28, Q4 FY26 1.99, Q1 FY27 3.36, Q2 FY27 3.70010203040Q2 '26Q3 '26Q4 '26Q1 '27Q2 '27
  • Revenue (₹ Cr), Q2 FY26: 18.53
  • Revenue (₹ Cr), Q3 FY26: 13.53
  • Revenue (₹ Cr), Q4 FY26: 17.76
  • Revenue (₹ Cr), Q1 FY27: 20.96
  • Revenue (₹ Cr), Q2 FY27: 25.87
  • Profit (₹ Cr), Q2 FY26: 2.86
  • Profit (₹ Cr), Q3 FY26: 3.28
  • Profit (₹ Cr), Q4 FY26: 1.99
  • Profit (₹ Cr), Q1 FY27: 3.36
  • Profit (₹ Cr), Q2 FY27: 3.70

Revenue (₹ Cr)

Revenue (₹ Cr)Q2 FY26 18.53, Q3 FY26 13.53, Q4 FY26 17.76, Q1 FY27 20.96, Q2 FY27 25.87010203040Q2 '26Q3 '26Q4 '26Q1 '27Q2 '27
  • Revenue (₹ Cr), Q2 FY26: 18.53
  • Revenue (₹ Cr), Q3 FY26: 13.53
  • Revenue (₹ Cr), Q4 FY26: 17.76
  • Revenue (₹ Cr), Q1 FY27: 20.96
  • Revenue (₹ Cr), Q2 FY27: 25.87

Profit (₹ Cr)

Profit (₹ Cr)Q2 FY26 2.86, Q3 FY26 3.28, Q4 FY26 1.99, Q1 FY27 3.36, Q2 FY27 3.7002468Q2 '26Q3 '26Q4 '26Q1 '27Q2 '27
  • Profit (₹ Cr), Q2 FY26: 2.86
  • Profit (₹ Cr), Q3 FY26: 3.28
  • Profit (₹ Cr), Q4 FY26: 1.99
  • Profit (₹ Cr), Q1 FY27: 3.36
  • Profit (₹ Cr), Q2 FY27: 3.70

Net Profit Margin (%)

Net Profit Margin (%)Q2 FY26 15.5, Q3 FY26 24.2, Q4 FY26 11.2, Q1 FY27 16.0, Q2 FY27 14.30%10%20%30%40%Q2 '26Q3 '26Q4 '26Q1 '27Q2 '27
  • Net Profit Margin (%), Q2 FY26: 15.5
  • Net Profit Margin (%), Q3 FY26: 24.2
  • Net Profit Margin (%), Q4 FY26: 11.2
  • Net Profit Margin (%), Q1 FY27: 16.0
  • Net Profit Margin (%), Q2 FY27: 14.3
MetricCurrentQ2 FY27PreviousQ1 FY27Same quarter LYQ2 FY26
Revenue (₹ Cr)
25.87YoY +40%
20.96
18.53
Profit (₹ Cr)
3.70YoY +29%
3.36
2.86
Net Profit Margin (%)
14.3YoY -7.7%
16.0
15.5

Why Profit Growth Lagged Behind Sales

The primary pressure came from a staggering rise in the cost of materials. According to a report from ScanX, this line item surged 145.3% year-on-year. While revenue grew by ₹7.35 crore, the cost of materials consumed rose by nearly ₹9.26 crore. A favorable inventory adjustment provided some relief, but not enough to prevent the margin squeeze.

This cost surge outpaced revenue growth, causing total expenses to rise 40.5% YoY. The company's debt-free balance sheet, noted by Univest, offers financial stability but no shield against such operational cost pressures.

The Outlook and Strategic Focus

Management's strategic focus, as outlined by StockFin.ai, remains on deepening penetration in automotive and electronics segments while localizing manufacturing at its Daman facility. This move aims to mitigate import dependency and currency risks over the long term.

Live Chart

· MULTIBASE

(BSE)

ISIN: INE678F01014

The near-term trajectory, however, will depend heavily on raw material cost trends. The company's significant inventory build-up, which weighed on operating cash flow in the first half, suggests it may be preparing for continued demand or bracing for further input cost volatility.

Key Points

  • Revenue growth remained robust at 39.6% YoY, marking a second consecutive quarter of strong sequential expansion.
  • Net profit margin narrowed by 170 basis points from the previous quarter due to raw material costs rising over three times faster than sales.
  • The company maintains a debt-free balance sheet with strong cash reserves, supporting operational flexibility amid cost pressures.

Hexa Perspective

The quarter underscores a classic growth-versus-margin trade-off. Multibase is successfully capturing demand, likely in its core automotive and electronics markets, but is currently absorbing a severe cost hit. The sustainability of its profit growth now hinges on whether these input costs recede or if the company can achieve pricing power or operational efficiencies to offset them. The localization strategy is a sensible long-term hedge, but its benefits will take time to materialize. Investors are left weighing strong top-line momentum against a profitability squeeze that has yet to find a floor.

Share or follow HexaWealth

Also read

Want this applied to your portfolio?

Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
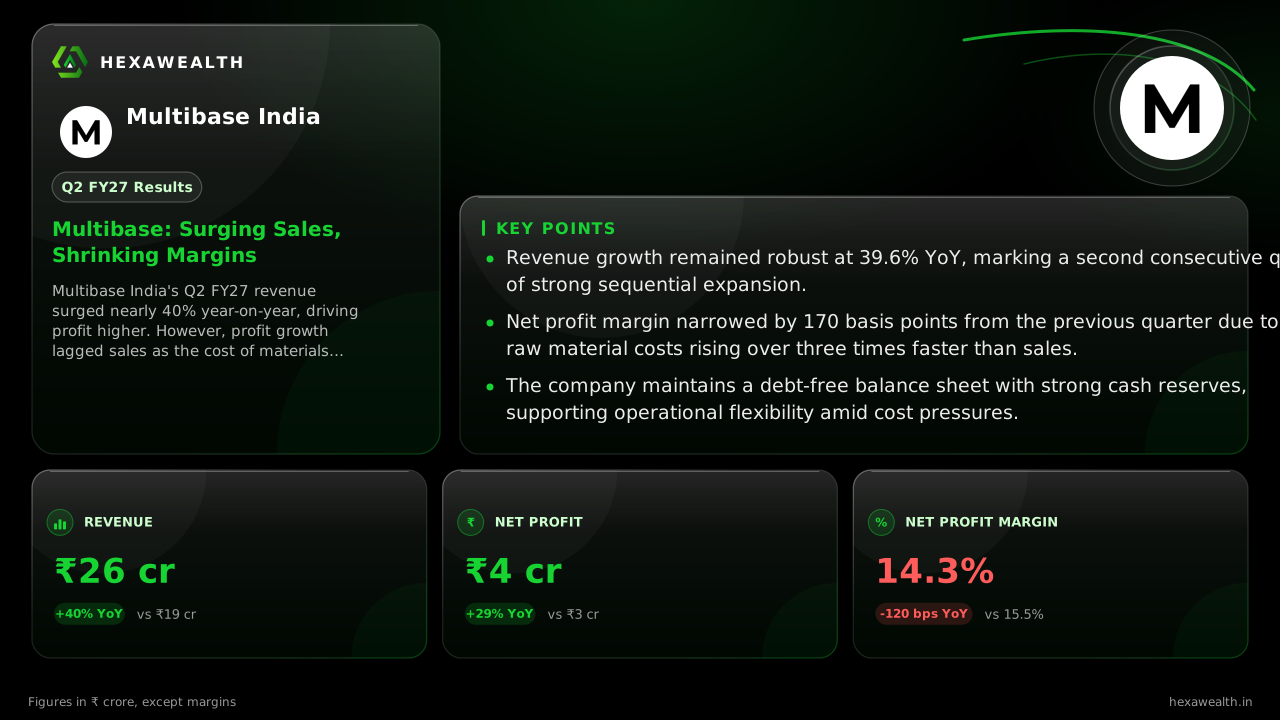
Multibase India (MULTIBASE) Q2 FY27 results, revenue and profits.

Frequently asked questions

What were Multibase India's Q2 FY27 results?
Multibase India reported revenue of ₹25.87 crore and a net profit of ₹3.70 crore for the quarter ended September 2026. This represents year-on-year growth of 39.6% in revenue and 29.4% in profit. However, the net profit margin narrowed to 14.3% from 15.5% a year earlier.
Why did Multibase India's Q2 profit margin decline despite higher sales?
Multibase India's net profit margin narrowed because the cost of materials consumed surged 145.3% year-on-year, far outpacing its 39.6% revenue growth. This severe input cost inflation, reported by ScanX, squeezed profitability even as sales volumes increased.
What was the main cost pressure for Multibase India in Q2 FY27?
The primary cost pressure was a massive increase in raw material expenses. The cost of materials consumed jumped 145.3% year-on-year to over ₹15.63 crore, as noted by ScanX. This was the main driver behind total expenses rising 40.5%, faster than revenue growth.
What is Multibase India's management outlook after Q2 FY27 results?
Management's strategic focus, per StockFin.ai, is on expanding in automotive and electronics segments and localizing manufacturing at its Daman facility to reduce import dependency. No formal financial guidance was provided, but the company emphasized innovation and financial discipline.
What is the demand outlook for thermoplastic elastomers in India?
Industry analysis from IndexBox suggests India's thermoplastic elastomer demand is projected to grow at 8–10% annually through 2035. Growth is driven by automotive lightweighting and substitution of traditional materials, with automotive applications accounting for 30–35% of domestic consumption.
Which customer segments drive Multibase India's growth?
Multibase India operates in a single segment but serves multiple industries. Analysis from StockFin.ai indicates the company has a strategic focus on expanding penetration in automotive, electronics, and industrial segments, which are its key end markets.
Is Multibase India a debt-free company?
Yes, Multibase India maintains a debt-free balance sheet. Reports from Univest and ScanX confirm the company has no borrowings, with cash and equivalents of over ₹62 crore as of September 2026, supporting strong financial stability.
What are Multibase India's capacity expansion plans?
The company has disclosed plans to expand local manufacturing at its Daman facility, as per StockFin.ai. This aims to support growth in automotive and electronics segments and mitigate import dependency, though specific capex figures were not detailed in the quarterly filings.
Did Multibase India's Q2 results beat analyst estimates?
The available research reports from ScanX and Univest present the declared results without referencing specific analyst estimates or consensus. Therefore, it is not clear if the results constituted a beat or a miss against market expectations.
How did Multibase India's stock price react to the Q2 results?
The research snippets do not provide specific price action for the results announcement date. The stock had closed at ₹175.45 on November 5, 2026, the day after the results were declared, but immediate reaction data is not covered in the provided sources.
Are institutional investors buying Multibase India stock?
As of September 2026, foreign and domestic institutional investors held a negligible 0% stake in Multibase India, according to StockFin.ai. Promoters hold a steady 75% stake, with the remaining 25% held by public shareholders.
What are the key raw material risks for Multibase India?
The key risk is extreme volatility in the cost of materials, which surged 145% YoY in Q2. The company imports certain raw materials from its French parent, making it exposed to global price swings and currency fluctuations, as noted by Inve.money.
Multibase India Q2 FY27 results?
Multibase India's Q2 FY27 results, for the quarter ended September 2026, showed revenue of ₹25.87 crore and net profit of ₹3.70 crore. This was a growth of 39.6% and 29.4% year-on-year, respectively. The results were declared on November 4, 2026.
Multibase India Q2 net profit?
Multibase India's net profit for Q2 FY27 (September 2026 quarter) was ₹3.70 crore. This marks an increase of 29.4% from the ₹2.86 crore net profit reported in the same quarter of the previous fiscal year, Q2 FY26.
Why did Multibase India profits rise slower than sales?
Multibase India's profit rose slower than sales because raw material costs exploded, increasing 145.3% year-on-year according to ScanX. This severe cost inflation compressed margins, causing the 29.4% profit growth to lag behind the 39.6% revenue growth.