Midwest (MIDWESTLTD) Q2 FY27's Q2 Growth Slows as a Key Mine Remains Shut
Midwest's consolidated revenue grew 15% year-on-year, but a sequential dip and a key mine suspension reveal operational headwinds.
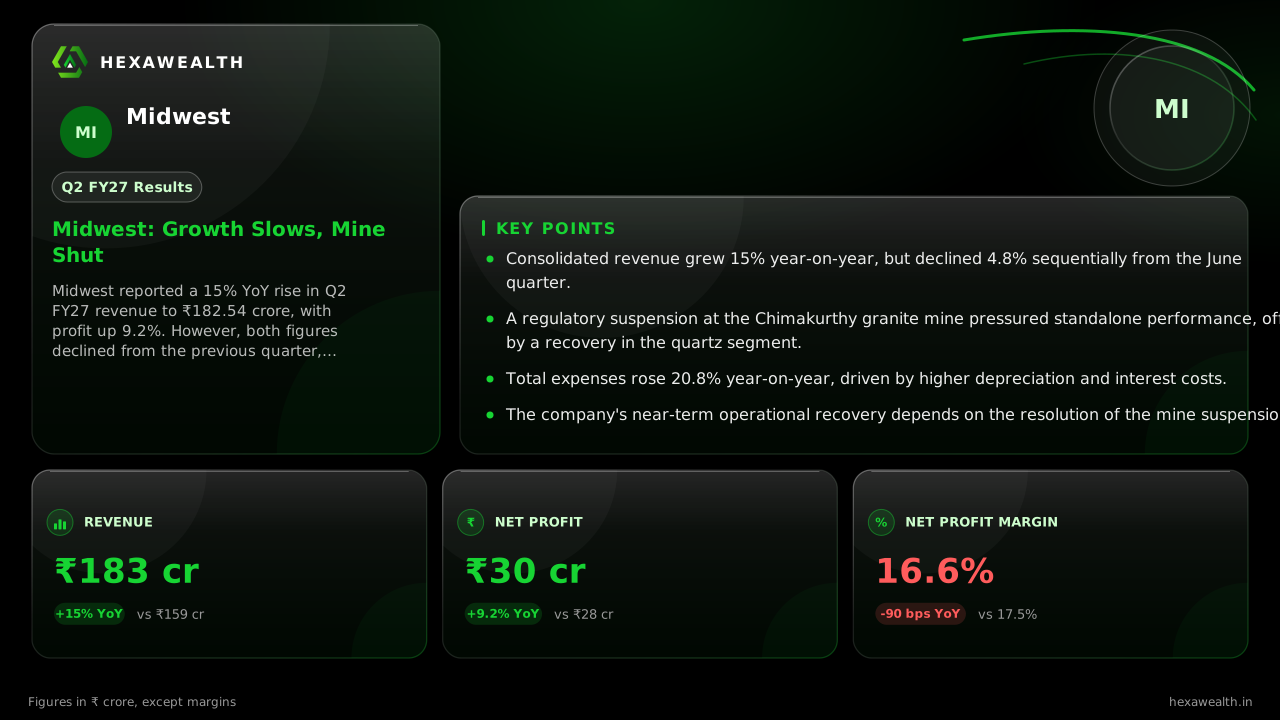
Midwest reported a 15% YoY rise in Q2 FY27 revenue to ₹182.54 crore, with profit up 9.2%. However, both figures declined from the previous quarter, pressured by a regulatory shutdown at the Chimakurthy granite mine.
For Midwest, a natural stone miner, the September quarter was about managing a disruption. A regulatory suspension at a key granite mine clipped standalone sales, leaving the group reliant on its quartz processing unit to deliver year-on-year growth.
Revenue rose 15% from a year ago to ₹182.54 crore, while profit grew 9.2% to ₹30.25 crore. Sequentially, both metrics softened, with revenue down 4.8% and profit down 2.5%. The net profit margin improved slightly from the June quarter but remained 90 basis points below last year's level.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 158.69
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 128.86
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 215.81
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 191.84
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 182.54
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 27.71
- Profit (₹ Cr), Q3 FY26 (Dec 2025): 17.36
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 37.02
- Profit (₹ Cr), Q1 FY27 (Jun 2026): 31.04
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 30.25
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 158.69
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 128.86
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 215.81
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 191.84
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 182.54
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 27.71
- Profit (₹ Cr), Q3 FY26 (Dec 2025): 17.36
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 37.02
- Profit (₹ Cr), Q1 FY27 (Jun 2026): 31.04
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 30.25
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY26 (Sep 2025): 17.5
- Net Profit Margin (%), Q3 FY26 (Dec 2025): 13.5
- Net Profit Margin (%), Q4 FY26 (Mar 2026): 17.2
- Net Profit Margin (%), Q1 FY27 (Jun 2026): 16.2
- Net Profit Margin (%), Q2 FY27 (Sep 2026): 16.6
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 182.54 | 191.84 |
| Profit (₹ Cr) | 30.25 | 31.04 |
| Net Profit Margin (%) | 16.6 | 16.2 |
The Chimakurthy disruption
A prohibitory order from the Directorate General of Mines Safety halted operations at the Chimakurthy granite mine in early October, as reported by StockFin.ai. While the full-quarter impact was muted, the scanx.trade report notes it contributed to a 25% year-on-year drop in standalone revenue. This core mining disruption forced the company to lean on other segments.
Quartz picks up the slack
Consolidated growth was salvaged by the quartz processing business, which swung to a profit. According to a Multibagg.ai report, the segment posted a profit before interest and tax of ₹3.85 crore, recovering from a loss in the prior quarter. This, along with a 237% surge in other income, helped offset the mining weakness and keep consolidated profit in positive territory year-on-year.
Costs also rose, with total expenses up 20.8% from last year. Depreciation jumped nearly 24%, reflecting recent capital expenditure, while interest expense grew 19% quarter-on-quarter.
Live Chart
· MIDWESTLTD
(BSE)
ISIN: INE0XAD01024
How long does the squeeze last?
The near-term outlook hinges on the mine restart. The DGMS order remains in effect until withdrawn, creating uncertainty. Management's growth narrative now rests on new projects like a quartz plant expansion and a planned facility in Sri Lanka, but these are future catalysts.
Financially, the balance sheet is stable with a low debt-to-equity ratio of 0.18. The stock, down 14% over the past year, trades at a P/E of 39.5, a discount to the industry average.
Key Points
- Consolidated revenue grew 15% year-on-year, but declined 4.8% sequentially from the June quarter.
- A regulatory suspension at the Chimakurthy granite mine pressured standalone performance, offset by a recovery in the quartz segment.
- Total expenses rose 20.8% year-on-year, driven by higher depreciation and interest costs.
- The company's near-term operational recovery depends on the resolution of the mine suspension.
Hexa Perspective
The quarter reveals a business in transition, caught between an operational setback and a strategic pivot. The mine suspension is a clear near-term drag, but its financial impact was contained this quarter by a strong contribution from quartz.
The path forward involves resolving the regulatory overhang while successfully ramping up new processing capacity. Investors are weighing the execution risk of these new projects against the company's solid balance sheet and its position in a structurally growing stone market.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.