Meenakshi India (MEEIND) Q1 FY27 Profit Jumps 153% as Core Business Turns a Corner
A surge in other income drove a 153% profit jump, but the real story is a return to positive operating margins after a tariff-hit year.
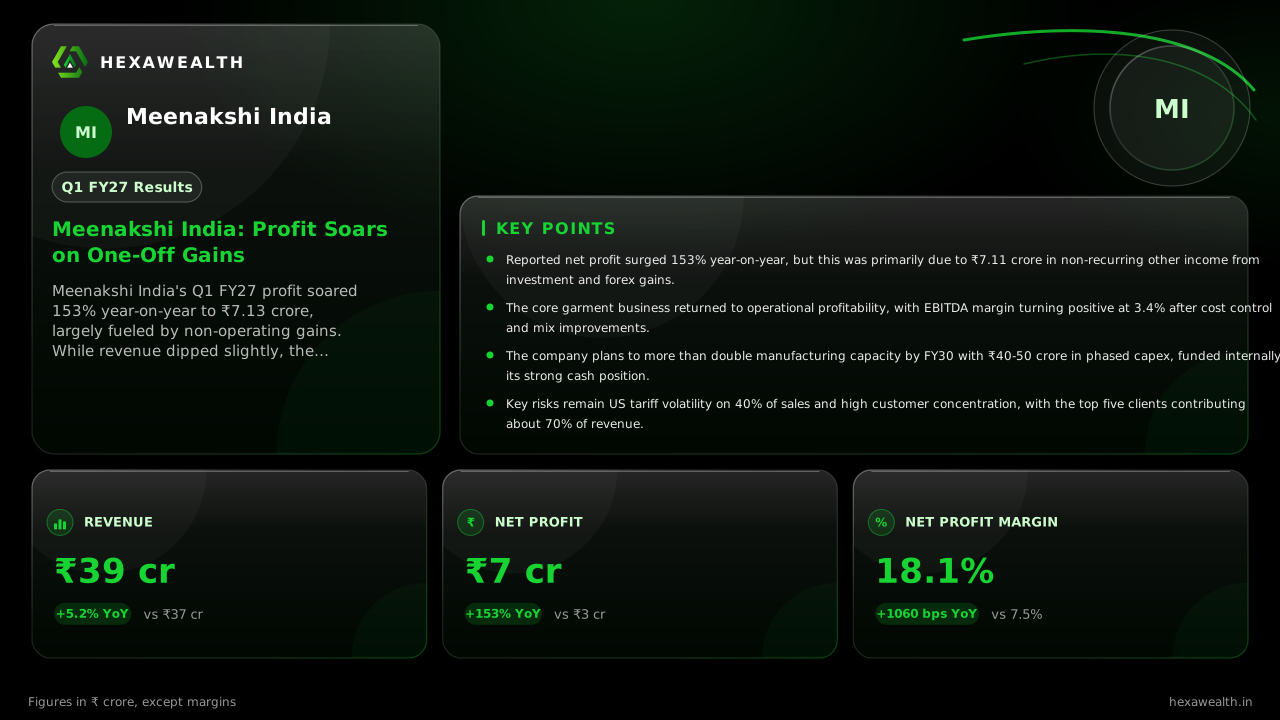
Meenakshi India's Q1 FY27 profit soared 153% year-on-year to ₹7.13 crore, largely fueled by non-operating gains. While revenue dipped slightly, the core garment business turned operationally positive, signaling a recovery from last year's tariff pressures.
For Meenakshi India, a premium apparel exporter, the June quarter was about stabilizing after a disruptive year. While revenue was soft, the company posted a ₹7.13 crore net profit, a 153% jump from a year ago. The headline profit surge, however, masks a more nuanced story of operational repair and a significant one-off boost.
The numbers show a clear divergence. Revenue from operations, as reported by InvestorStack, dipped 3.4% year-on-year to ₹32.24 crore. Yet, total income rose 5.2% to ₹39.36 crore, and net profit margin expanded dramatically to 18.1% from 7.5% a year earlier.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 77.38
- Revenue (₹ Cr), Q1 FY26: 37.43
- Revenue (₹ Cr), Q3 FY26: 42.22
- Revenue (₹ Cr), Q4 FY26: 46.71
- Revenue (₹ Cr), Q1 FY27: 39.36
- Profit (₹ Cr), Q4 FY25: 25.9
- Profit (₹ Cr), Q1 FY26: 2.82
- Profit (₹ Cr), Q3 FY26: 2.36
- Profit (₹ Cr), Q4 FY26: 4.52
- Profit (₹ Cr), Q1 FY27: 7.13
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 77.38
- Revenue (₹ Cr), Q1 FY26: 37.43
- Revenue (₹ Cr), Q3 FY26: 42.22
- Revenue (₹ Cr), Q4 FY26: 46.71
- Revenue (₹ Cr), Q1 FY27: 39.36
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY25: 25.9
- Profit (₹ Cr), Q1 FY26: 2.82
- Profit (₹ Cr), Q3 FY26: 2.36
- Profit (₹ Cr), Q4 FY26: 4.52
- Profit (₹ Cr), Q1 FY27: 7.13
Net Profit Margin (%)
- Net Profit Margin (%), Q4 FY25: 33.5
- Net Profit Margin (%), Q1 FY26: 7.5
- Net Profit Margin (%), Q3 FY26: 5.6
- Net Profit Margin (%), Q4 FY26: 9.7
- Net Profit Margin (%), Q1 FY27: 18.1
| Metric | CurrentQ1 FY27 | PreviousQ4 FY26 | Same quarter LYQ1 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 39.36YoY +5.2% | 46.71 | 37.43 |
| Profit (₹ Cr) | 7.13YoY +153% | 4.52 | 2.82 |
| Net Profit Margin (%) | 18.1YoY +141% | 9.7 | 7.5 |
The One-Off Driving the Profit
The real driver of the profit jump was a ₹7.11 crore surge in other income, as detailed in the earnings call summary. This included unrealized fair value gains on investments and foreign exchange reversals that management explicitly flagged as market-linked and non-recurring. This windfall accounted for nearly all of the quarter's profit before tax.
Stripping that away reveals the quarter's operational achievement. The core garment business turned its EBITDA positive at a 3.4% margin, according to InvestorStack, after a marginal loss a year ago. This shift reflects better product mix, pricing discipline, and a 6.9% reduction in total expenses.
A Fragile Recovery and a Long Roadmap
The operational turnaround is early-stage and faces headwinds. Management noted that US tariff policy, affecting 40% of revenue, remains volatile. To hedge this, the company has a contingency MoU with a Sri Lankan manufacturer. Its growth plan is a phased capacity expansion from 18 lakh to 38 lakh pieces by FY30, backed by ₹40-50 crore in capex funded from its debt-free balance sheet.
Live Chart
· MEEIND
(BSE)
ISIN: INE208H01016
Guidance for the year ahead is measured. Management targets roughly 70% capacity utilization for FY27 and aims for a 17% EBITDA margin by FY28, a return toward pre-tariff levels. For FY30, they have set a conservative revenue target of ₹565 crore.
Key Points
- Reported net profit surged 153% year-on-year, but this was primarily due to ₹7.11 crore in non-recurring other income from investment and forex gains.
- The core garment business returned to operational profitability, with EBITDA margin turning positive at 3.4% after cost control and mix improvements.
- The company plans to more than double manufacturing capacity by FY30 with ₹40-50 crore in phased capex, funded internally from its strong cash position.
- Key risks remain US tariff volatility on 40% of sales and high customer concentration, with the top five clients contributing about 70% of revenue.
Hexa Perspective
The quarter presents a tale of two profits. The reported figure is flattered by a one-off, but the underlying move to positive operating margins is the more meaningful signal. It suggests the corrective measures taken during last year's tariff disruption are starting to work.
The path forward hinges on sustaining this operational momentum without the support of exceptional income. Investors will watch for consistent progress toward the 17% EBITDA margin target, which requires stable trade policy and successful execution of the capacity expansion. The company's strong, debt-free balance sheet provides a solid foundation for this multi-year plan, but the premium export business remains exposed to global trade winds.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.