Matrimony.com (MATRIMONY) Q2 FY27 Profit Triples as Revenue Growth Meets Flat Spending
The matchmaking leader’s Q2 net profit soared 167% year-on-year, powered by strong subscription growth and disciplined cost control that sent margins sharply higher.
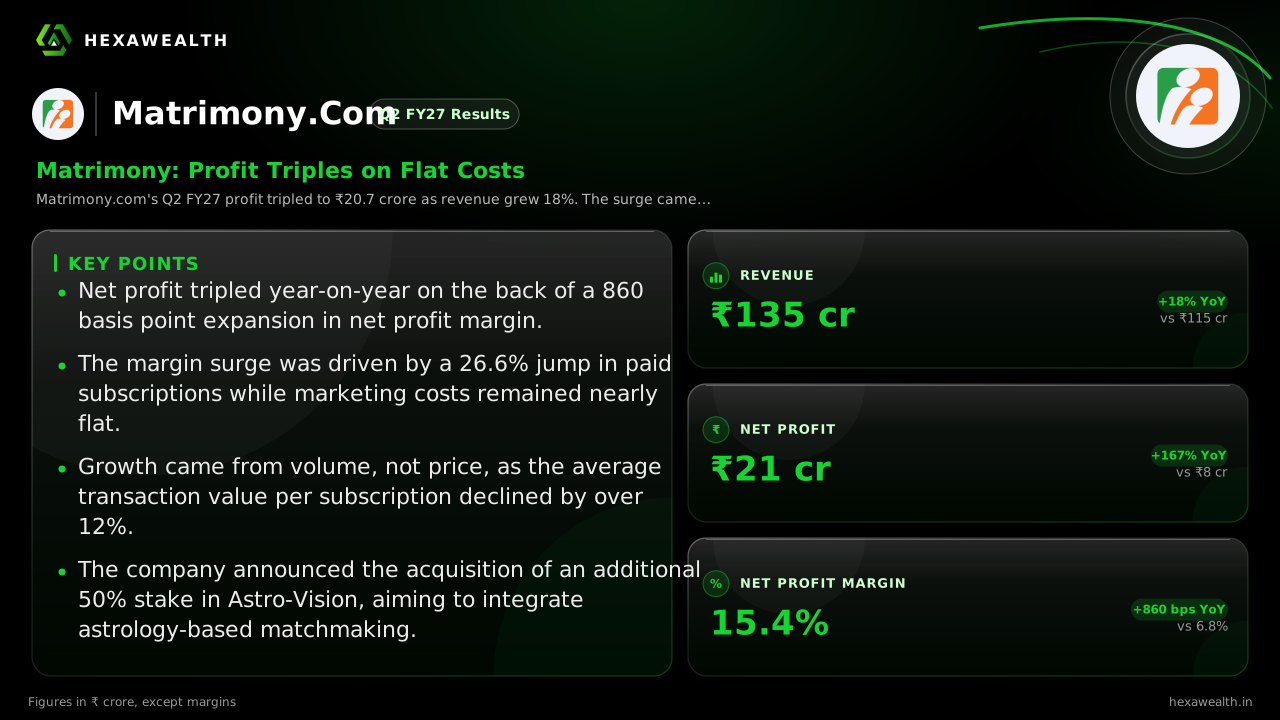
Matrimony.com's Q2 FY27 profit tripled to ₹20.7 crore as revenue grew 18%. The surge came from adding 26.6% more paid subscribers while keeping marketing spend flat, a powerful mix of volume growth and operating leverage.
For India’s leading online matchmaker, the September quarter was a story of volume winning over price. Matrimony.com added users aggressively while keeping its spending almost unchanged, turning modest revenue growth into a profit surge.
Revenue rose 17.6% year-on-year to ₹134.8 crore, while net profit jumped 167% to ₹20.7 crore. The net profit margin expanded to 15.4%, nearly nine percentage points higher than a year ago. This gap between top-line growth and bottom-line explosion defines the quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 114.59
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 113.24
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 116.83
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 130.51
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 134.76
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 7.76
- Profit (₹ Cr), Q3 FY26 (Dec 2025): 8.30
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 9.71
- Profit (₹ Cr), Q1 FY27 (Jun 2026): 19.08
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 20.73
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 114.59
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 113.24
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 116.83
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 130.51
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 134.76
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 7.76
- Profit (₹ Cr), Q3 FY26 (Dec 2025): 8.30
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 9.71
- Profit (₹ Cr), Q1 FY27 (Jun 2026): 19.08
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 20.73
Net Profit Margin
- Net Profit Margin, Q2 FY26 (Sep 2025): 6.8%
- Net Profit Margin, Q3 FY26 (Dec 2025): 7.3%
- Net Profit Margin, Q4 FY26 (Mar 2026): 8.3%
- Net Profit Margin, Q1 FY27 (Jun 2026): 14.6%
- Net Profit Margin, Q2 FY27 (Sep 2026): 15.4%
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 134.76 | 130.51 |
| Profit (₹ Cr) | 20.73 | 19.08 |
| Net Profit Margin | 15.4% | 14.6% |
The engine behind the margin leap
The profit jump was driven entirely by the core matchmaking business, which contributes over 99% of revenue. According to Multibagg.ai, matchmaking segment EBITDA margin hit 29.7%, up from 17.1% a year ago. This expansion came from a powerful combination: paid subscriptions grew 26.6% year-on-year to 302,000, while marketing expense for the segment actually fell 0.8%.
The company achieved this by holding its largest cost line steady as revenue climbed. Total expenses rose just 2.2% year-on-year. Chairman Murugavel Janakiraman told The Hindu BusinessLine the company “continued our growth momentum… by more than doubling our profits.” The strategy is clear—acquire users efficiently and let operating leverage do the rest.
The trade-off beneath the growth
This volume-led model has a catch. While subscriptions soared, the average transaction value (ATV) fell 12.2% year-on-year to ₹4,313, as reported by Multibagg.ai. The company is trading price for volume, betting that a larger subscriber base at lower average revenue per user will deliver more profit through scale.
Live Chart
· MATRIMONY
(BSE)
ISIN: INE866R01028
The market’s initial reaction was muted, with the stock closing virtually flat on results day. Investors may be weighing whether this margin level is sustainable if ATV pressure continues or if marketing spend needs to rise to maintain subscriber momentum.
Key Points
- Net profit tripled year-on-year on the back of a 860 basis point expansion in net profit margin.
- The margin surge was driven by a 26.6% jump in paid subscriptions while marketing costs remained nearly flat.
- Growth came from volume, not price, as the average transaction value per subscription declined by over 12%.
- The company announced the acquisition of an additional 50% stake in Astro-Vision, aiming to integrate astrology-based matchmaking.
Hexa Perspective
Matrimony.com has demonstrated impressive operating leverage this quarter, proving it can grow its user base without proportionally increasing its cost base. The sustainability of this model hinges on two factors: maintaining subscriber growth without a significant rebound in customer acquisition costs, and managing the decline in average transaction value.
The current margin expansion is a direct result of a specific, disciplined spending period. If competition intensifies or subscriber growth slows, the company may face pressure to increase marketing spend, which would test the durability of these elevated profitability levels. For now, the focus on volume over price is delivering exceptional bottom-line results.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.