Madala Holdings (MADALA) Q1 FY27 Profit Falls 23% as Redevelopment Costs Bite
The real estate firm's Q1 profit fell sharply despite higher revenue, weighed down by accelerated depreciation for a Hyderabad redevelopment plan.
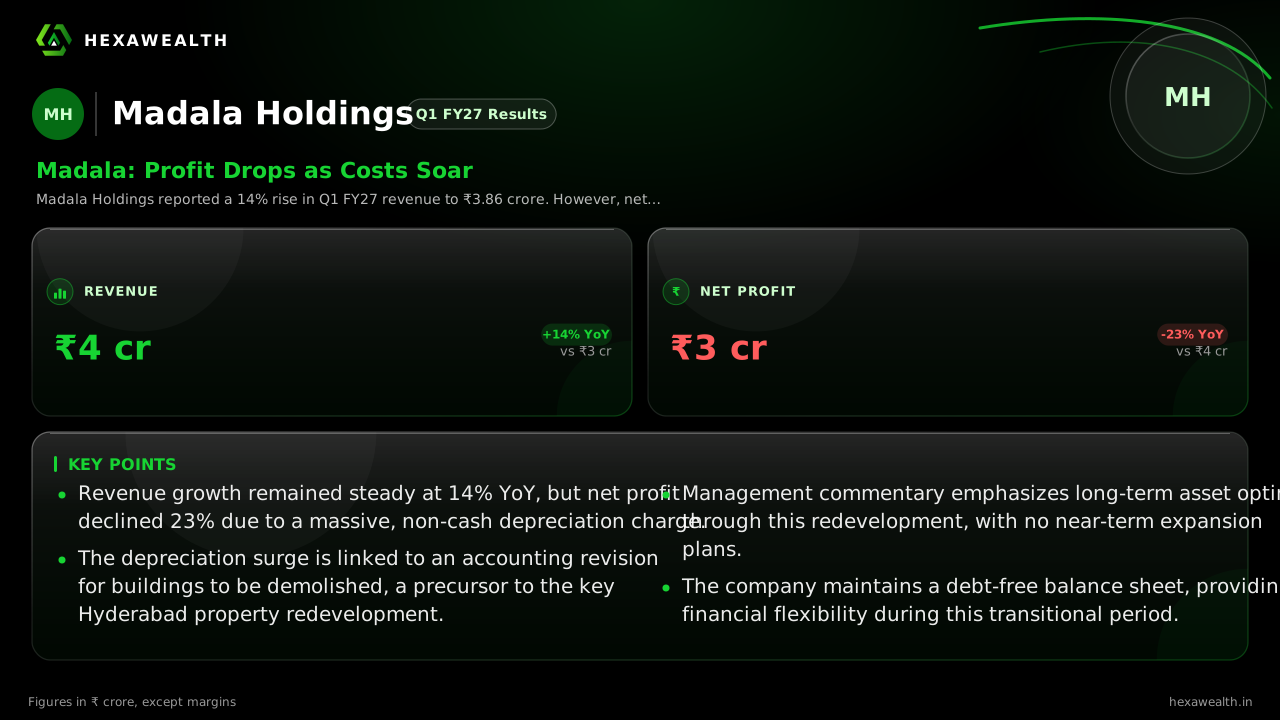
Madala Holdings reported a 14% rise in Q1 FY27 revenue to ₹3.86 crore. However, net profit declined 23% year-on-year to ₹3.43 crore, pressured by a massive surge in depreciation costs linked to an asset redevelopment project.
For Madala Holdings, now a pure-play real estate company, the first quarter was about navigating its future. The numbers show a business in transition, where a planned redevelopment of its core Hyderabad asset is already reshaping the financials.
Revenue grew 14% year-on-year to ₹3.86 crore, continuing a steady climb. Yet, net profit fell 23% to ₹3.43 crore. The divergence stems from a nearly 800% surge in depreciation, which Scanx.trade reports is due to a revision in the useful life of buildings slated for demolition.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q1 FY26: 3.39
- Revenue (₹ Cr), Q2 FY26: 3.39
- Revenue (₹ Cr), Q3 FY26: 3.4
- Revenue (₹ Cr), Q4 FY26: 3.59
- Revenue (₹ Cr), Q1 FY27: 3.86
- Profit (₹ Cr), Q1 FY26: 4.44
- Profit (₹ Cr), Q2 FY26: 1.86
- Profit (₹ Cr), Q3 FY26: 3.62
- Profit (₹ Cr), Q4 FY26: -7.21
- Profit (₹ Cr), Q1 FY27: 3.43
Revenue (₹ Cr)
- Revenue (₹ Cr), Q1 FY26: 3.39
- Revenue (₹ Cr), Q2 FY26: 3.39
- Revenue (₹ Cr), Q3 FY26: 3.4
- Revenue (₹ Cr), Q4 FY26: 3.59
- Revenue (₹ Cr), Q1 FY27: 3.86
Profit (₹ Cr)
- Profit (₹ Cr), Q1 FY26: 4.44
- Profit (₹ Cr), Q2 FY26: 1.86
- Profit (₹ Cr), Q3 FY26: 3.62
- Profit (₹ Cr), Q4 FY26: -7.21
- Profit (₹ Cr), Q1 FY27: 3.43
| Metric | CurrentQ1 FY27 | PreviousQ4 FY26 | Same quarter LYQ1 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 3.86YoY +14% | 3.59 | 3.39 |
| Profit (₹ Cr) | 3.43YoY -23% | -7.21 | 4.44 |
The Accounting Behind the Squeeze
The profit drop was not from weak operations but an accounting shift. According to Scanx.trade, the company accelerated depreciation on buildings proposed for demolition as part of a redevelopment plan. This one-time, non-cash charge of ₹3.73 crore constituted nearly 70% of total expenses.
It masked what was otherwise a stable quarter. Operating revenue grew, and other income provided a significant boost of ₹5.02 crore. Flashfinance.news notes this other income accounted for over 56% of total income, highlighting the still-heavy reliance on non-operating streams post the IT demerger.
A Quiet Phase of Transition
Management's focus, as per a StockFin.ai analysis, is squarely on the long-term redevelopment of its Hyderabad property and stakeholder engagement. The report states there is no active development pipeline beyond this single asset, with the strategic focus on “asset optimization rather than expansion.”
Live Chart
· MADALA
(BSE)
ISIN: INE002B01016
The balance sheet remains a source of stability with zero debt and a strong current ratio. This provides a cushion as the company enters what StockFin.ai calls a “quiet phase,” where near-term earnings are suppressed by redevelopment planning.
Key Points
- Revenue growth remained steady at 14% YoY, but net profit declined 23% due to a massive, non-cash depreciation charge.
- The depreciation surge is linked to an accounting revision for buildings to be demolished, a precursor to the key Hyderabad property redevelopment.
- Management commentary emphasizes long-term asset optimization through this redevelopment, with no near-term expansion plans.
- The company maintains a debt-free balance sheet, providing financial flexibility during this transitional period.
Hexa Perspective
The quarter underscores Madala's identity as a story stock, where current earnings are a poor proxy for value. The heavy depreciation is a front-loaded cost for a future redevelopment that lacks a public timeline or specific financial targets.
Investors are effectively funding a call option on the Hyderabad project's execution. The debt-free balance sheet and stable rental income provide a floor, but the 150% premium to the industry P/E, as per the valuation data, prices in significant future success that remains unproven. The next few quarters will be about monitoring cash flow and any concrete steps on the redevelopment, as operating profits will likely remain under pressure.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.