KSH International (KSHINTL) Q2 FY27's 85% Revenue Surge Meets a Soaring Interest Bill
The winding wire maker's sales more than doubled year-on-year, but a 140% jump in interest expense held back profit growth and squeezed margins.
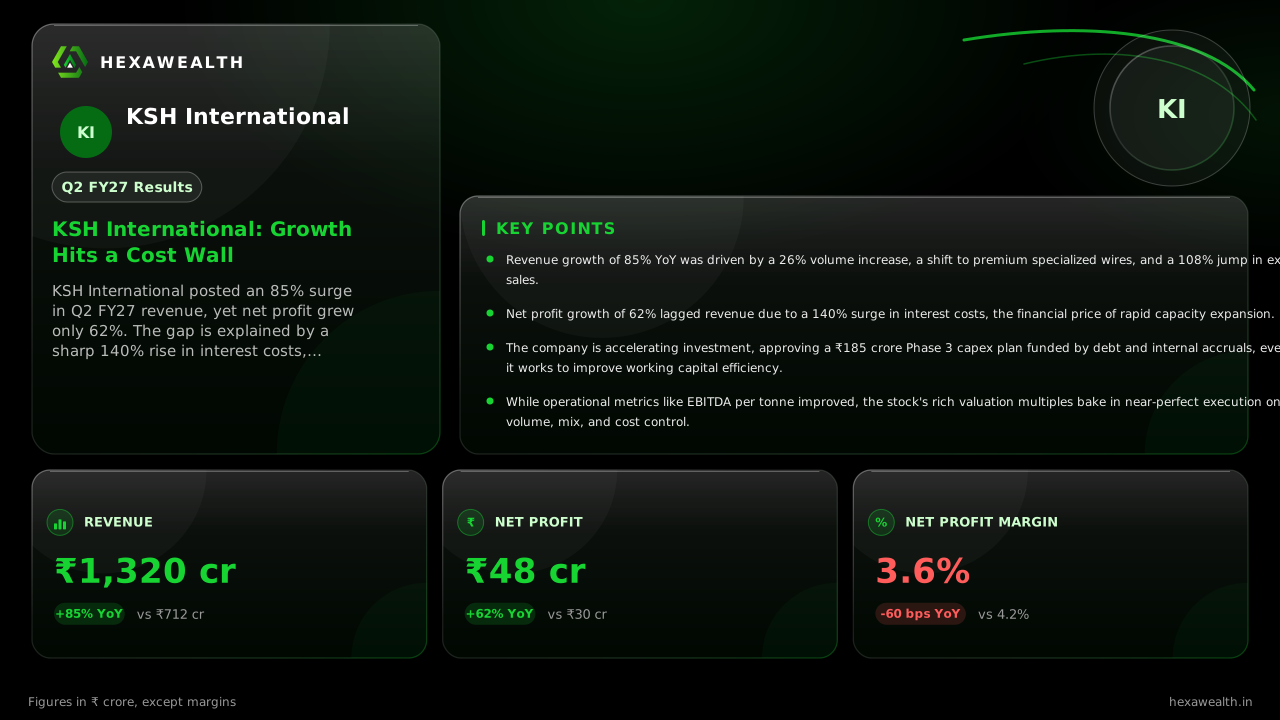
KSH International posted an 85% surge in Q2 FY27 revenue, yet net profit grew only 62%. The gap is explained by a sharp 140% rise in interest costs, reflecting the price of funding rapid expansion in a booming power infrastructure market.
For manufacturers feeding India's power infrastructure boom, growth is not a question of demand but of capacity and capital. KSH International's September quarter shows what happens when both are stretched at once: sales more than doubled, but the cost of funding that surge ate deeply into the rewards.
The company posted revenue of ₹1,319.7 crore, up 85% from a year ago and 13% sequentially. Net profit reached ₹48.0 crore, a 62% yearly gain. The five-quarter trend reveals a business scaling rapidly, with revenue nearly doubling since Q2 FY26.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 712.15
- Revenue (₹ Cr), Q3 FY26: 817.77
- Revenue (₹ Cr), Q4 FY26: 1,018.34
- Revenue (₹ Cr), Q1 FY27: 1,164.23
- Revenue (₹ Cr), Q2 FY27: 1,319.65
- Profit (₹ Cr), Q2 FY26: 29.59
- Profit (₹ Cr), Q3 FY26: 23.33
- Profit (₹ Cr), Q4 FY26: 34.53
- Profit (₹ Cr), Q1 FY27: 42.22
- Profit (₹ Cr), Q2 FY27: 47.95
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 712.15
- Revenue (₹ Cr), Q3 FY26: 817.77
- Revenue (₹ Cr), Q4 FY26: 1,018.34
- Revenue (₹ Cr), Q1 FY27: 1,164.23
- Revenue (₹ Cr), Q2 FY27: 1,319.65
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26: 29.59
- Profit (₹ Cr), Q3 FY26: 23.33
- Profit (₹ Cr), Q4 FY26: 34.53
- Profit (₹ Cr), Q1 FY27: 42.22
- Profit (₹ Cr), Q2 FY27: 47.95
Net Profit Margin
- Net Profit Margin, Q2 FY26: 4.2%
- Net Profit Margin, Q3 FY26: 2.9%
- Net Profit Margin, Q4 FY26: 3.4%
- Net Profit Margin, Q1 FY27: 3.6%
- Net Profit Margin, Q2 FY27: 3.6%
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 1,319.65YoY +85% | 1,164.23 | 712.15 |
| Profit (₹ Cr) | 47.95YoY +62% | 42.22 | 29.59 |
| Net Profit Margin | 3.6%YoY -14% | 3.6% | 4.2% |
Why profit trailed the sales boom
Operating performance was strong, driven by a 26% jump in sales volume and a richer product mix. According to the company's investor presentation, specialized wires now make up 74% of revenue, and exports surged 108%. This lifted EBITDA per tonne by 55% year-on-year, as reported by Equitybulls.
Yet the net profit margin fell 60 basis points from last year. The primary drag was a 140% year-on-year surge in interest expense to ₹22.25 crore. MarketsMojo notes this reflects the cost of an aggressive expansion strategy, with debt funding both working capital and new capacity.
The expansion engine and its fuel
Management is pushing capacity hard to meet what it calls a “structural growth phase” for winding wires. The Phase 2 expansion at its Supa facility was completed six months early, taking available capacity to 57,845 MT. Utilization improved to 76%.
Live Chart
· KSHINTL
(BSE)
ISIN: INE987S01020
Simultaneously, the board approved a new ₹185 crore Phase 3 expansion, targeting 72,200 MT of capacity by Q1 FY2029. The company told Multibagg.ai this will be funded by internal accruals and long-term debt. While total debt fell sequentially to ₹341.3 crore, the interest run-rate suggests financing costs will remain a heavy load.
A market reading the fine print
The stock jumped over 9% on the results day, as MarketsMojo reported, celebrating the top-line beat. Yet analyst notes strike a cautious chord on valuation and execution. A Flash Finance analysis called it a “Strong Candidate” but flagged an elevated trailing P/E multiple above 40x, leaving little room for error given the high interest burden and working capital intensity.
The company's own margin commentary, cited by Arthneeti, advises looking past percentage margins. It argues that with copper costs fully passed through, the stable measure is EBITDA per tonne—which did rise sharply—not the margin percentage depressed by a higher revenue denominator.
Key Points
- Revenue growth of 85% YoY was driven by a 26% volume increase, a shift to premium specialized wires, and a 108% jump in export sales.
- Net profit growth of 62% lagged revenue due to a 140% surge in interest costs, the financial price of rapid capacity expansion.
- The company is accelerating investment, approving a ₹185 crore Phase 3 capex plan funded by debt and internal accruals, even as it works to improve working capital efficiency.
- While operational metrics like EBITDA per tonne improved, the stock's rich valuation multiples bake in near-perfect execution on volume, mix, and cost control.
Hexa Perspective
KSH International is riding a powerful, credible demand wave from grid upgrades and renewable energy. The quarter confirms its ability to win orders and improve real operating profitability per unit sold.
The tension is between that operating leverage and the financial leverage needed to build capacity ahead of demand. If volume growth and the premium product mix hold, the interest burden becomes a manageable cost of scaling. A stumble on either, or a tightening of credit, would make that debt load the story. For now, the market is betting the growth pays for itself.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.