Krowniq (KROWNIQ) Q2 FY27 Profit Crashes 79% as Core Business Turns Loss-Making
The FMCG exporter's Q2 FY27 saw a sharp drop in revenue and a collapse in operating margin, with profit saved only by other income.
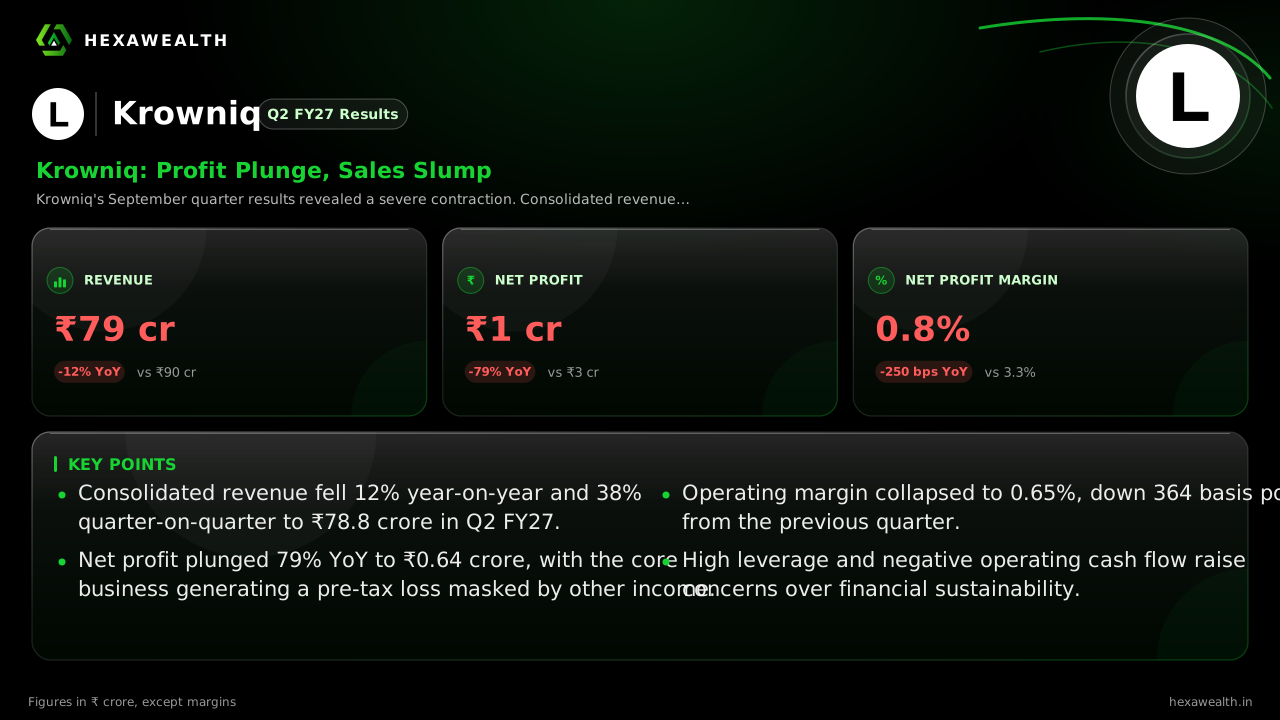
Krowniq's September quarter results revealed a severe contraction. Consolidated revenue fell 12% YoY and 38% QoQ, while net profit plunged 79%. The core business generated a pre-tax loss, masked by other income.
For an FMCG exporter like Krowniq, growth hinges on steady international orders and stable margins. The September quarter delivered the opposite, with revenue falling to a multi-quarter low and profitability evaporating.
Revenue dropped to ₹78.8 crore, down 12% from a year ago and 38% from the previous quarter. Net profit collapsed to ₹0.64 crore, a 79% YoY decline. The net profit margin shrank to just 0.8%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 89.58
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 90.61
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 145.4
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 126.68
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 78.8
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 3.0
- Profit (₹ Cr), Q3 FY26 (Dec 2025): 1.98
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 1.95
- Profit (₹ Cr), Q1 FY27 (Jun 2026): 3.89
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 0.64
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 89.58
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 90.61
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 145.4
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 126.68
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 78.8
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 3.0
- Profit (₹ Cr), Q3 FY26 (Dec 2025): 1.98
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 1.95
- Profit (₹ Cr), Q1 FY27 (Jun 2026): 3.89
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 0.64
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 78.8 | 126.68 |
| Profit (₹ Cr) | 0.64 | 3.89 |
| PAT Margin (%) | 0.8 | 3.1 |
The Core Business Turned Loss-Making
The headline profit was propped up entirely by other income. According to MarketsMojo, other income of ₹1.93 crore constituted 232% of the pre-tax profit. Without this cushion, the core operations would have reported a pre-tax loss of ₹1.10 crore. Operating profit before other income fell 86% sequentially to just ₹0.51 crore.
Why Margins Collapsed
A sharp drop in sales volume was the primary driver, with revenue falling to its lowest level in the last five quarters. This collapse in topline meant fixed costs like employee expenses consumed a larger share of revenue. Interest costs also jumped 92% year-on-year, pressuring profits further. The company had previously flagged that the Middle East conflict was increasing freight costs and causing shipment delays.
A Precarious Financial Position
Analyst scepticism centres on the company's weak financial buffers. MarketsMojo notes operating cash flow was deeply negative in FY26 due to severe working capital stress. The debt-to-equity ratio stands at 1.67, and the interest coverage ratio from operations fell to a concerning 0.43 times this quarter. This raises questions about the firm's ability to service debt from its core, currently loss-making, business.
Live Chart
· KROWNIQ
(BSE)
ISIN: INE624M01014
The market reaction was swift, with the stock falling 7.4% on the results day. Research firm MarketsMoji issued a 'Sell' rating, citing an unsustainable profit structure and fundamental deterioration. It estimates a fair value 19% below the current price.
Key Points
- Consolidated revenue fell 12% year-on-year and 38% quarter-on-quarter to ₹78.8 crore in Q2 FY27.
- Net profit plunged 79% YoY to ₹0.64 crore, with the core business generating a pre-tax loss masked by other income.
- Operating margin collapsed to 0.65%, down 364 basis points from the previous quarter.
- High leverage and negative operating cash flow raise concerns over financial sustainability.
Hexa Perspective
The quarter reveals a business under severe operational stress, not just a cyclical dip. The dependency on other income to report a profit is a clear red flag, indicating the core export trading model is currently unviable.
Recovery hinges on a swift rebound in sales volumes to absorb high fixed and financing costs. Until revenue stabilises consistently above ₹100 crore and operating margins recover without non-operating support, the risk of further earnings disappointment and balance sheet strain remains high. The valuation discount to the industry reflects these genuine quality concerns.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.