JOJO's Profit Halves Despite a 224% Revenue Surge in Q2 FY27
The event and media company's revenue tripled year-on-year, but a sharp rise in expenses caused net profit to drop nearly 50% sequentially.
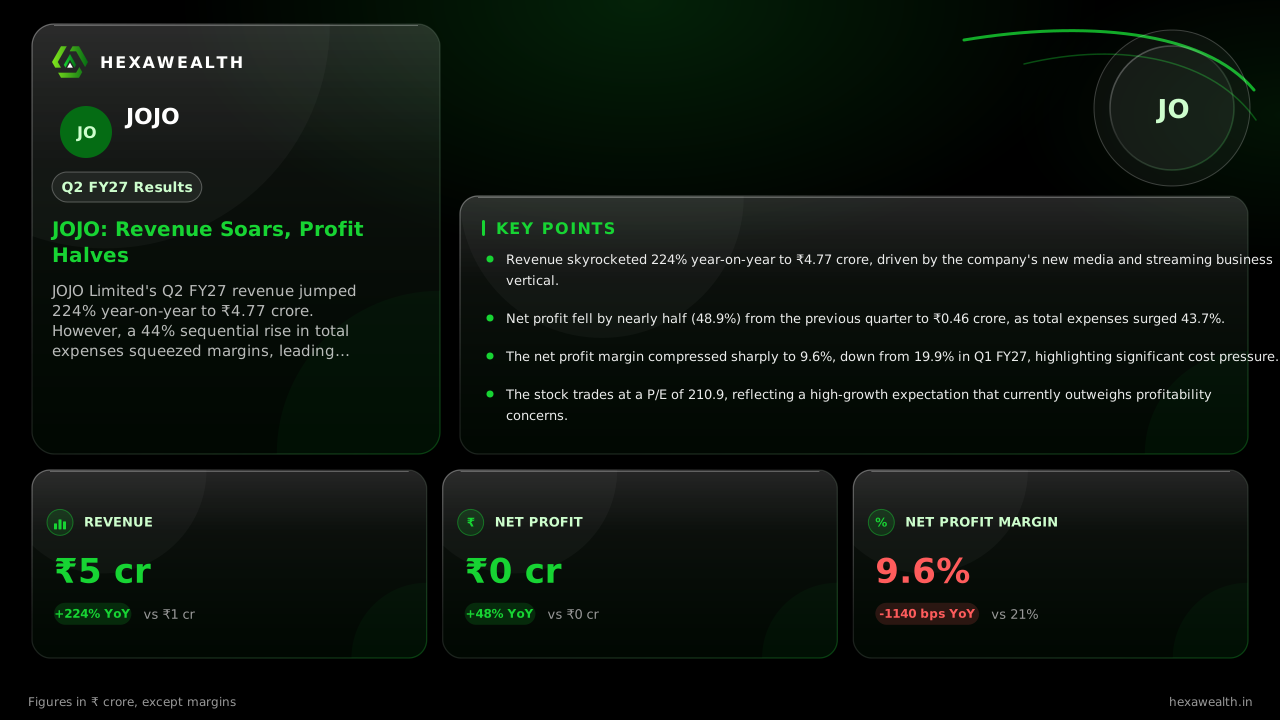
JOJO Limited's Q2 FY27 revenue jumped 224% year-on-year to ₹4.77 crore. However, a 44% sequential rise in total expenses squeezed margins, leading to a 49% quarterly drop in net profit to ₹0.46 crore.
JOJO Limited’s pivot to media and entertainment delivered a staggering top-line jump this quarter, but the cost of that growth bit deeply into profitability. Revenue more than tripled from a low base, yet the company’s net profit margin collapsed as expenses surged faster than sales.
The numbers tell a story of two diverging trends. Revenue climbed to ₹4.77 crore, up 224% from a year ago and 5.5% from the previous quarter. Profit, however, fell sharply to ₹0.46 crore, down 48.9% sequentially even as it rose 48.4% year-on-year. The net profit margin contracted by over 10 percentage points to just 9.6%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 1.47
- Revenue (₹ Cr), Q3 FY26: 8.15
- Revenue (₹ Cr), Q4 FY26: 12.60
- Revenue (₹ Cr), Q1 FY27: 4.52
- Revenue (₹ Cr), Q2 FY27: 4.77
- Profit (₹ Cr), Q2 FY26: 0.31
- Profit (₹ Cr), Q3 FY26: 1.02
- Profit (₹ Cr), Q4 FY26: 4.79
- Profit (₹ Cr), Q1 FY27: 0.90
- Profit (₹ Cr), Q2 FY27: 0.46
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 1.47
- Revenue (₹ Cr), Q3 FY26: 8.15
- Revenue (₹ Cr), Q4 FY26: 12.60
- Revenue (₹ Cr), Q1 FY27: 4.52
- Revenue (₹ Cr), Q2 FY27: 4.77
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26: 0.31
- Profit (₹ Cr), Q3 FY26: 1.02
- Profit (₹ Cr), Q4 FY26: 4.79
- Profit (₹ Cr), Q1 FY27: 0.90
- Profit (₹ Cr), Q2 FY27: 0.46
Net Profit Margin
- Net Profit Margin, Q2 FY26: 21.0%
- Net Profit Margin, Q3 FY26: 12.5%
- Net Profit Margin, Q4 FY26: 38.0%
- Net Profit Margin, Q1 FY27: 19.9%
- Net Profit Margin, Q2 FY27: 9.6%
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 4.77YoY +224% | 4.52 | 1.47 |
| Profit (₹ Cr) | 0.46YoY +48% | 0.90 | 0.31 |
| Net Profit Margin | 9.6%YoY -54% | 19.9% | 21.0% |
Where the Revenue Surge Came From
The explosive year-on-year growth stems from the company’s strategic shift. JOJO acquired a media streaming and production vertical in March 2026, rebranding from Madhuveer Com 18 Network. This new business drove the revenue leap from a modest ₹1.47 crore in Q2 FY26. Recent expansions, like launching JOJO TV on Samsung TV Plus and JioFastTV, aim to build on this digital pivot.
The Cost Squeeze That Followed
Growth came at a high price. Total expenses ballooned by 43.7% quarter-on-quarter to ₹4.38 crore. This surge dramatically outpaced the 5.5% revenue growth, eroding margins. The increase follows the integration of the new media vertical, which likely carries higher operating and content costs. Depreciation also rose 71.4% year-on-year, reflecting investments in this digital infrastructure.
A Valuation Built on Promise
The market prices JOJO for its future potential, not current earnings. With a P/E of 210.9, it trades at a massive 757% premium to the industry, as reported by HexaWealth. This valuation hinges on the success of its digital distribution deals and its ability to eventually convert top-line growth into sustained profit.
Live Chart
· JOJO
(BSE)
ISIN: INE312M01024
Key Points
- Revenue skyrocketed 224% year-on-year to ₹4.77 crore, driven by the company's new media and streaming business vertical.
- Net profit fell by nearly half (48.9%) from the previous quarter to ₹0.46 crore, as total expenses surged 43.7%.
- The net profit margin compressed sharply to 9.6%, down from 19.9% in Q1 FY27, highlighting significant cost pressure.
- The stock trades at a P/E of 210.9, reflecting a high-growth expectation that currently outweighs profitability concerns.
Hexa Perspective
The quarter underscores the classic growth-investment trade-off. JOJO is successfully scaling its revenue base through digital expansion, but profitability is being sacrificed to fund that growth. The path to justifying its lofty valuation now depends on achieving operating leverage. Investors are betting that the current cost surge is a temporary phase of investment, not a permanent feature of the new business model. The next few quarters will be critical to see if expenses stabilize as the new verticals mature.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.