Indus Infra Trust (INDUSINVIT) Q2 FY27 Profit Triples as Acquisitions Supercharge Revenue
The InvIT's profit surged 253% year-on-year to ₹210 crore, driven by a significantly expanded portfolio of operational road assets.
Indus Infra Trust reported a massive 253% YoY jump in Q2 FY27 net profit to ₹210 crore. The growth was fueled by recent acquisitions of highway SPVs, which more than tripled revenue. The trust maintained its distribution guidance of ₹14 per unit for the year.
For an infrastructure investment trust, growth is measured by the steady expansion of its operational asset base. Indus Infra Trust delivered exactly that in the September quarter, with recent acquisitions of highway projects translating directly into a surge in cash flows.
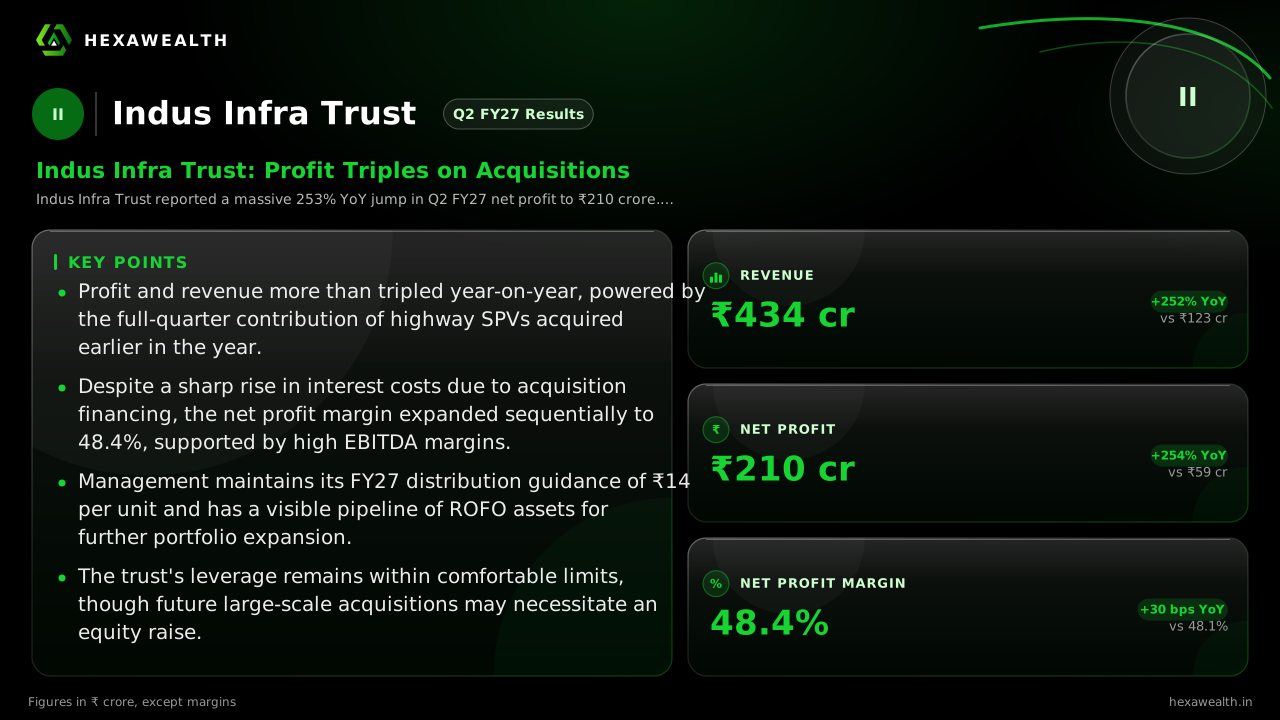
The numbers tell a story of inorganic growth. Revenue from operations jumped 252% year-on-year to ₹434 crore, while net profit rose 253% to ₹210 crore. Sequentially, both revenue and profit grew over 50%, highlighting the immediate contribution of new assets.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 434.0YoY +252% | 284.8 | 123.4 |
| Profit (₹ Cr) | 210.0YoY +254% | 129.4 | 59.4 |
| Net Profit Margin | 48.4%YoY +0.6% | 45.4% | 48.1% |
The acquisition engine behind the surge
The leap in scale came from integrating new road assets. According to the investor presentation, the trust now owns 17 operational Hybrid Annuity Model (HAM) projects, up from 13 earlier. The Q2 performance included a full quarter's contribution from assets like KNR Palani and ULCCS Kasaragod Expressway, acquired in June.
Management, in an earnings call covered by Investing.com, said the trust also completed the acquisition of KNR Guruvayur during the quarter. These additions have dramatically expanded the annuity and toll collection base, which is backed by long-term contracts with the National Highways Authority of India.
Why margins held firm despite rising costs
A 232% year-on-year spike in interest expense, to ₹127 crore, was the direct cost of funding this growth. The trust's CFO explained on the call that this was due to additional debt taken to refinance acquired projects. Yet, the net profit margin still improved 300 basis points from the previous quarter to 48.4%.
The margin resilience came from the high-operating leverage of the new assets. As reported by ScanX, the EBITDA margin for the quarter was a robust 78.47%. The revenue from these government-backed annuities is highly predictable, allowing profit to scale even as financing costs rise.
The path ahead: More deals, steady payouts
The growth story is set to continue. Management is targeting 5-6 more asset acquisitions under its Right of First Offer (ROFO) agreement in the coming quarter, with a projected enterprise value of about ₹4,700 crore. It reaffirmed its annual distribution per unit (DPU) guidance of ₹14 for FY27, approving a Q2 payout of ₹3.55.
With leverage around 47% against a self-imposed ceiling of 65%, the trust has room for more debt-funded deals. However, CEO Amit Kumar Singh noted on the call that a capital raise would be considered once leverage approaches 60-61%, ensuring the acquisition spree remains sustainable.
Key Points
- Profit and revenue more than tripled year-on-year, powered by the full-quarter contribution of highway SPVs acquired earlier in the year.
- Despite a sharp rise in interest costs due to acquisition financing, the net profit margin expanded sequentially to 48.4%, supported by high EBITDA margins.
- Management maintains its FY27 distribution guidance of ₹14 per unit and has a visible pipeline of ROFO assets for further portfolio expansion.
- The trust's leverage remains within comfortable limits, though future large-scale acquisitions may necessitate an equity raise.
Hexa Perspective
The quarter confirms Indus Infra Trust's model: acquire operational road assets, integrate them swiftly, and watch annuity income flow to the bottom line. The 300-basis-point sequential margin expansion, even with higher interest costs, shows the model's inherent operating leverage.
The critical test is execution on the promised pipeline. Successfully onboarding the next ₹4,700 crore of ROFO assets will be key to sustaining this growth rate and the ₹14 DPU guidance. Investors are betting on management's ability to replicate this quarter's acquisition success while managing a gradually rising cost of capital.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.