GLEN Industries Q4 FY26 Profit Slips 20% Despite Strong Revenue Growth
The packaging firm's Q4 FY26 sales jumped 24%, but a sharp rise in raw material costs squeezed margins, leading to a profit decline.
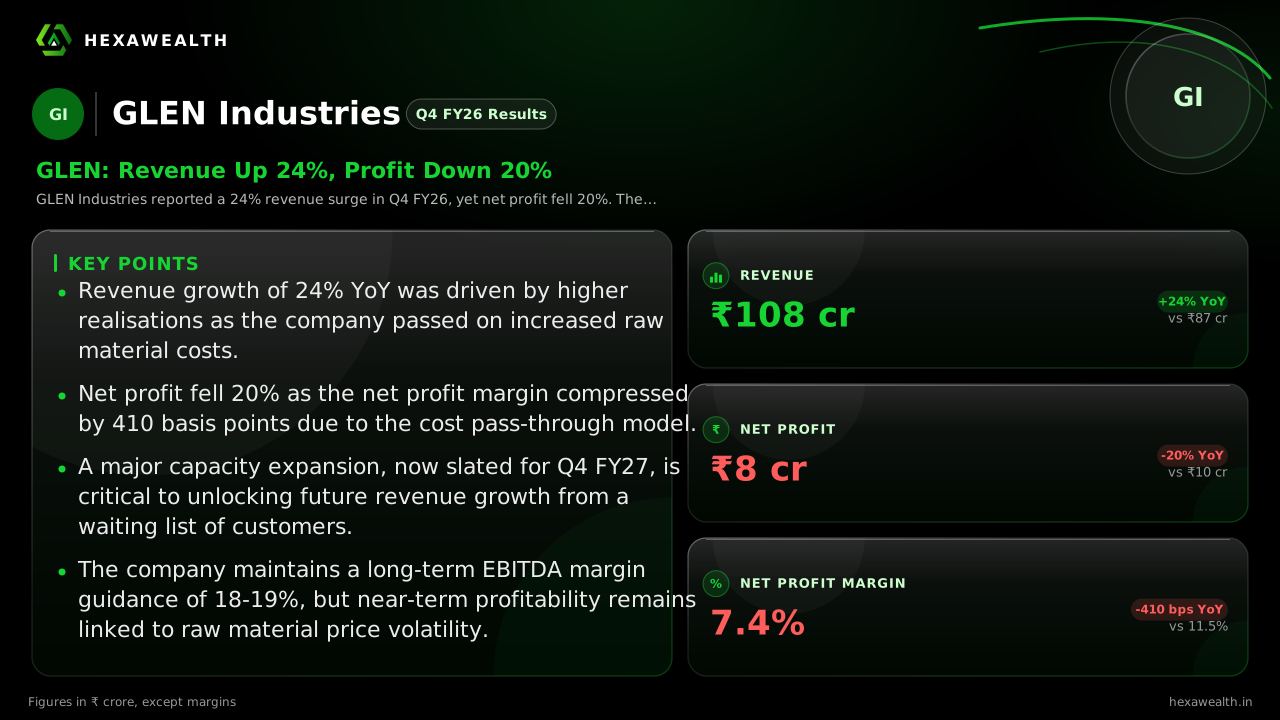
GLEN Industries reported a 24% revenue surge in Q4 FY26, yet net profit fell 20%. The margin squeeze was driven by higher raw material costs, while a major capacity expansion is set to fuel future growth.
For a packaging company running at full capacity, the story is usually about demand. GLEN Industries’ March quarter delivered that, with revenue up 24% year-on-year. Yet the bottom line told a different tale, as profit fell 20% in a clear sign that costs won the quarter.
The numbers show the tension. Revenue hit ₹108 crore, up from ₹87 crore a year ago. Profit, however, slid to ₹8 crore from ₹10 crore. The net profit margin compressed by 410 basis points to 7.4%, a level last seen in the September 2024 quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Jun 2024: 43.7
- Revenue (₹ Cr), Sep 2024: 84.0
- Revenue (₹ Cr), Mar 2025: 87.0
- Revenue (₹ Cr), Sep 2025: 96.0
- Revenue (₹ Cr), Mar 2026: 108.0
- Profit (₹ Cr), Jun 2024: 5.2
- Profit (₹ Cr), Sep 2024: 8.0
- Profit (₹ Cr), Mar 2025: 10.0
- Profit (₹ Cr), Sep 2025: 8.0
- Profit (₹ Cr), Mar 2026: 8.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Jun 2024: 43.7
- Revenue (₹ Cr), Sep 2024: 84.0
- Revenue (₹ Cr), Mar 2025: 87.0
- Revenue (₹ Cr), Sep 2025: 96.0
- Revenue (₹ Cr), Mar 2026: 108.0
Profit (₹ Cr)
- Profit (₹ Cr), Jun 2024: 5.2
- Profit (₹ Cr), Sep 2024: 8.0
- Profit (₹ Cr), Mar 2025: 10.0
- Profit (₹ Cr), Sep 2025: 8.0
- Profit (₹ Cr), Mar 2026: 8.0
Net Profit Margin (%)
- Net Profit Margin (%), Jun 2024: 12.0
- Net Profit Margin (%), Sep 2024: 9.5
- Net Profit Margin (%), Mar 2025: 11.5
- Net Profit Margin (%), Sep 2025: 8.3
- Net Profit Margin (%), Mar 2026: 7.4
| Metric | CurrentMar 2026 | PreviousSep 2025 |
|---|---|---|
| Revenue (₹ Cr) | 108.0 | 96.0 |
| Profit (₹ Cr) | 8.0 | 8.0 |
| Net Profit Margin (%) | 7.4 | 8.3 |
Why the top line did not reach the bottom
A 34% surge in total expenses year-on-year was the culprit. According to reports from Arthneeti and Newboard, the company passes raw material price changes directly to customers, protecting its absolute rupee margin per unit. This quarter, higher polymer prices boosted revenue but compressed the percentage margin, explaining the divergence.
The expansion that will decide the next year
Capacity is the current bottleneck. Management, in its Q4 earnings call cited by Arthneeti, said the existing plant is near full and has not added a new export customer in years. The solution is a ₹100 crore-plus expansion, now delayed to Q4 FY27. It is expected to add ₹100-125 crore to FY27 revenue.
This growth comes at a cost. The company’s working capital swelled by ₹44 crore in FY26, largely due to building inventory as a buffer against supply chain risks. Operating cash flow improved, but the balance sheet is funding a major build-out.
Live Chart
· GLEN
(BSE)
ISIN: INE0UMC01019
A valuation gap and institutional view
The stock trades at a P/E of 15.4, a 29% discount to the industry average. This likely reflects the near-term margin pressure. Institutional sentiment has been cautious, with DII stake decreasing by 9.5% between March and September 2026, as per Upstox data.
Key Points
- Revenue growth of 24% YoY was driven by higher realisations as the company passed on increased raw material costs.
- Net profit fell 20% as the net profit margin compressed by 410 basis points due to the cost pass-through model.
- A major capacity expansion, now slated for Q4 FY27, is critical to unlocking future revenue growth from a waiting list of customers.
- The company maintains a long-term EBITDA margin guidance of 18-19%, but near-term profitability remains linked to raw material price volatility.
Hexa Perspective
The quarter frames GLEN’s transition phase. Strong demand is evident, but profitability is hostage to input costs the business chooses not to absorb. The coming year’s story hinges entirely on the new plant’s timely commissioning and smooth ramp-up. If execution stays on track, the revenue guidance of ₹100-125 crore from new capacity could restore earnings momentum by FY28. Until then, the stock’s discount to peers prices in the execution risk and the margin squeeze that has at least another quarter to run.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.