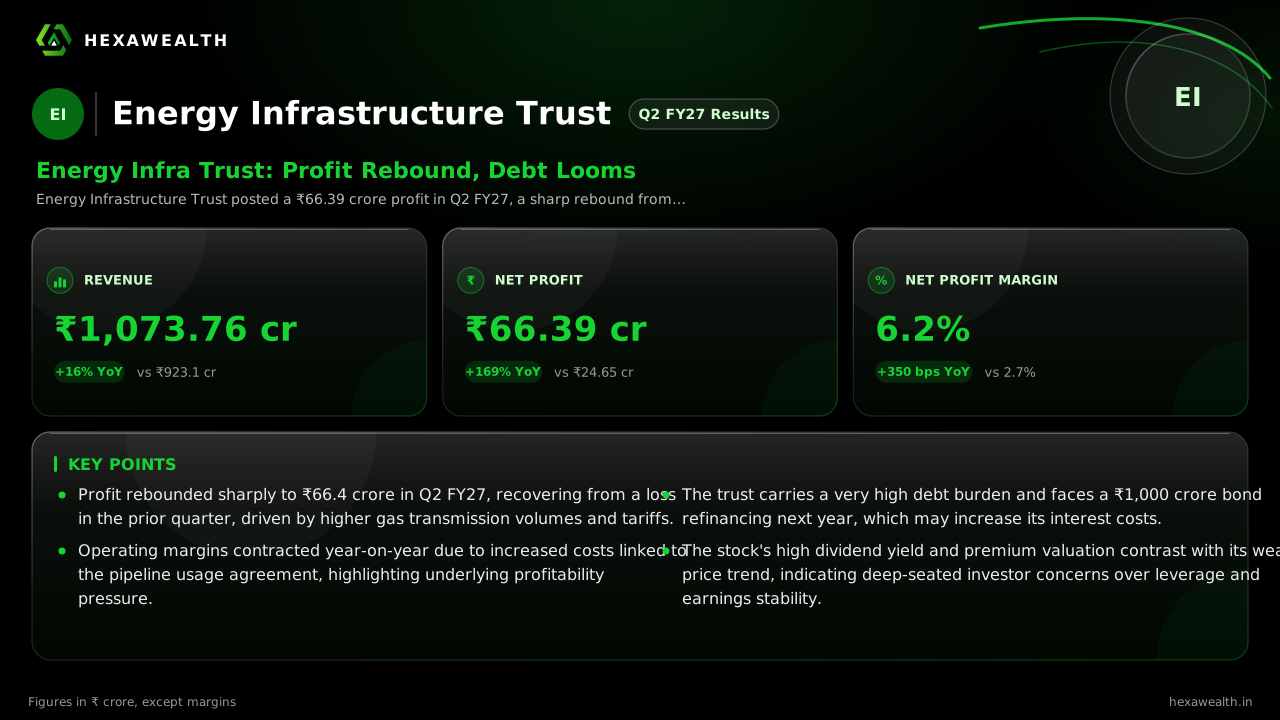
Energy Infrastructure Trust (ENERGYINF) Q2 FY27 Profit Jumps 169% Despite Margin Pressure
The gas pipeline InvIT swung to a ₹66 crore profit in Q2 FY27, but higher costs and a heavy debt burden cast a shadow over the recovery.
Energy Infrastructure Trust posted a ₹66.39 crore profit in Q2 FY27, a sharp rebound from last quarter's loss. Revenue grew 16% yearly, but margins compressed as costs rose and a major debt refinancing looms.
For a pipeline infrastructure trust, stability of cash flows is the bedrock. Energy Infrastructure Trust's September quarter delivered a dramatic profit swing, but the underlying cost structure tells a more complex story of pressure beneath the headline growth.
The trust reported a consolidated net profit of ₹66.39 crore for Q2 FY27, a 169% jump from the year-ago period. This marked a sharp recovery from the ₹6.55 crore loss in the June quarter. Revenue reached ₹1,073.76 crore, up 16.3% year-on-year but down 2% sequentially.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 923.10
- Revenue (₹ Cr), Q3 FY26: 952.39
- Revenue (₹ Cr), Q4 FY26: 1,001.79
- Revenue (₹ Cr), Q1 FY27: 1,095.12
- Revenue (₹ Cr), Q2 FY27: 1,073.76
- Net Profit (₹ Cr), Q2 FY26: 24.65
- Net Profit (₹ Cr), Q3 FY26: 13.93
- Net Profit (₹ Cr), Q4 FY26: 47.68
- Net Profit (₹ Cr), Q1 FY27: -6.55
- Net Profit (₹ Cr), Q2 FY27: 66.39
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 923.10
- Revenue (₹ Cr), Q3 FY26: 952.39
- Revenue (₹ Cr), Q4 FY26: 1,001.79
- Revenue (₹ Cr), Q1 FY27: 1,095.12
- Revenue (₹ Cr), Q2 FY27: 1,073.76
Net Profit (₹ Cr)
- Net Profit (₹ Cr), Q2 FY26: 24.65
- Net Profit (₹ Cr), Q3 FY26: 13.93
- Net Profit (₹ Cr), Q4 FY26: 47.68
- Net Profit (₹ Cr), Q1 FY27: -6.55
- Net Profit (₹ Cr), Q2 FY27: 66.39
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 1,073.76YoY +16% | 1,095.12 | 923.10 |
| Net Profit (₹ Cr) | 66.39YoY +169% | -6.55 | 24.65 |
| PAT Margin (%) | 6.2YoY +130% | -0.6 | 2.7 |
Why profits swung back
The profit rebound was driven by its core gas transmission business. According to an investor call transcript cited by mcapital.in, volumes averaged 37.48 MMSCMD in the first half, up about 9% year-on-year, aided by a record single-day high in July. The realized tariff also rose to ₹82.9 per MMBTU after a regulatory increase.
However, this operational strength was offset by rising costs. MarketsMojo reported the operating margin compressed to 38.53% from 40.75% a year ago. Higher 'PUA upside' expenses, payments linked to the pipeline usage agreement, pressured profitability.
The leverage overhang
A towering debt burden remains the trust's most significant constraint. The payload shows a debt-to-equity ratio of 13.32, but other analyses paint a starker picture. MarketsMojo cited a net debt-to-equity ratio of 10.80 times, calling the leverage 'unsustainable.'
Live Chart
· ENERGYINF
(BSE)
ISIN: INE05KD23015
Management is actively addressing a near-term maturity. The trust plans to refinance ₹1,000 crore of bonds due in March 2027. Scanx.trade noted this could come with a potential cost increase of 20-30 basis points.
Market skepticism persists
Despite the profit recovery, the stock fell 2% on the results day, per a MarketsMojo alert. The shares have declined 23% over the past year, significantly underperforming the market. This suggests investors are weighing the high yield against structural risks.
The trust's valuation reflects this tension. It trades at a P/E of 55.8, a 130% premium to the industry average, largely supported by its massive 22.76% dividend yield. This premium exists alongside clear concerns about earnings volatility and leverage.
Key Points
- Profit rebounded sharply to ₹66.4 crore in Q2 FY27, recovering from a loss in the prior quarter, driven by higher gas transmission volumes and tariffs.
- Operating margins contracted year-on-year due to increased costs linked to the pipeline usage agreement, highlighting underlying profitability pressure.
- The trust carries a very high debt burden and faces a ₹1,000 crore bond refinancing next year, which may increase its interest costs.
- The stock's high dividend yield and premium valuation contrast with its weak price trend, indicating deep-seated investor concerns over leverage and earnings stability.
Hexa Perspective
The quarter confirms the core pipeline asset generates robust cash flow, supporting the trust's high distribution policy. The volume and tariff growth are tangible positives. Yet, the margin squeeze shows limited pricing power against contracted costs.
The story for the next year hinges on the refinancing. Successfully rolling over the March 2027 debt at a manageable cost is critical to preserving distributable cash flows. Until the leverage is visibly reduced, the stock's high yield will likely remain a beacon for income-seekers but a red flag for those assessing balance sheet risk. The market is pricing in the uncertainty, not the recovery.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.