Emmforce Autotech (EMMFORCE) Q2 FY27 Profit Rises 50% as Revenue Surges 70%
The auto parts exporter's quarterly revenue hit a record ₹92 crore, but higher costs and interest expenses kept a lid on profitability.
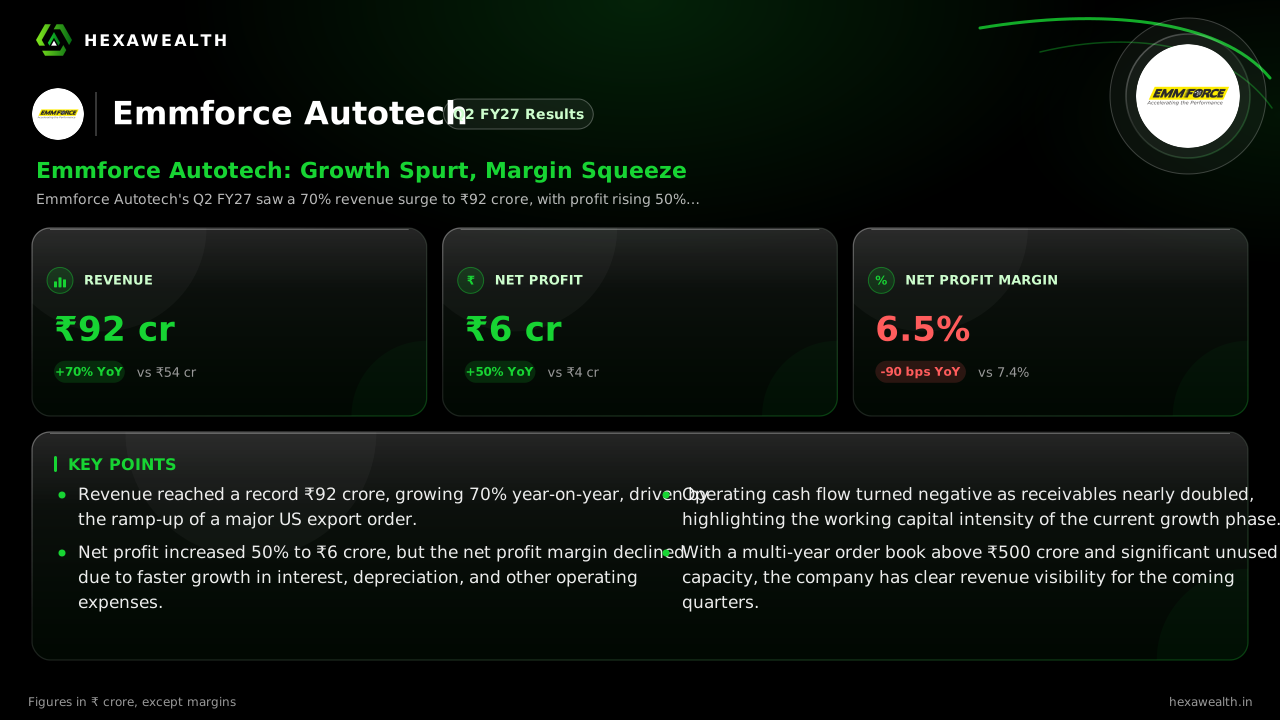
Emmforce Autotech's Q2 FY27 saw a 70% revenue surge to ₹92 crore, with profit rising 50% to ₹6 crore. However, net profit margin fell as costs and interest expenses grew faster than sales.
For Emmforce Autotech, a niche exporter of drivetrain parts, the September quarter was about proving it could deliver on a massive order book. The test was passed on the top line, but the cost of that growth is now showing up in the financials.
The company posted revenue of ₹92 crore, a 70% jump from a year ago and a 56% leap from the previous quarter. Profit followed, rising 50% year-on-year to ₹6 crore. Yet the net profit margin slipped to 6.5%, down 90 basis points from last year, as expenses grew even faster.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25 (Sep 2024): 35.0
- Revenue (₹ Cr), Q4 FY25 (Mar 2025): 52.0
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 54.0
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 59.0
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 92.0
- Profit (₹ Cr), Q2 FY25 (Sep 2024): 3.0
- Profit (₹ Cr), Q4 FY25 (Mar 2025): 5.0
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 4.0
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 4.0
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 6.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25 (Sep 2024): 35.0
- Revenue (₹ Cr), Q4 FY25 (Mar 2025): 52.0
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 54.0
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 59.0
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 92.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25 (Sep 2024): 3.0
- Profit (₹ Cr), Q4 FY25 (Mar 2025): 5.0
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 4.0
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 4.0
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 6.0
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY25 (Sep 2024): 8.6
- Net Profit Margin (%), Q4 FY25 (Mar 2025): 9.6
- Net Profit Margin (%), Q2 FY26 (Sep 2025): 7.4
- Net Profit Margin (%), Q4 FY26 (Mar 2026): 6.8
- Net Profit Margin (%), Q2 FY27 (Sep 2026): 6.5
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ4 FY26 (Mar 2026) |
|---|---|---|
| Revenue (₹ Cr) | 92.0 | 59.0 |
| Profit (₹ Cr) | 6.0 | 4.0 |
| Net Profit Margin (%) | 6.5 | 6.8 |
Why the margin is under pressure
The revenue surge is driven by a large, multi-year US carmaker order that entered full production last year. According to management commentary cited by Multibagg.ai, this contract alone is expected to contribute about ₹60 crore annually.
However, servicing this growth is expensive. Total expenses soared 77% year-on-year. Interest costs doubled as the company took on more short-term debt to fund its working capital needs. Depreciation also rose sharply, reflecting prior investments in a dedicated production line.
The cash flow trade-off
A critical divergence emerged between reported profit and cash generation. While net profit rose 54% for the half-year, operating cash flow turned negative, according to a report from ScanX.trade.
Live Chart
· EMMFORCE
(BSE)
ISIN: INE0SDC01012
This was due to a near-doubling of trade receivables, which ballooned to ₹62.9 crore by September end. The rapid sales growth is tying up cash in longer customer credit cycles, a typical challenge for export-heavy businesses scaling up.
The runway ahead
Management has set an ambitious target of ₹195 crore in revenue for the full FY27, as noted in an investor presentation. With an order book exceeding ₹500 crore, visibility is strong for the next few years.
The key question is when operating leverage will kick in. The company's automotive capacity is only 50-55% utilized, per its own disclosures. As volumes fill this headroom, fixed costs should spread out, potentially easing the margin pressure that defined this quarter.
Key Points
- Revenue reached a record ₹92 crore, growing 70% year-on-year, driven by the ramp-up of a major US export order.
- Net profit increased 50% to ₹6 crore, but the net profit margin declined due to faster growth in interest, depreciation, and other operating expenses.
- Operating cash flow turned negative as receivables nearly doubled, highlighting the working capital intensity of the current growth phase.
- With a multi-year order book above ₹500 crore and significant unused capacity, the company has clear revenue visibility for the coming quarters.
Hexa Perspective
This quarter confirms Emmforce Autotech is in a high-growth, investment-heavy phase. The top-line execution is impressive and validates its niche export strategy. However, the margin compression and negative cash flow signal that this growth is not yet efficient.
The investment case now hinges on the company's ability to convert its robust order book into sustained revenue while managing the associated working capital bulge. Margin improvement will be the next critical milestone, dependent on higher capacity utilization and stable raw material costs. Until then, the stock's premium valuation reflects future potential more than current profitability.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.