India Power (DPSCLTD) Q2 FY27 Profit Jumps 164% Despite Revenue Dip as Insolvency Looms
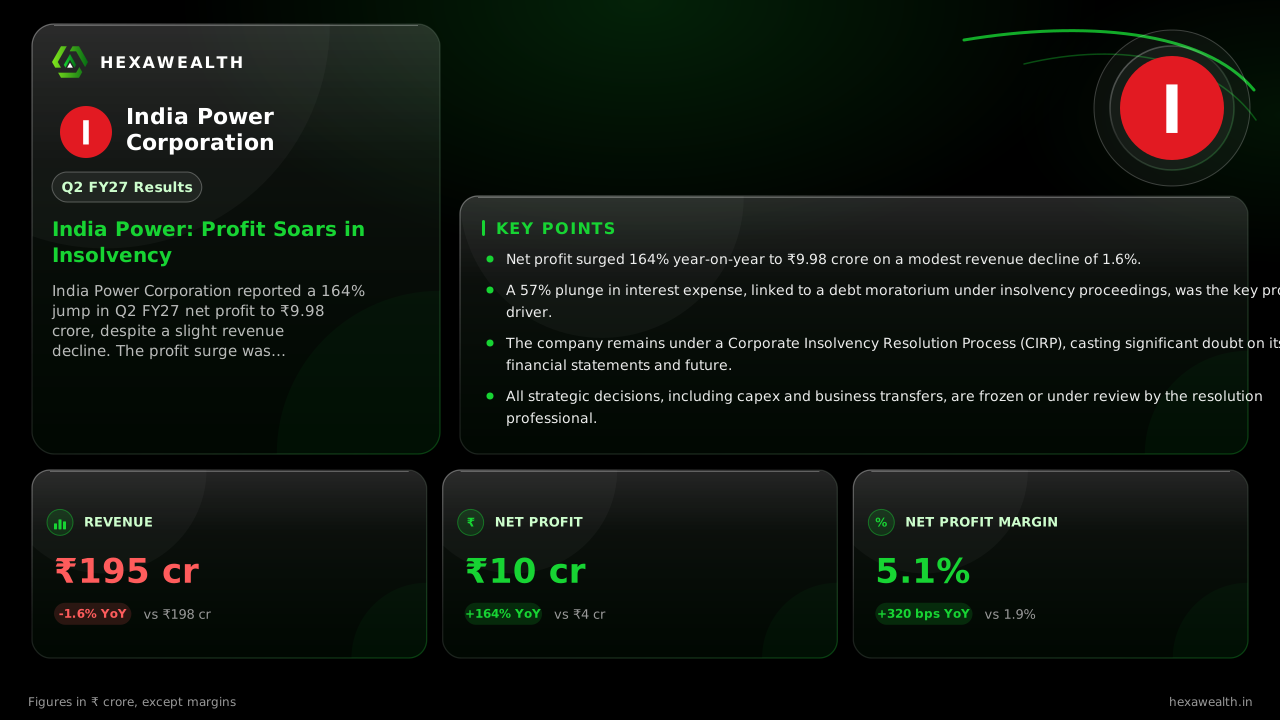
India Power Corporation's Q2 FY27 net profit surged 164% year-on-year to ₹9.98 crore, driven by a sharp fall in interest cost, even as revenue slipped 1.6%.
India Power Corporation reported a 164% jump in Q2 FY27 net profit to ₹9.98 crore, despite a slight revenue decline. The profit surge was fueled by a 57% drop in interest expense, though the company remains under a corporate insolvency resolution process.
For India Power Corporation, the September quarter was a story of financial efficiency under the shadow of insolvency. The century-old utility posted a 164% surge in net profit to ₹9.98 crore, even as its revenue edged down 1.6% to ₹194.7 crore.
The numbers show a company squeezing more from less. While revenue dipped slightly, net profit margin expanded by 320 basis points year-on-year to 5.1%. A sharp 57% fall in interest expense was the primary driver, alongside an 8% reduction in employee costs.
Revenue & profit
Revenue (₹ Cr.)
Profit (₹ Cr.)
- Revenue (₹ Cr.), Q2 FY26: 197.94
- Revenue (₹ Cr.), Q3 FY26: 155.32
- Revenue (₹ Cr.), Q4 FY26: 166.08
- Revenue (₹ Cr.), Q1 FY27: 186.93
- Revenue (₹ Cr.), Q2 FY27: 194.7
- Profit (₹ Cr.), Q2 FY26: 3.78
- Profit (₹ Cr.), Q3 FY26: 1.85
- Profit (₹ Cr.), Q4 FY26: 4.13
- Profit (₹ Cr.), Q1 FY27: 4.22
- Profit (₹ Cr.), Q2 FY27: 9.98
Revenue (₹ Cr.)
- Revenue (₹ Cr.), Q2 FY26: 197.94
- Revenue (₹ Cr.), Q3 FY26: 155.32
- Revenue (₹ Cr.), Q4 FY26: 166.08
- Revenue (₹ Cr.), Q1 FY27: 186.93
- Revenue (₹ Cr.), Q2 FY27: 194.7
Profit (₹ Cr.)
- Profit (₹ Cr.), Q2 FY26: 3.78
- Profit (₹ Cr.), Q3 FY26: 1.85
- Profit (₹ Cr.), Q4 FY26: 4.13
- Profit (₹ Cr.), Q1 FY27: 4.22
- Profit (₹ Cr.), Q2 FY27: 9.98
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY26: 1.9
- Net Profit Margin (%), Q3 FY26: 1.2
- Net Profit Margin (%), Q4 FY26: 2.5
- Net Profit Margin (%), Q1 FY27: 2.3
- Net Profit Margin (%), Q2 FY27: 5.1
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr.) | 194.7YoY -1.6% | 186.93 | 197.94 |
| Profit (₹ Cr.) | 9.98YoY +164% | 4.22 | 3.78 |
| Net Profit Margin (%) | 5.1YoY +168% | 2.3 | 1.9 |
Why the profit jumped as sales fell
The dramatic profit increase stems from a steep drop in finance costs, which fell to ₹1.88 crore from ₹4.36 crore a year ago. Reports from MCapital indicate this is linked to the Corporate Insolvency Resolution Process (CIRP) that began in May 2026, which includes a moratorium on debt repayments. Lower employee and total expenses also contributed to the margin expansion.
The overhang that defines the quarter
Every financial metric is now viewed through the lens of the ongoing CIRP. The company's results for the prior quarter drew an adverse conclusion from its reviewer, who noted ₹8,720 crore of admitted creditor claims were not recognized as liabilities. The resolution professional has also put a past business transfer agreement under review for potential avoidance.
This creates material uncertainty over the company's ability to continue as a going concern, as noted in the review. The insolvency process freezes major capital expenditure and keeps equity under a potential wipe-out risk, overshadowing any operational efficiency gains.
Live Chart
· DPSCLTD
(BSE)
ISIN: INE360C01024
Key Points
- Net profit surged 164% year-on-year to ₹9.98 crore on a modest revenue decline of 1.6%.
- A 57% plunge in interest expense, linked to a debt moratorium under insolvency proceedings, was the key profit driver.
- The company remains under a Corporate Insolvency Resolution Process (CIRP), casting significant doubt on its financial statements and future.
- All strategic decisions, including capex and business transfers, are frozen or under review by the resolution professional.
Hexa Perspective
This quarter's profit spike is a function of financial distress, not operating strength. The interest cost relief is temporary, granted by the insolvency moratorium. The reported numbers are also qualified, with a reviewer noting billions in unrecorded creditor claims.
The path forward is binary: a successful resolution plan that restructures the business, or liquidation. Until that clarity arrives, the operational metrics are secondary to the legal and financial restructuring underway. Investors are weighing a potential recovery against the high risk of equity erosion.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.