Bambino Agro (BAMBINO) Q2 FY27 Profit Rises 7% as Cost Control Offsets Flat Sales
The packaged foods maker posted a 7.2% rise in Q2 FY27 net profit to ₹5.2 crore, driven by disciplined expense management despite revenue growing just 1% year-on-year.
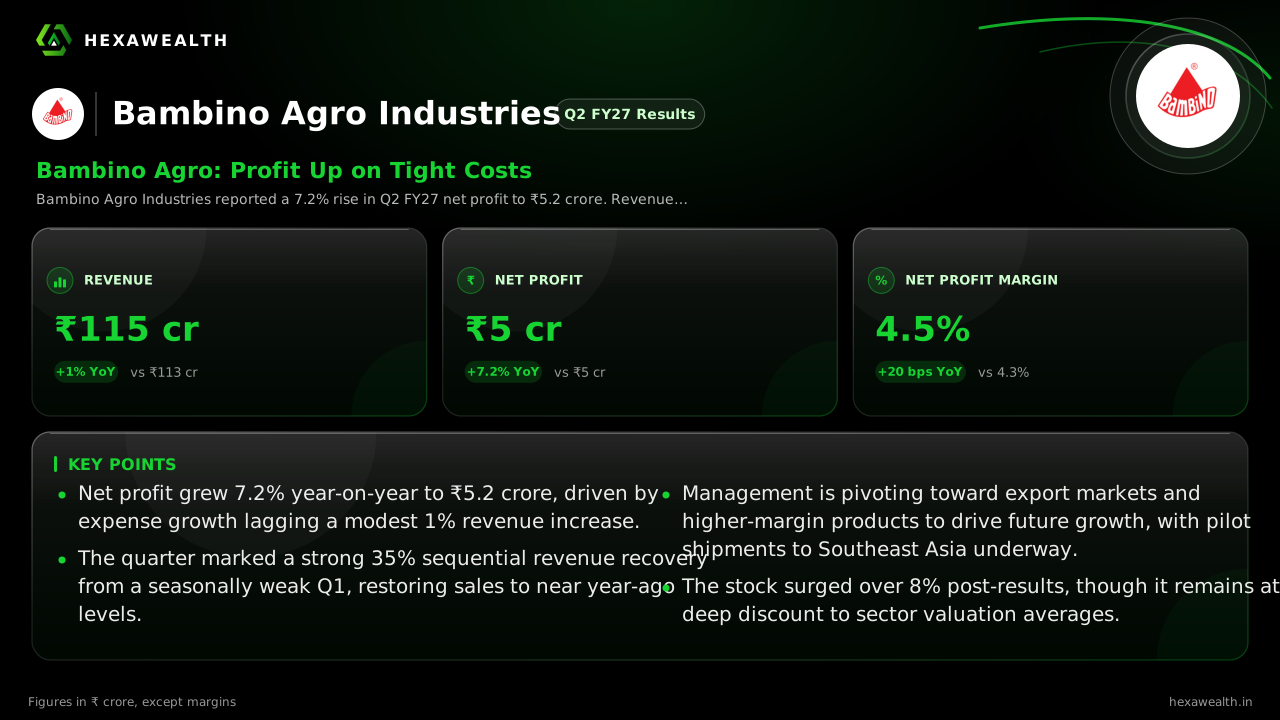
Bambino Agro Industries reported a 7.2% rise in Q2 FY27 net profit to ₹5.2 crore. Revenue was nearly flat at ₹114.64 crore, but tight cost control expanded the net profit margin to 4.5%.
For Bambino Agro Industries, a maker of staple foods like pasta and vermicelli, the September quarter was about holding the line. Revenue was nearly flat, but a disciplined grip on costs delivered a 7.2% rise in net profit to ₹5.2 crore.
The scorecard shows a business stabilizing. Revenue of ₹114.64 crore was up just 1% from a year ago, but it marked a strong 35% sequential rebound from a weak June quarter. Profit growth outpaced the top line, lifting the net profit margin 20 basis points to 4.5%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 113.45
- Revenue (₹ Cr), Q3 FY26: 93.36
- Revenue (₹ Cr), Q4 FY26: 98.61
- Revenue (₹ Cr), Q1 FY27: 84.70
- Revenue (₹ Cr), Q2 FY27: 114.64
- Profit (₹ Cr), Q2 FY26: 4.85
- Profit (₹ Cr), Q3 FY26: 1.16
- Profit (₹ Cr), Q4 FY26: 0.41
- Profit (₹ Cr), Q1 FY27: 3.39
- Profit (₹ Cr), Q2 FY27: 5.20
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 113.45
- Revenue (₹ Cr), Q3 FY26: 93.36
- Revenue (₹ Cr), Q4 FY26: 98.61
- Revenue (₹ Cr), Q1 FY27: 84.70
- Revenue (₹ Cr), Q2 FY27: 114.64
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26: 4.85
- Profit (₹ Cr), Q3 FY26: 1.16
- Profit (₹ Cr), Q4 FY26: 0.41
- Profit (₹ Cr), Q1 FY27: 3.39
- Profit (₹ Cr), Q2 FY27: 5.20
Net Profit Margin
- Net Profit Margin, Q2 FY26: 4.3%
- Net Profit Margin, Q3 FY26: 1.2%
- Net Profit Margin, Q4 FY26: 0.4%
- Net Profit Margin, Q1 FY27: 4.0%
- Net Profit Margin, Q2 FY27: 4.5%
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 114.64YoY +1% | 84.70 | 113.45 |
| Profit (₹ Cr) | 5.20YoY +7.2% | 3.39 | 4.85 |
| Net Profit Margin | 4.5%YoY +4.7% | 4.0% | 4.3% |
How margins held firm
The profit improvement came from holding expenses in check. According to a scanx.trade report, while revenue grew 1.05% year-on-year, total expenses rose by only 0.48%. This tighter cost control expanded the pre-tax profit margin.
Other income also contributed, tripling to ₹8.30 lakh. Interest costs, however, rose 8% from the year-ago quarter, reflecting the company's ongoing debt load.
The seasonal rebound and the road ahead
The sharp sequential jump in revenue follows typical post-monsoon patterns in agricultural processing, as noted by scanx.trade. Management's focus, per a StockFin.ai analysis, is now on scaling higher-margin products and exports to Southeast Asia.
Live Chart
· BAMBINO
(BSE)
ISIN: INE921D01013
No formal guidance was given, but the company indicated export demand should drive second-half growth. The strategy hinges on premiumization, moving beyond domestic volume-driven sales.
Investors cheered the profit beat, sending shares up over 8% on the results day, reports HDFC Sky. The stock trades at a P/E of 18.9, a significant discount to the industry average of 37.6.
Key Points
- Net profit grew 7.2% year-on-year to ₹5.2 crore, driven by expense growth lagging a modest 1% revenue increase.
- The quarter marked a strong 35% sequential revenue recovery from a seasonally weak Q1, restoring sales to near year-ago levels.
- Management is pivoting toward export markets and higher-margin products to drive future growth, with pilot shipments to Southeast Asia underway.
- The stock surged over 8% post-results, though it remains at a deep discount to sector valuation averages.
Hexa Perspective
This quarter demonstrates Bambino Agro's ability to protect profitability in a no-growth sales environment. The margin defense through cost control is a positive operational signal.
The path forward, however, requires reigniting the top line. The company's export-led premiumization plan is the stated route, but it faces logistical hurdles and is untested at scale. Success there will determine if this is a story of resilient stability or the beginning of a new growth phase.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.