Balurghat Technologies (BALTE) Q2 FY27' Record Revenue Fails to Stem Widening Loss
The logistics firm posted its highest-ever quarterly sales, but surging costs and debt-financed growth pushed it back into a loss.
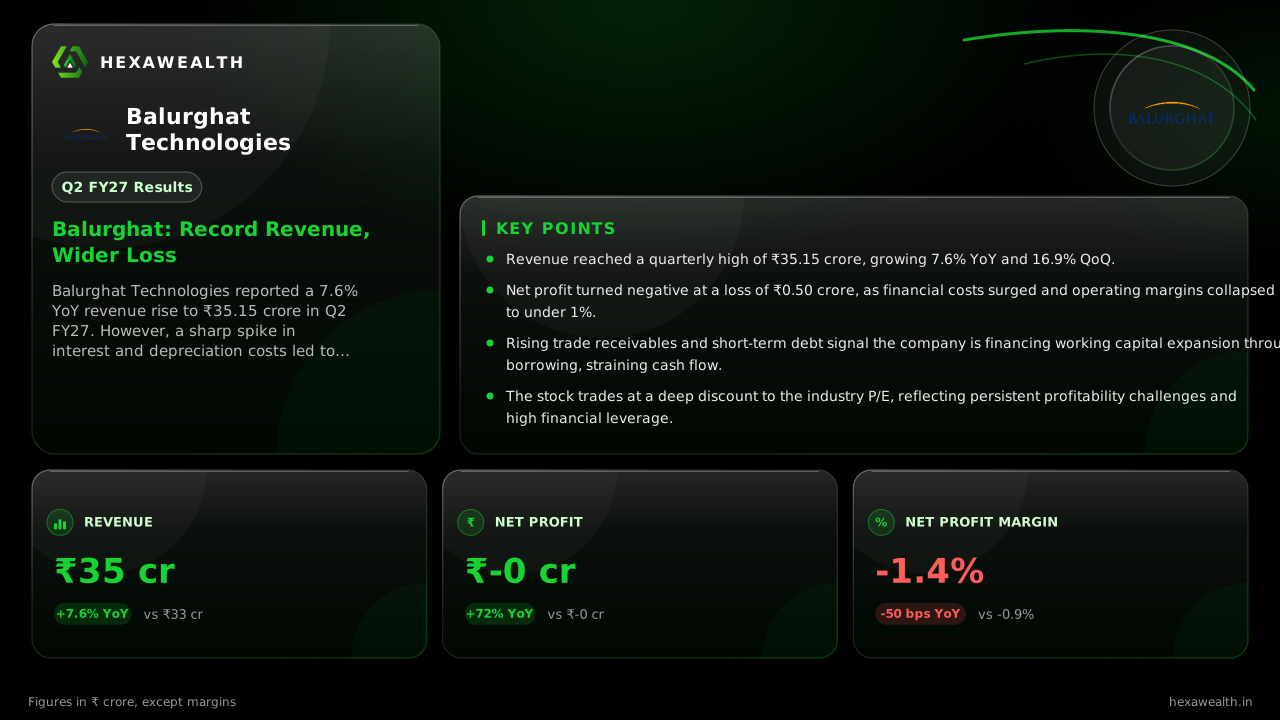
Balurghat Technologies reported a 7.6% YoY revenue rise to ₹35.15 crore in Q2 FY27. However, a sharp spike in interest and depreciation costs led to a net loss of ₹0.50 crore, widening from the loss a year ago.
For a logistics operator, growth is only as good as the cash it generates. Balurghat Technologies hit a revenue high this quarter, but the cost of that expansion consumed all its operating profit and more, pushing the firm back into the red.
The numbers show a clear split. Revenue climbed 7.6% year-on-year and nearly 17% sequentially to a record ₹35.15 crore. Yet, the bottom line swung to a loss of ₹0.50 crore from a profit of ₹0.31 crore last quarter.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
| Metric | CurrentQ2 FY27 (Sep '26) | PreviousQ1 FY27 (Jun '26) |
|---|---|---|
| Revenue (₹ Cr) | 35.15 | 30.07 |
| Net Profit (₹ Cr) | -0.50 | 0.31 |
| PAT Margin | -1.4% | 1.0% |
Why the profit vanished
A thin operating margin of just 0.94%, as reported by MarketsMojo, was wiped out by a steep rise in financial charges. Interest expense jumped 36.4% quarter-on-quarter to ₹0.82 crore, reflecting higher short-term borrowings. Depreciation nearly tripled, rising 174% sequentially to ₹0.20 crore.
These costs point to a business funding growth through debt, not internal cash. Research from ScanX Trade shows trade receivables surged by over ₹7 crore in six months, indicating working capital is being financed externally. This creates a cash flow mismatch that pressures liquidity.
The leverage trap
With a debt-to-equity ratio of 1.5 and no institutional investor ownership, the company's financial flexibility is constrained. MarketsMojo notes the EBIT-to-interest coverage ratio is weak and deteriorated further this quarter. High leverage amplifies risk when operating margins are this slim.
The market reaction was muted but telling. The stock closed at ₹12.60 on November 13, the day of the announcement, and has fallen 22.3% over the past year. The valuation trades at a significant discount to the industry, with a P/E of 15.4 against a sector average of 48.8.
Key Points
- Revenue reached a quarterly high of ₹35.15 crore, growing 7.6% YoY and 16.9% QoQ.
- Net profit turned negative at a loss of ₹0.50 crore, as financial costs surged and operating margins collapsed to under 1%.
- Rising trade receivables and short-term debt signal the company is financing working capital expansion through borrowing, straining cash flow.
- The stock trades at a deep discount to the industry P/E, reflecting persistent profitability challenges and high financial leverage.
Hexa Perspective
The quarter underscores a fundamental tension for Balurghat. It can win business and grow the top line, but it lacks the pricing power or operational efficiency to convert that into sustainable profit. The core issue is that revenue growth is being funded by debt, not accruals.
For the trend to reverse, operating margins must recover decisively above 3% to cover the high interest burden. Until the company demonstrates an ability to generate cash from its operations, the attractive valuation multiple is likely a value trap, not an opportunity.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.