All posts

Follow Us

LinkedInInstagramX
Quarterly ResultsArchiveLast updated 11 November 20262 min read

Ambika Cotton Mills (AMBIKCO) Q2 FY27 Profit Soars 69% as Exports Drive Growth

The specialty yarn maker posted a 69% surge in Q2 profit, driven by strong export demand and disciplined capacity utilization, even as raw cotton costs remain volatile.

By Vinayak Gandhi, CFA · Created 11 November 2026

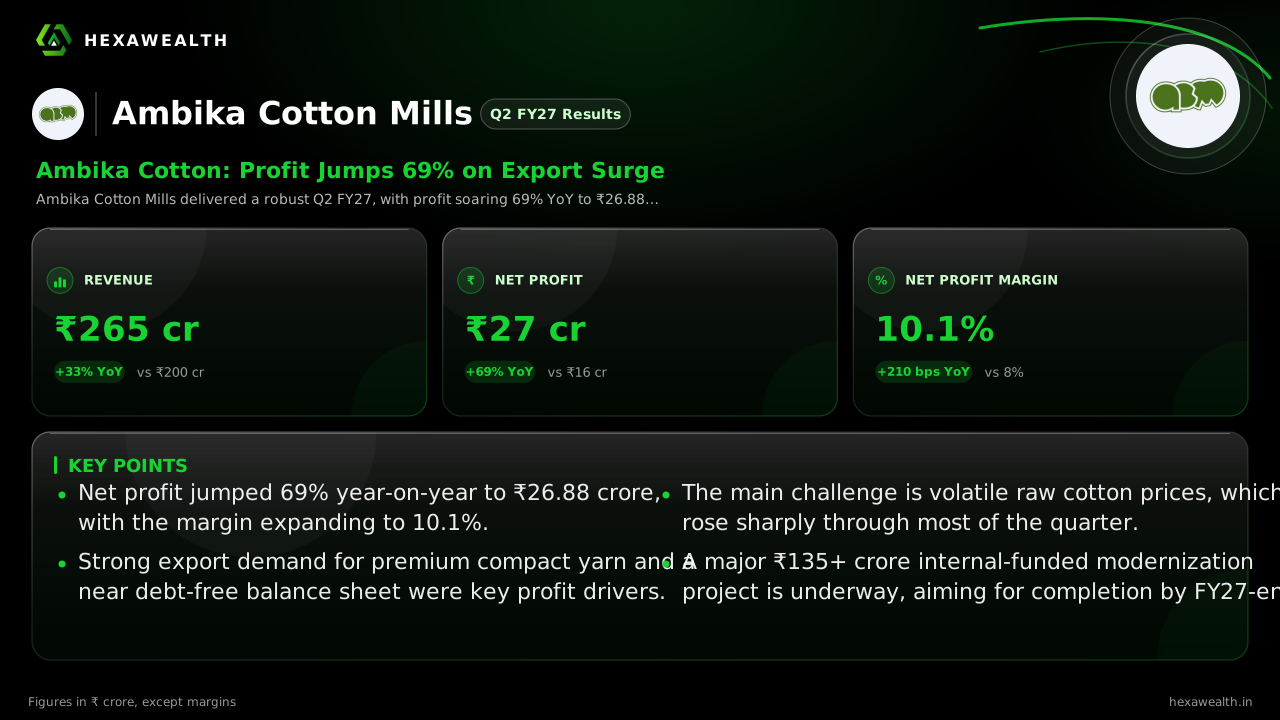
Ambika Cotton Mills delivered a robust Q2 FY27, with profit soaring 69% YoY to ₹26.88 crore. Revenue grew 33% to ₹265 crore, supported by export recovery and operational efficiency, while a lean balance sheet kept interest costs low.

For a specialty cotton yarn maker, the story is always about managing the spread between raw material costs and finished product realizations. Ambika Cotton Mills delivered a strong quarter by doing exactly that, with profit surging 69% year-on-year on the back of disciplined operations and recovering export demand.

The numbers show a clear trajectory. Revenue rose 33% to ₹265 crore, while net profit climbed to ₹26.88 crore. The net profit margin expanded by 210 basis points to 10.1%, a sign of improving operational leverage.

Revenue & profit

Revenue (₹ Cr)

Profit (₹ Cr)

Revenue & profitQ2 FY26 199.64, Q3 FY26 174.17, Q4 FY26 215.16, Q1 FY27 257.92, Q2 FY27 264.98. Q2 FY26 15.94, Q3 FY26 15.17, Q4 FY26 24.53, Q1 FY27 25.70, Q2 FY27 26.880100200300400Q2 '26Q3 '26Q4 '26Q1 '27Q2 '27
  • Revenue (₹ Cr), Q2 FY26: 199.64
  • Revenue (₹ Cr), Q3 FY26: 174.17
  • Revenue (₹ Cr), Q4 FY26: 215.16
  • Revenue (₹ Cr), Q1 FY27: 257.92
  • Revenue (₹ Cr), Q2 FY27: 264.98
  • Profit (₹ Cr), Q2 FY26: 15.94
  • Profit (₹ Cr), Q3 FY26: 15.17
  • Profit (₹ Cr), Q4 FY26: 24.53
  • Profit (₹ Cr), Q1 FY27: 25.70
  • Profit (₹ Cr), Q2 FY27: 26.88

Revenue (₹ Cr)

Revenue (₹ Cr)Q2 FY26 199.64, Q3 FY26 174.17, Q4 FY26 215.16, Q1 FY27 257.92, Q2 FY27 264.980100200300400Q2 '26Q3 '26Q4 '26Q1 '27Q2 '27
  • Revenue (₹ Cr), Q2 FY26: 199.64
  • Revenue (₹ Cr), Q3 FY26: 174.17
  • Revenue (₹ Cr), Q4 FY26: 215.16
  • Revenue (₹ Cr), Q1 FY27: 257.92
  • Revenue (₹ Cr), Q2 FY27: 264.98

Profit (₹ Cr)

Profit (₹ Cr)Q2 FY26 15.94, Q3 FY26 15.17, Q4 FY26 24.53, Q1 FY27 25.70, Q2 FY27 26.88010203040Q2 '26Q3 '26Q4 '26Q1 '27Q2 '27
  • Profit (₹ Cr), Q2 FY26: 15.94
  • Profit (₹ Cr), Q3 FY26: 15.17
  • Profit (₹ Cr), Q4 FY26: 24.53
  • Profit (₹ Cr), Q1 FY27: 25.70
  • Profit (₹ Cr), Q2 FY27: 26.88

Net Profit Margin (%)

Net Profit Margin (%)Q2 FY26 8.0, Q3 FY26 8.7, Q4 FY26 11.4, Q1 FY27 10.0, Q2 FY27 10.10%5%10%15%20%Q2 '26Q3 '26Q4 '26Q1 '27Q2 '27
  • Net Profit Margin (%), Q2 FY26: 8.0
  • Net Profit Margin (%), Q3 FY26: 8.7
  • Net Profit Margin (%), Q4 FY26: 11.4
  • Net Profit Margin (%), Q1 FY27: 10.0
  • Net Profit Margin (%), Q2 FY27: 10.1
MetricCurrentQ2 FY27PreviousQ1 FY27Same quarter LYQ2 FY26
Revenue (₹ Cr)
264.98YoY +33%
257.92
199.64
Profit (₹ Cr)
26.88YoY +69%
25.70
15.94
Net Profit Margin (%)
10.1YoY +26%
10.0
8.0

The Export Engine Firing

Growth was led by a rebound in export demand for compact and high-count yarn, used in premium shirting and athleisure. Reports from Sahi Markets and StockFin.ai highlight disciplined capacity utilization and favorable spread dynamics as key drivers. The company's focus on this niche segment allowed it to capitalize on the recovery.

A Leaner Balance Sheet Lifts Margins

A significant contributor to the margin expansion was a sharp 29% year-on-year drop in interest expense. According to SectorAlpha, this reflects a visible debt reduction following a strong operating cash flow inflection in FY26. With a debt-to-equity ratio of just 0.1, the company has ample financial headroom.

The Volatility That Remains

The primary risk is raw material cost. Industry reports note cotton yarn prices rose about 60% from January to September 2026, squeezing downstream fabric makers. While prices eased slightly by late September, the underlying domestic cotton shortfall persists. Managing this input cost volatility is the critical swing factor for margins going forward.

Live Chart

· AMBIKCO

(BSE)

ISIN: INE540G01014

The company is funding a ₹135-138 crore modernization of Unit 4 internally, targeting completion by March 2027. This upgrade aims to boost productivity, not just capacity. As noted by Arthneeti.com, the focus remains on efficiency and product differentiation to sustain competitiveness.

Key Points

  • Net profit jumped 69% year-on-year to ₹26.88 crore, with the margin expanding to 10.1%.
  • Strong export demand for premium compact yarn and a near debt-free balance sheet were key profit drivers.
  • The main challenge is volatile raw cotton prices, which rose sharply through most of the quarter.
  • A major ₹135+ crore internal-funded modernization project is underway, aiming for completion by FY27-end.

Hexa Perspective

Ambika Cotton's quarter demonstrates effective execution in a favorable demand window. The profit growth is high-quality, driven by operating leverage and lower finance costs rather than one-offs. The sustainability of this run hinges on two factors: the company's ability to navigate volatile cotton costs, and the continued strength of export orders for its premium yarn. The internal funding of its capex preserves a robust balance sheet, a clear positive in a cyclical industry.

Share or follow HexaWealth

Also read

Want this applied to your portfolio?

Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
Ambika Cotton Mills (AMBIKCO) Q2 FY27 results, revenue and profits.

Frequently asked questions

What were Ambika Cotton Mills' Q2 FY27 results?
Ambika Cotton Mills reported a standalone net profit of ₹26.88 crore for Q2 FY27 (July-September 2026), a 69% increase from ₹15.94 crore a year ago. Revenue from operations grew 33% year-on-year to ₹264.98 crore, driven by strong export demand for its specialty cotton yarn.
Why did Ambika Cotton Mills' Q2 profit jump 69%?
Ambika Cotton Mills' Q2 FY27 profit surged due to strong export demand for its compact and high-count yarn and significantly lower interest costs. Interest expense fell 29% year-on-year as the company reduced debt, which helped expand the net profit margin by 210 basis points.
What was Ambika Cotton Mills' net profit margin in Q2 FY27?
Ambika Cotton Mills' net profit margin was 10.1% in Q2 FY27, an improvement of 210 basis points from 8.0% in the same quarter last year. The expansion was aided by operational efficiency and a sharp reduction in finance costs.
What is driving revenue growth for Ambika Cotton Mills?
Revenue growth for Ambika Cotton Mills is being driven by a recovery in export demand for its premium compact cotton yarn, used in shirting and athleisure. Reports from Sahi Markets highlight disciplined capacity utilization and favorable spread dynamics in this segment.
Why did interest expense fall for Ambika Cotton Mills?
Ambika Cotton Mills' interest expense fell 29% year-on-year in Q2 FY27 due to debt reduction. According to SectorAlpha, strong operating cash flow in FY26 allowed the company to reduce borrowings, leading to lower finance costs and a healthier balance sheet.
What are Ambika Cotton Mills' capex plans?
Ambika Cotton Mills is undertaking a ₹135-138 crore modernization of its Unit 4, to be funded entirely through internal accruals. The project, aimed at boosting productivity and automation, is targeted for completion by March 2027, as noted in reports from Arthneeti.com and StockFin.ai.
What is the outlook for cotton prices affecting Ambika Cotton?
Cotton yarn prices rose about 60% from January to September 2026, creating cost pressure. While prices eased slightly by late September, a domestic cotton shortfall and volatile global markets remain key risks for input costs, as reported by industry sources like Bennycotts.com.
Did Ambika Cotton Mills' Q2 results beat analyst estimates?
No verified public analyst consensus estimates were available for Ambika Cotton Mills' Q2 FY27 results, as noted by Univest.in. The performance is best measured against its year-ago base of ₹199.64 crore in revenue and ₹15.94 crore in profit, both of which it surpassed significantly.
What is the capacity utilization for Ambika Cotton Mills?
While a specific figure for Q2 is not provided, reports from Sahi Markets indicate the company benefits from 'disciplined capacity utilization' in its compact yarn segment. Past commentary has highlighted that utilization levels are a key trigger factor for operational performance.
Have FIIs or DIIs changed their stake in Ambika Cotton Mills?
Yes, according to DalalOS shareholding data, Foreign Institutional Investors (FIIs) increased their stake to 0.79% in September 2026 from 0.47% in June 2026. Domestic Institutional Investor (DII) holding remained steady at 1.71% over the same period.
Ambika Cotton Mills Q2 net profit
Ambika Cotton Mills' Q2 FY27 (September 2026 quarter) standalone net profit was ₹26.88 crore. This represents a strong 69% growth compared to the net profit of ₹15.94 crore reported in the same quarter of the previous fiscal year.
Ambika Cotton Mills Q2 FY27 results August 2026
Ambika Cotton Mills' Q2 FY27 results, for the quarter ended September 2026, were announced on 14 November 2026. The company reported revenue of ₹264.98 crore and a net profit of ₹26.88 crore, marking significant year-on-year growth.